Nifty Chronicles
NIFTY 50 Pre-Market Analysis — Tuesday, 6 October 2026
Weekly expiry Tue, 06 Oct · Monthly expiry Tue, 27 Oct · Weekly expiry day (Tuesday 06-Oct contract). Monday's rebound closed +0.60% at 22,555.75, but official breadth was negative (A/D 0.88) and the move was heavyweight-led. GIFT Nifty holds a ~103-point gap-up ahead of the 09:15 open, and the RBI's rate decision lands tomorrow (Wed 07-Oct). · Published ~07:55 IST, before the 09:15 open. Informational & educational only — no trade recommendations (SEBI-compliant).
1. Global Cues Snapshot
GIFT NIFTY — full OHLC (quote saved 06:28 AM, 6 min before render)
| Metric | Value | Metric | Value |
|---|---|---|---|
| LTP | 22,659.00 | Change | 83.00 (+0.37%) |
| Open | 22,640.00 | Day High | 22,723.00 |
| Day Low | 22,501.00 | Prev Close | 22,576.00 |
| Implied gap vs NIFTY 22,555.75 | 103.3 pts | vs own prev close | 83.0 pts |
Cross-check source: 22,647.50 — agrees
Gap read: GIFT Nifty prints 22,659 (+83 vs its own prior close; O 22,640 / H 22,723 / L 22,501), which is +103 points versus NIFTY's official 05-Oct close — a modest gap-up open. The day low holding above GIFT's own prior close reads as an overnight bullish hold rather than a rejected rally, and the niftytrader cross-read (22,647.5) agrees within tolerance. Treat this as the pre-market state, not a live tape: the quote is the 06:28 IST session-break read.
| Market / Asset | Level | Change | Session OHLC |
|---|---|---|---|
| S&P 500 | 7,773.95 | +0.66% | — |
| Dow Jones | 51,267.90 | +0.18% | — |
| Nasdaq Composite | 27,477.31 | +1.05% | — |
| CBOE VIX | 15.52 | +1.37% | — |
| FTSE 100 | 10,497.94 | +0.34% | O 10,462.38 · H 10,527.46 · L 10,451.73 |
| DAX | 25,254.21 | +0.09% | O 25,251.39 · H 25,324.70 · L 25,143.26 |
| CAC 40 | 7,834.10 | −0.80% | O 0.00 · H 0.00 · L 0.00 |
| Euro Stoxx 50 | 6,242.14 | +0.06% | O 0.00 · H 0.00 · L 0.00 |
| Nikkei 225 | 70,242.43 | +0.42% | O 69,954.61 · H 70,355.93 · L 69,813.16 |
| Hang Seng | 24,040.34 | +0.28% | O 23,963.41 · H 24,040.34 · L 23,835.68 |
| Shanghai Composite | 3,842.20 | +0.31% | O 3,839.25 · H 3,851.22 · L 3,833.09 |
| KOSPI | 7,014.39 | +0.15% | O 7,044.67 · H 7,044.67 · L 6,980.39 |
| Taiwan TAIEX | 49,712.04 | +2.55% | O 48,574.95 · H 49,770.66 · L 48,574.95 |
| ASX 200 | 8,723.80 | +0.43% | O 8,686.40 · H 8,729.50 · L 8,686.40 |
| Straits Times | 5,664.33 | +0.52% | O 5,650.28 · H 5,674.02 · L 5,632.01 |
| Sensex | 72,382.47 | +0.66% | O 72,340.95 · H 72,631.93 · L 71,840.18 |
| USD/INR | 96.30 | 0.00% | — |
| Dollar Index (DXY) | 102.16 | −0.01% | — |
| Brent crude | 100.48 | +0.16% | — |
| WTI crude | 89.43 | 0.00% | — |
| Gold (USD) | 4,164.40 | +0.18% | — |
| Infosys (ADR) | 10.76 | −2.54% | — |
| HDFC Bank (ADR) | 22.11 | −1.03% | — |
| ICICI Bank (ADR) | 27.75 | +1.13% | — |
| Wipro (ADR) | 1.69 | −1.74% | — |
| India VIX | 14.78 | — | prior session close |
Global read: Risk-on overnight: the Nasdaq notched a record close (+1.05%), the S&P 500 added 0.66% on earnings focus, and Asia is firm into the Indian open (Taiwan +2.55%, Nikkei +0.42% with the tech complex bid). The caveat is domestic: Indian IT ADRs fell hard against that tape (Infosys -2.5%, Wipro -1.7% while ICICI Bank +1.1%), so the global bid arrives with a sector-level IT divergence and a DXY +0.23% / USD-INR ~96.3 backdrop that still leans against EM flows.
2. Critical Macro Indicators
| Indicator | Value | Change | Status |
|---|---|---|---|
| Brent / WTI | $100.48 / $89.43 | +0.16% / 0.00% | — |
| USD/INR · DXY | 96.30 · 102.16 | 0.00% · −0.01% | — |
| India VIX | 14.775 | — | — |
| Gold (₹/10g) | ₹1,49,312 | −0.92% / 10d | — |
| Yield curve 10Y–2Y | 0.47 pp (47 bps) | 2026-10-05 | 🟢 positive |
| Yield curve 10Y–3M | 1.09 pp (109 bps) | 2026-10-05 | 🟢 positive |
| NY Fed recession prob. | 13.88% | 12-mo ahead Aug 2027; data through Aug 2026; updated 06-Sep-2026 | 🟢 low |
| Sahm Rule | 0 | 2026-09-01 | 🟢 no trigger |
| HY / IG credit spreads | 310 / 85 bps | 2026-10-02 | 🟢 normal |
| VIX term structure | VIX9D 12.85 < VIX 15.52 < VIX3M 18 | — | 🟡 contango |
| Shiller CAPE / Buffett | 41.67 / 244% | 2026-10-06 | 🔴 bubble territory |
| TED spread | discontinued by FRED (last obs 2022-01-21) — retained as a framework footnote only | ||
Crude: Brent trades ~$100.5 (about -1.7% versus its prior completed daily bar) and WTI ~$89.4 — the pullback helps, but Brent at triple digits remains a structural headwind for India's import bill, and Polymarket still assigns a ~28% chance to WTI touching $100 in October. On the domestic tape MCX CRUDEOIL is at 8,684/bbl (-232, -2.60%), with the page flagging the 9,000 call wall as immediate resistance.
Currency: USD/INR is pinned around 96.30 (essentially flat) while DXY ticks up 0.23% to 102.16 — no fresh rupee record this morning, but the combination of a strong dollar and persistent FII cash selling keeps the currency as the pressure valve to watch. Nothing in the overnight tape changes that setup.
Gold: Gold's single-session move is the stress tell of the day: 24k jumped +2,416 to 1,49,312 per 10g (+1.62% — the site's own row-level change), past the cluster's >1.5% flag threshold, even as its 10-day trend is still negative. Caveat disclosed rather than dropped: the same page's headline widget prints +1,588 (1.06%) off a 147,724 prior-close reference, so the size of the print is source-ambiguous even though the direction is not. COMEX gold at 4,164/oz is essentially flat (+0.18%), so the INR leg carries most of the move — a bid to watch, not yet a risk-off signal on its own.
Yield curve: The US curve stays un-inverted and steepening: 10Y-2Y +47 bps and 10Y-3M +109 bps (both 05-Oct), with the NY Fed's 12-month recession probability unchanged at 13.88% (data through Aug-2026). This is the benign part of the macro board — no curve-based warning today.
Credit: Credit is calm: HY OAS 310 bps and IG OAS 85 bps (02-Oct prints, both well inside stress thresholds). Margin debt carries the August FINRA vintage (USD 1.45tn, +37.2% y/y) as the one classic flag still reading hot; it is a monthly series and unchanged since the last release.
3. Economic Events — Today & This Week
Today (2026-10-06 — IST)
| Time (IST) | Event | Ccy | Impact | Forecast vs prev |
|---|---|---|---|---|
| 02:30 | NZIER Business Confidence | NZD | Low | F: · P: 8 |
| 04:31 | Bank Holiday | CNY | Holiday | F: · P: |
| 05:00 | Westpac Consumer Sentiment | AUD | Low | F: · P: -5.2% |
| 06:00 | ANZ Job Advertisements m/m | AUD | Low | F: · P: 2.5% |
| 09:05 | 10-y Bond Auction | JPY | Low | F: · P: 3.00|3.3 |
| 11:30 | German Factory Orders m/m | EUR | Low | F: -0.9% · P: 2.5% |
| 12:05 | BOJ Gov Ueda Speaks | JPY | High | F: · P: |
| 12:15 | French Gov Budget Balance | EUR | Low | F: · P: -145.9B |
| 12:15 | French Industrial Production m/m | EUR | Low | F: 0.2% · P: -0.4% |
| 12:30 | Unemployment Rate | CHF | Low | F: 3.1% · P: 3.1% |
| 14:00 | Construction PMI | GBP | Low | F: 45.0 · P: 44.3 |
| 14:00 | MPC Member Mann Speaks | GBP | Low | F: · P: |
| 14:00 | Housing Equity Withdrawal q/q | GBP | Low | F: -11.9B · P: -12.6B |
| 14:30 | Retail Sales m/m | EUR | Low | F: 0.2% · P: -0.6% |
| 17:45 | ADP Weekly Employment Change | USD | Low | F: · P: |
| 17:46 | ADP Weekly Employment Change | USD | Low | F: · P: 20.0K |
| 18:00 | Trade Balance | CAD | Low | F: 1.5B · P: 0.8B |
| 18:00 | Trade Balance | USD | Low | F: -100.8B · P: -88.6B |
| 19:30 | Ivey PMI | CAD | Medium | F: 65.2 · P: 64.3 |
| 19:40 | RCM/TIPP Economic Optimism | USD | Low | F: 44.5 · P: 45.6 |
| 20:15 | FOMC Member Bowman Speaks | USD | Low | F: · P: |
| 20:20 | GDT Price Index | NZD | Low | F: · P: -1.1% |
| 22:45 | FOMC Member Schmid Speaks | USD | Low | F: · P: |
Rest of the week (high/medium impact)
| Date | Time (IST) | Event | Ccy | Impact |
|---|---|---|---|---|
| 2026-10-07 | 02:00 | API Weekly Statistical Bulletin | USD | Low |
| 2026-10-07 | 04:31 | Bank Holiday | CNY | Holiday |
| 2026-10-07 | 05:00 | Average Cash Earnings y/y | JPY | Low |
| 2026-10-07 | 10:30 | Leading Indicators | JPY | Low |
| 2026-10-07 | 11:30 | German Industrial Production m/m | EUR | Low |
| 2026-10-07 | 11:30 | Lloyds HPI m/m | GBP | Low |
| 2026-10-07 | 12:15 | French Trade Balance | EUR | Low |
| 2026-10-07 | 12:30 | Foreign Currency Reserves | CHF | Low |
| 2026-10-07 | 20:00 | Crude Oil Inventories | USD | Low |
| 2026-10-07 | 22:31 | 10-y Bond Auction | USD | Low |
| 2026-10-07 | 23:30 | FOMC Meeting Minutes | USD | High |
| 2026-10-08 | 00:30 | Consumer Credit m/m | USD | Low |
| 2026-10-08 | 04:31 | RICS House Price Balance | GBP | Low |
| 2026-10-08 | 05:20 | Current Account | JPY | Low |
| 2026-10-08 | 05:30 | MI Inflation Expectations | AUD | Low |
| 2026-10-08 | 09:05 | 30-y Bond Auction | JPY | Low |
| 2026-10-08 | 10:30 | Economy Watchers Sentiment | JPY | Low |
| 2026-10-08 | 11:30 | German Trade Balance | EUR | Low |
| 2026-10-08 | 13:35 | Gov Board Member Martin Speaks | CHF | Low |
| 2026-10-08 | 14:00 | BOE Credit Conditions Survey | GBP | Low |
| 2026-10-08 | 14:00 | FOMC Member Waller Speaks | USD | Medium |
| 2026-10-08 | 14:45 | MPC Member Greene Speaks | GBP | Low |
| 2026-10-08 | 14:45 | Eurogroup Meetings | EUR | Low |
| 2026-10-08 | 16:00 | MPC Member Pill Speaks | GBP | Low |
| 2026-10-08 | 17:00 | ECB Monetary Policy Meeting Accounts | EUR | Low |
| 2026-10-08 | 17:45 | BOE Gov Bailey Speaks | GBP | High |
| 2026-10-08 | 18:00 | Unemployment Claims | USD | Medium |
| 2026-10-08 | 18:30 | MPC Member Lombardelli Speaks | GBP | Low |
| 2026-10-08 | 19:30 | Final Wholesale Inventories m/m | USD | Low |
| 2026-10-08 | 20:00 | Natural Gas Storage | USD | Low |
| 2026-10-08 | 22:31 | 30-y Bond Auction | USD | Low |
| 2026-10-08 | 23:10 | FOMC Member Musalem Speaks | USD | Low |
| 2026-10-09 | 05:00 | Household Spending y/y | JPY | Low |
| 2026-10-09 | 11:30 | Prelim Machine Tool Orders y/y | JPY | Low |
| 2026-10-09 | 12:30 | SECO Consumer Climate | CHF | Low |
| 2026-10-09 | 13:30 | Italian Industrial Production m/m | EUR | Low |
| 2026-10-09 | 14:45 | ECOFIN Meetings | EUR | Low |
| 2026-10-09 | 18:00 | Employment Change | CAD | High |
| 2026-10-09 | 18:00 | Unemployment Rate | CAD | High |
| 2026-10-09 | 19:30 | Prelim UoM Consumer Sentiment | USD | Medium |
| 2026-10-09 | 19:30 | Prelim UoM Inflation Expectations | USD | Medium |
| 2026-10-10 | 01:30 | FOMC Member Collins Speaks | USD | Low |
Events read: Today's calendar is thin — BOJ Governor Ueda speaks at 12:05 IST (the only high-impact slot) and Ivey PMI at 19:30 is the only medium-tier release; everything else is low-tier. The week's real event risk sits ahead: FOMC minutes Wednesday 23:30 IST, BOE Bailey Thursday, US claims Thursday, Canada jobs and UoM Friday — and, not carried by the ForexFactory feed, the RBI's own rate decision tomorrow, which Polymarket prices as a 25bp hike with ~75% probability and a ~12% tail for 50bp.
4. F&O Positioning — What Smart Money Is Doing
Index futures
| Index | LTP | Chg% | OI | OI Chg% | OI Chg | Signal |
|---|---|---|---|---|---|---|
| NIFTY | 22,620.80 | +0.40% | 1,90,15,620 | −0.73% | -1,40,335 | Short covering |
| NIFTY | 22,722.80 | +0.38% | 23,07,370 | +2.43% | 54,730 | Long buildup |
| NIFTY | 22,845.80 | +0.29% | 2,31,270 | +14.55% | 29,380 | Long buildup |
| BANKNIFTY | 54,923.00 | +0.23% | 23,00,730 | −1.94% | -45,450 | Short covering |
| BANKNIFTY | 55,228.00 | +0.25% | 1,62,960 | +0.28% | 450 | Long buildup |
| BANKNIFTY | 55,558.20 | +0.29% | 20,010 | +25.38% | 4,050 | Long buildup |
| FINNIFTY | 24,741.70 | +0.17% | 27,000 | −1.32% | -360 | Short covering |
| FINNIFTY | 24,880.30 | 0.00% | 240 | 0.00% | 0 | Flat |
| FINNIFTY | 25,015.00 | 0.00% | 0 | — | 0 | Flat |
| MIDCPNIFTY | 13,668.95 | +0.39% | 20,17,200 | −0.91% | -18,600 | Short covering |
| MIDCPNIFTY | 13,722.70 | +0.40% | 78,360 | +1.08% | 840 | Long buildup |
| MIDCPNIFTY | 13,751.00 | +0.23% | 960 | +60.00% | 360 | Long buildup |
| NIFTYNXT50 | 69,543.80 | +0.48% | 16,775 | +0.60% | 100 | Long buildup |
| NIFTYNXT50 | 69,744.40 | +0.52% | 275 | −15.38% | -50 | Short covering |
| NIFTYNXT50 | 70,493.00 | 0.00% | 25 | 0.00% | 0 | Flat |
Futures say Monday's rise was covering, not conviction: NIFTY's 27-Oct contract gained 0.40% while its OI shrank 0.73% (short covering), and BANKNIFTY's front month did the same (-1.94% OI on +0.23% price). The far months built small longs (NIFTY Dec +14.55% OI), but the front-month signal is light positioning into today's expiry rather than fresh upside commitment.
Option Chain Key Levels — nearest expiry 2026-10-06
| Type | Strike | OI (Lakh) | Significance |
|---|---|---|---|
| 🔴 Strong Resistance | 23,000 | 146.6 | Highest Call OI |
| 🔴 Strong Resistance | 22,800 | 143.8 | |
| 🔴 Strong Resistance | 23,500 | 133.6 | |
| 🟢 Strong Support | 21,500 | 147.3 | Highest Put OI |
| 🟢 Strong Support | 22,000 | 127.8 | |
| 🟢 Strong Support | 22,500 | 122.3 |
PCR: 0.9008 · Max pain: 22550 · India VIX: 14.775 · ATM straddle: 22,475.85–22,629.50 (₹153.65 width)
OI change: The expiry chain is put-heavy: net put OI rose +511.3 lakh against +113.5 lakh on calls, PCR 0.90, and max pain sits at 22,550 — essentially spot. The walls are calls at 23,000 (146.6 lakh) and 22,800 (143.8), puts at 21,500 (147.3), 22,000 (127.8) and 22,500 (122.3), so the market is priced to defend 22,500 and cap 22,800 into the close. The ATM straddle (22,475.85–22,629.50) frames the market's expected same-day range at roughly ±77 points around spot.
Sensibull Verified Cohort (#VerifiedBySensibull)
| Index | Signal | Bias % (bull-side) | Cohort PCR | CE-short wall | PE-short wall |
|---|---|---|---|---|---|
| NIFTY | NEUTRAL | 56.6 | 1.6 | 22900 (17550 lots) | 22500 (16640 lots) |
| BANKNIFTY | NEUTRAL | 47.5 | 0.98 | 54400 (1200.0 lots) | 54400 (1200.0 lots) |
| SENSEX | — | — | |||
| FINNIFTY | — | — | |||
| MIDCPNIFTY | — | — |
4B. India VIX — IV Rank & IV Percentile
| Metric | Value |
|---|---|
| India VIX (latest close) | 14.775 |
| 252-session high / low | 27.89 / 9.15 |
| IV Rank (0–100) | 30.0 — Low |
| IV Percentile | 72.6% |
Trailing 252 sessions (2025-09-18 → 2026-10-05) of India VIX EOD closes. IV Rank = (VIX − session low) / (session high − low) × 100; IV Percentile = share of those sessions that closed below the current VIX. Derived deterministically by scripts/vix-iv-rank.mjs; window high/low include the day's own close.
Vol is mid-range, not complacent: India VIX's IV Rank reads low against the trailing-year band while its IV Percentile sits well above the median. The two diverge because one outsized earlier spike anchors the top of the window, so the rank understates how much of the past year traded below today's level — the practical read is that options are not cheap even though the rank looks benign. VIX firming alongside a green index keeps option-seller comfort a warning rather than an all-clear.
5. Yesterday's NIFTY Movers
| Top 5 Pullers | Points | Top 5 Draggers | Points |
|---|---|---|---|
| ICICI Bank | +33.41 | HDFC Bank | -54.74 |
| ITC | +27.26 | Infosys | -11.15 |
| Reliance Industries | +27.23 | HCL Technologies | -9.43 |
| Bharti Airtel | +26.31 | Sun Pharmaceutical Industries | -5.02 |
| Larsen and Toubro | +14.43 | Asian Paints | -4.03 |
Net contribution (top movers): 124.98 pts
Monday's +125-point net index contribution was narrow: ICICI Bank +33.4, ITC +27.3 and Reliance +27.2 lifted the index while HDFC Bank alone dragged -54.7 (its CEO-day pop failed and a class-action headline circulated), with Infosys -11.2 and HCL Tech -9.4. That mix explains the weak breadth behind a green index close.
6. Technical Levels for Today
| Level | Price |
|---|---|
| R3 | 22,877.37 |
| R2 | 22,749.58 |
| R1 | 22,652.67 |
| Pivot | 22,524.88 |
| S1 | 22,427.97 |
| S2 | 22,300.18 |
| S3 | 22,203.26 |
Moving averages
| MA | Level | Spot vs MA |
|---|---|---|
| 5 DMA | 22,618.92 | −0.28% below |
| 10 DMA | 22,948.83 | −1.71% below |
| 20 DMA | 23,203.04 | −2.79% below |
| 50 DMA | 23,843.82 | −5.40% below |
Nifty closed 22,555.75 on Monday with a 224-point range (22,397–22,622), still 2.8% below its 20-DMA and below every monitored average from 5-DMA down — the rebound has not repaired the trend, only the oversold condition. Classic pivots for today: PP 22,525, R1 22,653, R2 22,750; S1 22,428, S2 22,300.
6B. Market Breadth — How Many Stocks Actually Moved
| Metric | Value |
|---|---|
| Advancers | 1692 |
| Decliners | 1915 |
| Net (A − D) | -223 |
| A/D ratio 0.88 | 45.58% advancing · 3,712 traded |
| Net over last 5 sessions | -4777 |
| Net over last 20 sessions | -9396 |
NSE top movers — 2026-10-05
| Top gainers | LTP | Chg% | Top losers | LTP | Chg% |
|---|---|---|---|---|---|
| ORIENTCABL | 405.00 | +48.90% | ACEVECTOR | 26.08 | −18.50% |
| DPWIRES | 196.78 | +20.00% | HIMALAYAN | 84.85 | −17.62% |
| KRISHNADEF | 1,201.00 | +19.99% | V2RETAIL | 169.28 | −15.94% |
| ROXHITECH | 62.45 | +19.98% | |||
⚠️ Prices are unadjusted. ORIENTCABL 48.9% — no corporate action found near 2026-10-05 — large but apparently genuine; verify before featuring
Filtered to liquid NSE equity names (volume ≥ 1,00,000); 9 illiquid or non-equity entries were excluded from the raw all-securities list.
Official NSE breadth for 05-Oct is negative beneath a positive close: 1,692 advancers against 1,915 decliners (A/D 0.88), and the multi-session nets remain deeply negative (-4,777 over 5 sessions, -9,396 over 20). This is a narrow, heavyweight-led tape — participation is not confirming Monday's bounce, so treat the index gain as a repair attempt, not a broad-based turn.
NSE MCP get_market_breadth (2026-10-05) — Exchange data via NSE MCP (mcp.nseindia.in) — informational use only, not endorsed by NSEIL.
7. Key News Headlines — NIFTY, US & India
🇺🇸 US / Global
- Nasdaq notches record high close as investors focus on earnings — Reuters 🟢 Record US close plus an earnings-led tape is the risk-on input behind the GIFT gap.
- Why Small Caps Are Lagging the Nasdaq Record in 2026 — Stock Titan ⚪ Narrow US leadership mirrors India's own narrow tape — a global breadth divergence, not a local one.
- Brazil markets' Bolsonaro rally sends stock exchange to record high — Reuters ⚪ EM risk appetite is alive; marginal positive read-through for flows.
🇮🇳 India
- FIIs net sell Rs 4,699 crore, DIIs net buyers of Rs 5,182 crore on Oct 5 — Moneycontrol 🔴 The FII supply / DII absorption pattern persists for another session — the structural overhang on every rally.
- HDFC Bank: new CEO, Q2 growth update and a class action suit — LatestLY 🔴 The bank is the single biggest index dragger and its headline flow stays mixed — watch whether it keeps bleeding points.
- Sensex, Nifty strong: Orient Green surges 51% on debut; Runwal, Acevector fall — Financial Express ⚪ Primary-market froth in small caps contrasts with the large-cap sell-off — a liquidity tell, not a signal.
NIFTY-specific
- Market snaps four-day losing streak, Nifty above 22,500 — news roundup 🟢 The bounce has a level attached to it — 22,500 is the line Monday left behind.
- Nifty 50 gains as IT and auto shares weigh — Dalal Street Investment Journal 🔴 IT and autos were the laggards into the close; both have ADR/global cross-reads this morning, and neither is helping.
- Nifty outlook and levels for Tuesday 06-Oct — news roundup ⚪ Sell-side levels cluster around the same 22,500-22,600 pivot the option data and the videos identify.
17. Market Charts — @Barchart & @Patterns0001 (X)
Latest chart image posts from the tracked X accounts, captured verbatim. Third-party content, reproduced for information only — all rights remain with the original posters. Not investment advice; no trade setups reproduced.
@Barchart
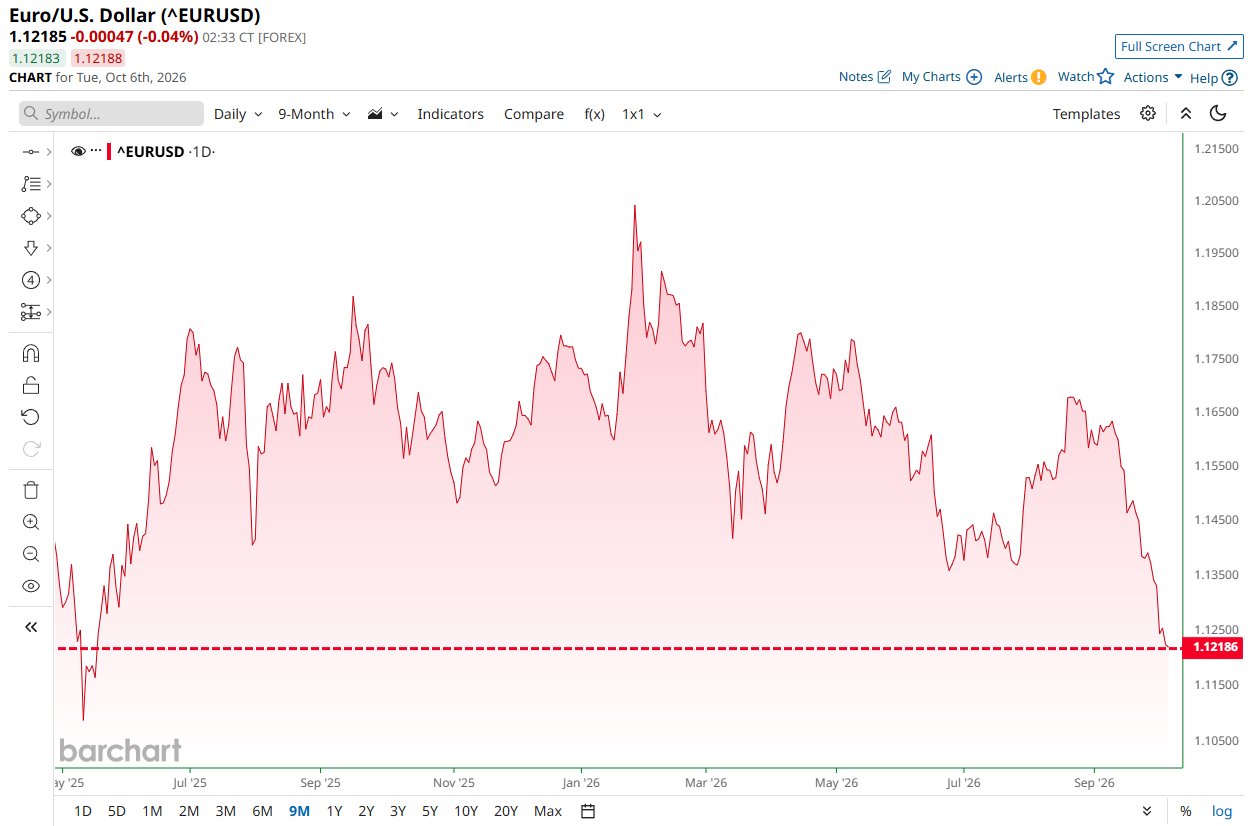
BREAKING 🚨: Europe Euro falls to its weakest level against the U.S. Dollar since May 2025 📉 https://t.co/21f1ObRMq2 — View on X ↗
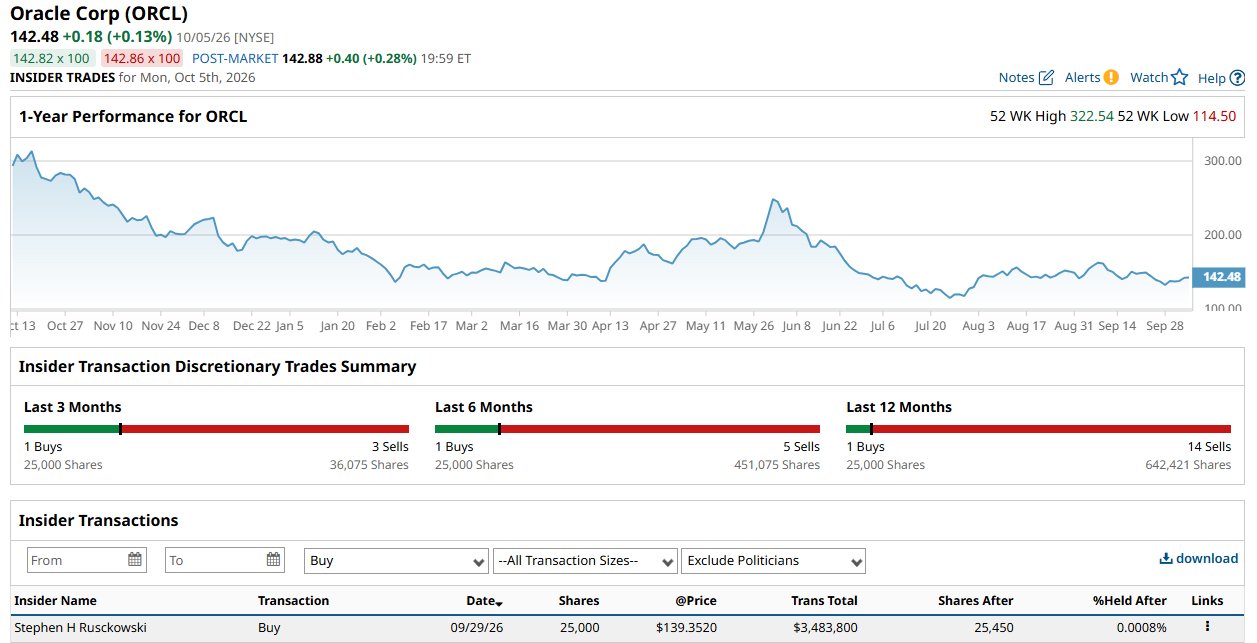
Oracle Insider Trading Alert 🚨 Director Stephen Rusckowski just bought $3.5 million worth of $ORCL shares, the 2nd largest insider buy in the company's history, only behind Founder Larry Ellison's $8.8 million purchase in 1993 👀 https://t.co/esd1TdWYge — View on X ↗
JUST IN 🚨: Michael Burry, the man who has predicted 60 of the last 2 market crashes, says the stock market is currently in denial 👀 https://t.co/Qonuanr6Xa — View on X ↗
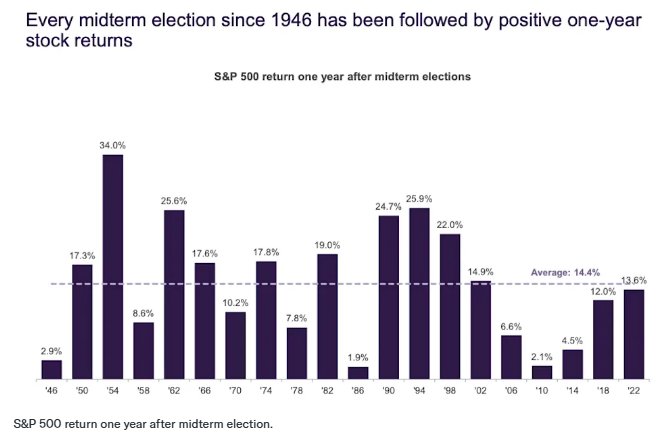
Every midterm election since 1946 has seen positive stock market returns over the next 12 months 📈 The average gain has been 14.4%, the largest gain was 34% (1954's midterm election) 🤑 🥳 https://t.co/85SLzP1nts — View on X ↗
@Patterns0001
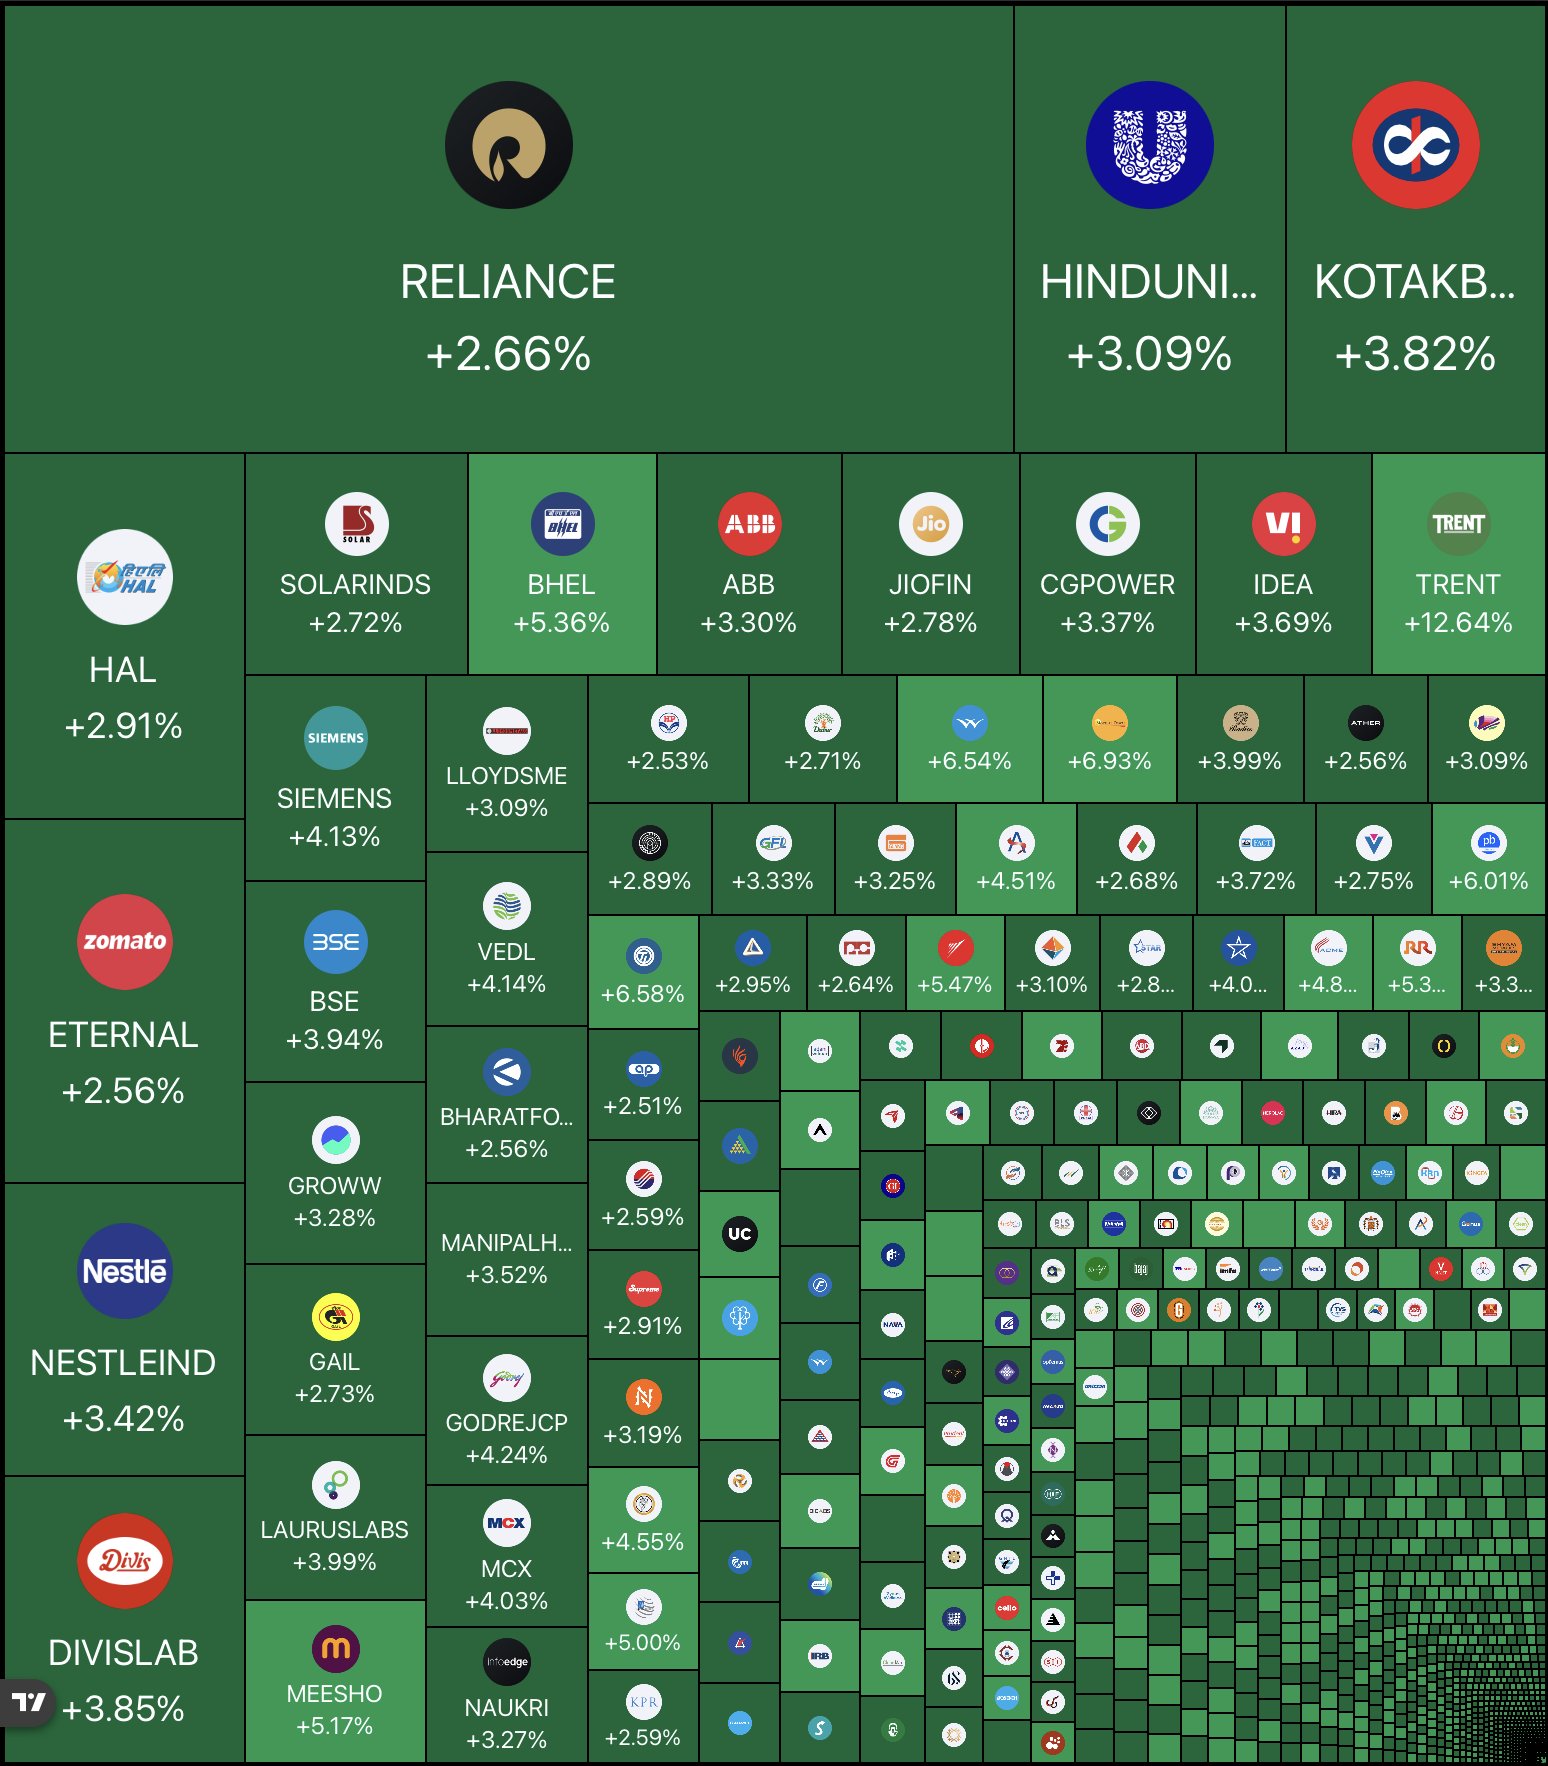
JUST IN: ₹4.7 lakh crore added to the Indian stock market Today Largest addition in more than 2 months https://t.co/AijcdLv5lL — View on X ↗
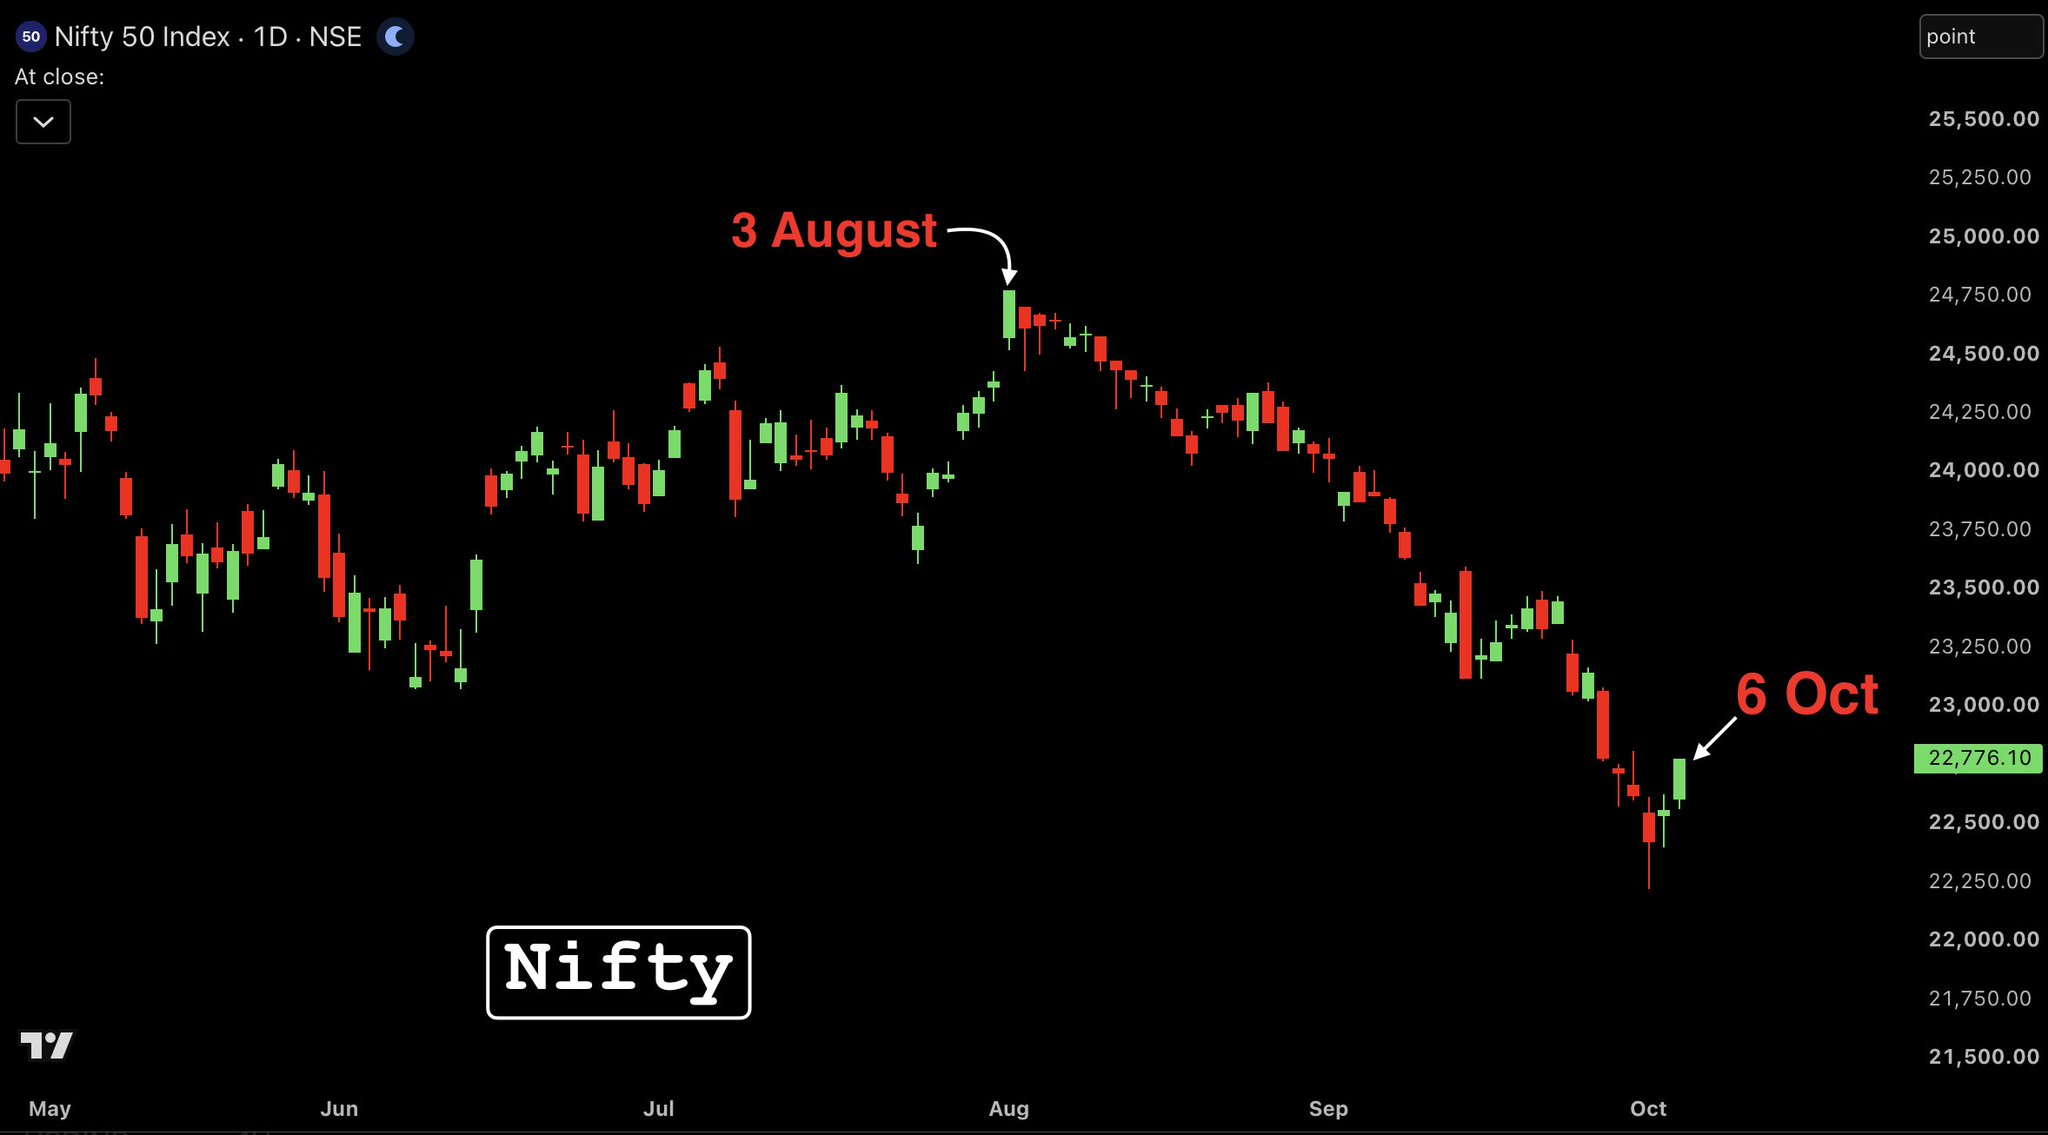
JUST IN: Nifty just had its Highest single-day gain in 2 months https://t.co/saW2w0GQq0 — View on X ↗
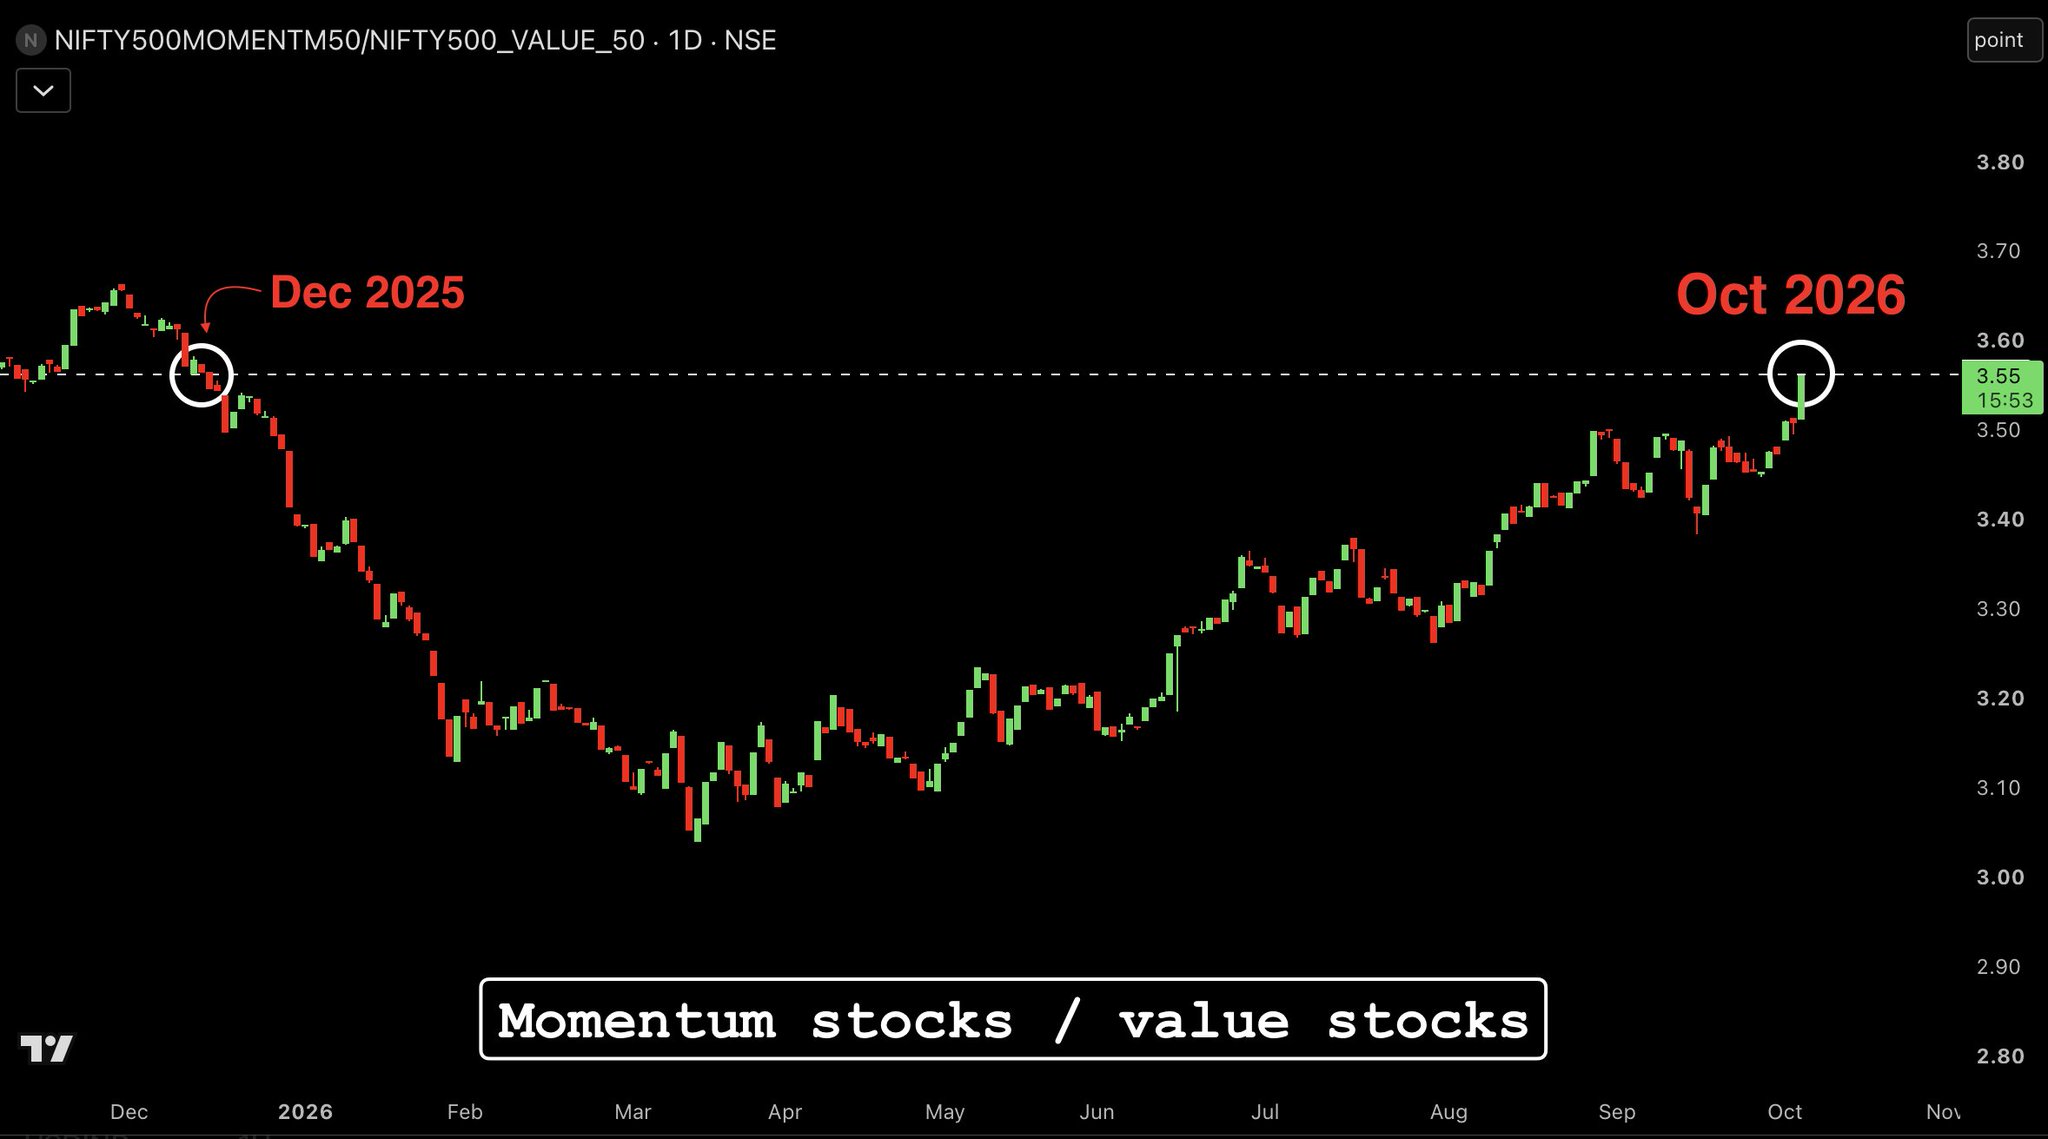
Momentum stocks are now Outperforming value stocks by the most in 10 months https://t.co/BU72r5cPpK — View on X ↗
8. PR SUNDAR'S VIEW
| Item | View |
|---|---|
| Bias | Cautious, bounce-conditional — and five sessions old. On his 01-Oct post-market report he framed the recovery as valid only while Nifty holds 22,500, with the downside 'really very very scary' if the prior week's low gives way. He called the FII exit unprecedented — about Rs 40,000 cr sold in five sessions (~Rs 8,000 cr/day), worse than the COVID or Lehman periods — with DIIs absorbing. |
| Key levels | 22,500 = the line that keeps the bounce alive (recovery toward 23,000 above it); the prior week's low (his spoken '2200' — the 22,000-22,200 zone) as the downside break level. He flagged the volatility index rising on an up day as the biggest concern, HDFC Bank ~30% off its 52-week high, Reliance >25% off, and IT weak despite Accenture's surge. |
| Rationale | He read 01-Oct as a volatile recovery from a six-month low led by domestic institutions while FIIs kept selling; banks were rescued by ICICI Bank after HDFC Bank gave back its CEO-day gains; IT faded despite Accenture; the VIX rising alongside the index was, in his words, 'a very very big concern'. |
| Cross-check with data | The user-supplied link resolved to this 01-Oct video — no 06-Oct pre-market upload existed at run time — so it is labelled with its publish date and not used as today's primary input. Its framework still maps onto today's tape: his 22,500 line sits exactly where the put wall (122.3 lakh) and max pain (22,550) sit, and his 'prior week low' downside case aligns with the 22,200 area above the 22,000 put wall. His VIX point has since cooled only slightly — India VIX 14.775 (+2.2%) is still rising with the index. |
8B. Be Sensibull Analysis View
| Item | View |
|---|---|
| Bias | Neutral inside a defined box with the verdict deferred to the 200-WMA. This IS the 06-Oct analysis stream (recorded Monday evening): he treats the bounce as credible only on a decisive close above 22,600 (~22,625 exact), calls upside 'limited / fizzling out' and the downside potentially 'violent, panicky and big'. He notes social-media sentiment turning against the government has historically preceded at least a relief rally. |
| Key levels | 22,300 = 'solid support'; 22,400 = support mostly built on Monday, so flagged as at risk of not holding; 22,600 = the pivot that decides the next leg; call towers at 22,800 and 23,000. His FII dashboard read: bought in futures but sold ~Rs 4,700 cr in cash on Monday; 'FII and pro bullish, client bearish' on the OI change. |
| OI / PCR / IV commentary | PCR ~0.9 on his screen (both around ATM and overall) which he explicitly discounts on expiry day as distorted by last-minute put selling; no IV print quoted. |
| Cross-check with data | His three anchors land on the independent data: the 22.600 pivot sits above the computed PP (22,525) and below R1 (22,653) — i.e. the middle of today's decision zone; his 22,400/22,300 supports stack exactly over the put walls (22,500's 122.3 lakh and 22,000's 127.8) and under max pain 22,550; his call towers match the top two public call strikes (23,000 and 22,800) and the cohort's short-CE wall (22,900, 17,550 lots). His 0.9 PCR and the independently computed 0.9008 agree. |
8C. Crowd Sentiment — 4chan & Reddit (US + India)
| Venue | Tone |
|---|---|
| 4chan /biz/ + /wsg/ | Biz/wsg is active in a market-thread way (/smg/ threads ~370 replies each) — tone is posturing and degen-humour, no panic. Contrarian: No capitulation signal; the boards are not treating Monday's bounce as a trap. |
| Reddit US (WSB · stocks · investing) | WallStreetBets is in its normal overnight wait state ('What Are Your Moves Tomorrow, October 6'), with an 'AI haters waiting for an AI bubble to pop' thread as the flavour of the day. Themes: earnings week positioning · AI bubble debate · small-cap lag |
| Reddit India (r/IndianStockMarket · r/IndiaInvestments) | India subs returned no readable RSS entries this run (fetch empty) — no domestic retail read to report. |
Verdict: Crowd is cautious and hedged, not euphoric — mildly contrarian-positive, but the read is thin without the India subs. — The absence of capitulation (4chan) alongside a slightly bearish Indian retail tone suggests the bounce is being met with skepticism rather than chase — consistent with the narrow breadth and FII supply.
9. Nifty Buddy's View (X/Twitter)
| Item | View |
|---|---|
| Bias | Not collected this run — x.com/niftybuddy remains HTTP 403 to this box and no equivalent read was sourced inside the time-box. |
| Weekly/monthly levels | — |
| Commentary | — |
| Cross-check with data | The section is marked unavailable in the footer; treat the OI, cohort and video reads as the expert layer today. |
10. Polymarket Prediction Market Signals
| Event | Probabilities | Trend | Vol 24h | Ends |
|---|---|---|---|---|
| 🏆 Largest company / NVIDIA | ||||
| 🗳️ US politics | ||||
| 🛢️ Oil | ||||
| 🌍 Geopolitics | ||||
| 🔵 Fed policy | ||||
| Fed Decision in October? | Fed decrease interest rates by 50+ bps after the October 2: 0.15% · Fed decrease interest rates by 25 bps after the October 20: 0.35% · there be no change in Fed interest rates after the October: 80.5% · Fed increase interest rates by 25 bps after the October 20: 19.5% · Fed increase interest rates by 50+ bps after the October 2: 0.35% | there be no change in Fed interest rates after the October ↓, Fed increase interest rates by 25 bps after the October 20 ↑ | $15,28,176 | 2026-10-29 |
| Fed Decision in December? | Fed decrease interest rates by 50+ bps after the December : 0.35% · Fed decrease interest rates by 25 bps after the December 2: 1.15% · there be no change in Fed interest rates after the Decembe: 22.5% · Fed increase interest rates by 25 bps after the December 2: 74.5% · Fed increase interest rates by 50+ bps after the December : 2.95% | Fed decrease interest rates by 50+ bps after the December ↓, there be no change in Fed interest rates after the Decembe ↓, Fed increase interest rates by 25 bps after the December 2 ↑ | $51,093 | 2026-12-10 |
| Another Fed rate hike in 2026? | Another Fed rate hike in 2026: 77.5% | Another Fed rate hike in 2026 ↑ | $23,880 | 2026-12-10 |
| US announces end of Iranian blockade by...? | US announces end of Iranian blockade by July 24, 2026: 0% · US announces end of Iranian blockade by July 31, 2026: 0% · US announces end of Iranian blockade by August 15, 2026: 0% · US announces end of Iranian blockade by August 31, 2026: 0% · US announces end of Iranian blockade by July 14, 2026: 0% · US announces end of Iranian blockade by December 31, 2026: 51.4% | US announces end of Iranian blockade by July 24, 2026 ↓, US announces end of Iranian blockade by July 31, 2026 ↓, US announces end of Iranian blockade by July 14, 2026 ↓, US announces end of Iranian blockade by December 31, 2026 ↓ | $4,87,461 | 2027-01-01 |
| Will the U.S. invade Iran before 2027? | U.S. invade Iran before 2027: 14.5% | flat | $4,49,120 | 2027-01-01 |
| Prime Minister of Israel after the next election? | Benjamin Netanyahu be the next Prime Minister of Israel: 35.5% · Naftali Bennett be the next Prime Minister of Israel: 10.5% · Yair Lapid be the next Prime Minister of Israel: 0.15% · Gadi Eizenkot be the next Prime Minister of Israel: 46.75% · Benny Gantz be the next Prime Minister of Israel: 0.1% · Avigdor Lieberman be the next Prime Minister of Israel: 1.85% | Naftali Bennett be the next Prime Minister of Israel ↓, Yair Lapid be the next Prime Minister of Israel ↓ | $3,37,254 | 2026-10-28 |
| What will WTI Crude Oil (WTI) hit in October 2026? | WTI Crude Oil (WTI) hit (HIGH) $150 in October: 0.45% · WTI Crude Oil (WTI) hit (HIGH) $140 in October: 0.7% · WTI Crude Oil (WTI) hit (HIGH) $130 in October: 1.15% · WTI Crude Oil (WTI) hit (HIGH) $120 in October: 2.4% · WTI Crude Oil (WTI) hit (HIGH) $110 in October: 8% · WTI Crude Oil (WTI) hit (HIGH) $100 in October: 28% | WTI Crude Oil (WTI) hit (HIGH) $110 in October ↓, WTI Crude Oil (WTI) hit (HIGH) $100 in October ↓ | $1,99,566 | 2026-11-01 |
| Saudi Oil Pipeline (East-West) restarts by...? | Saudi Oil Pipeline (East-West) restarts by September 15: 0% · Saudi Oil Pipeline (East-West) restarts by September 30: 0% · Saudi Oil Pipeline (East-West) restarts by September 22: 0% · Saudi Oil Pipeline (East-West) restarts by October 31: 49.25% · Saudi Oil Pipeline (East-West) restarts by October 15: 29.5% · Saudi Oil Pipeline (East-West) restarts by November 15: 63% | Saudi Oil Pipeline (East-West) restarts by September 15 ↓, Saudi Oil Pipeline (East-West) restarts by September 30 ↓, Saudi Oil Pipeline (East-West) restarts by September 22 ↓, Saudi Oil Pipeline (East-West) restarts by October 31 ↓, Saudi Oil Pipeline (East-West) restarts by October 15 ↓, Saudi Oil Pipeline (East-West) restarts by November 15 ↓ | $1,16,613 | 2026-11-01 |
| Crude Oil all time high by...? | Crude Oil reach a new all-time high by May 31: 0% · Crude Oil reach a new all-time high by June 30: 0% · Crude Oil reach a new all-time high by September 30: 0% · Crude Oil reach a new all-time high by December 31: 9.5% | Crude Oil reach a new all-time high by June 30 ↓, Crude Oil reach a new all-time high by September 30 ↓ | $49,907 | 2027-01-01 |
| Balance of Power: 2026 Midterms | 2026 Balance of Power: D Senate, D House: 65.5% · 2026 Balance of Power: D Senate, R House: 1.1% · 2026 Balance of Power: R Senate, D House: 26.5% · 2026 Balance of Power: R Senate, R House: 7.5% · 2026 Balance of Power: Other: 0.15% | 2026 Balance of Power: R Senate, R House ↓, 2026 Balance of Power: Other ↓ | $5,94,996 | 2026-11-04 |
| Texas Senate Election Winner | Democrats win the Texas Senate race in 2026: 64.5% · Republicans win the Texas Senate race in 2026: 35.5% | Republicans win the Texas Senate race in 2026 ↓ | $1,41,234 | 2026-11-04 |
| Which party will win the House in 2026? | Democratic Party control the House after the 2026 Midterm : 92.5% · Republican Party control the House after the 2026 Midterm : 7.5% | Democratic Party control the House after the 2026 Midterm ↓, Republican Party control the House after the 2026 Midterm ↓ | $1,06,564 | 2026-11-04 |
| Largest Company end of October 2026? | Alphabet be the largest company in the world by market cap: 0.35% · Tesla be the largest company in the world by market cap on: 0.05% · Saudi Aramco be the largest company in the world by market: 0.05% · Broadcom be the largest company in the world by market cap: 0.05% · NVIDIA be the largest company in the world by market cap o: 96.25% · Microsoft be the largest company in the world by market ca: 0.05% | Tesla be the largest company in the world by market cap on ↓, Saudi Aramco be the largest company in the world by market ↓, Broadcom be the largest company in the world by market cap ↓, Microsoft be the largest company in the world by market ca ↓ | $25,633 | 2026-11-01 |
| Largest Company end of December 2026? | NVIDIA be the largest company in the world by market cap o: 85% · Microsoft be the largest company in the world by market ca: 0.6% · Apple be the largest company in the world by market cap on: 10.05% · Alphabet be the largest company in the world by market cap: 4.5% · Tesla be the largest company in the world by market cap on: 0.15% · Saudi Aramco be the largest company in the world by market: 0.15% | Microsoft be the largest company in the world by market ca ↓, Alphabet be the largest company in the world by market cap ↓, Tesla be the largest company in the world by market cap on ↓, Saudi Aramco be the largest company in the world by market ↓ | $7,007 | 2027-01-01 |
Fed: The Fed market keeps a hawkish skew: October holds at 80.5% with a 25bp hike at 19.5%; December prices a 25bp hike at 74.5%; 'another hike in 2026' is 77.5%. Cuts are effectively priced out — no dovish pivot support for EM flows.
Geopolitics: —
US politics: Midterms lean Democratic: D-House 92.5%, D-Senate 65.5% — a divided-government outcome that historically reduces US policy volatility; the USD-INR and India tariffs carry no fresh Polymarket event this morning.
Overall signal: NEUTRAL
Fed: hold in October but a hike priced for December — hawkish tail continues.
RBI: the October decision (tomorrow) prices a 25bp hike at 75%, with an ~12% tail for 50bp — a live domestic event risk.
Oil: 28% chance WTI touches $100 in October — the crude premium has not been fully priced out.
NVIDIA dominance: 96.25% to be the largest company end-Oct, 85.0% end-Dec (flat day, +9.5pp week) — no bubble-deflation trigger from this market.
11. Trump Posts & Comments — Real-Time Policy Signal 🟢 LOW
| Time (IST) | Platform | Topic | Content | Impact |
|---|---|---|---|---|
| 03:55 | Truth Social | Political advertising | Says he will now pay for 'Patriotic Ads' himself and with MAGA-raised money rather than government funds. | ⚪ |
| 03:30 | Truth Social | 2026 Midterms | Promises every adult US citizen USD 5,000 if Republicans win the House and Senate. | 📉 |
| 02:53 | Truth Social | South Carolina Senate race | Endorses Darline Graham against 'Annie Andrews' in the South Carolina Senate primary. | ⚪ |
| 23:28 | Truth Social | Ohio rally | Disputes New York Times reporting on crowd size at his Ohio rally. | ⚪ |
Tone: Campaign/domestic-political · Theme: Midterm politics and media disputes; one conditional populist fiscal promise · Alert: LOW
Quiet on the market-relevant axes; the overnight window was dominated by domestic politics. Cross-ref: No tariff, India, Fed or market-structure post in the overnight window — nothing here moves NIFTY today. The USD 5,000-per-adult promise is fiscally expansionary if taken seriously, but it is conditional and unlegislated; treat it as a US-elections sidebar, not a macro input.
12. 🤖 AI Bubble & Systemic Risk Dashboard
Composite: ELEVATED — 3/7 flags (classic: 3/11, AI: 3/7)
Classic bubble & recession indicators
| # | Indicator | Value | Flag |
|---|---|---|---|
| 1 | 10Y-2Y spread | 0.47 pp | 🟢 |
| 2 | 10Y-3M spread | 1.09 pp | 🟢 |
| 3 | NY Fed recession prob | 13.88% | 🟢 |
| 4 | Sahm Rule | 0.00 | 🟢 |
| 5 | HY OAS | 310 bps | 🟢 |
| 6 | IG OAS | 85 bps | 🟢 |
| 7 | VIX term structure | contango | 🟢 |
| 8 | Shiller CAPE | 41.67 | 🔴 FLAG |
| 9 | Buffett indicator | 244% | 🔴 FLAG |
| 10 | Margin debt YoY | +37.2% | 🔴 FLAG |
| 11 | TED spread | discontinued | 🟢 |
AI-specific indicators
| # | Indicator | Value | Flag |
|---|---|---|---|
| 1 | NVIDIA P/E >60 with decelerating growth | P/E not re-read this run (stockanalysis.com Cloudflare-blocked); NVDA closed 05-Oct at $238.90, +2.12% on the day, a fresh 52-week-high zone. Carried valuation context: 29.58 TTM / 19.41 forward as of 02-Oct. | 🟢 |
| 2 | NVDA below 50/200-DMA | $238.90 (05-Oct close, +2.12%): +9.13% above the 50-DMA $218.92 and +18.84% above the 200-DMA $201.02 (Yahoo 1y daily closes + the 05-Oct close appended). | 🟢 |
| 3 | AI-driven job cuts inside tech vendors | Oracle 21,000 roles cut (13% of workforce) with AI explicitly named, India centres in focus; BMW cutting ~20% of management roles with AI as the stated driver (Times of India, 02-Oct). | 🔴 FLAG |
| 4 | Hyperscaler capex cuts | No new capex cut in the 02-06 Oct news window; Microsoft's calendar-2026 guidance carried at ~USD 175bn (from ~USD 190bn) on FX, unchanged build. | 🟢 |
| 5 | Polymarket NVIDIA dominance | Largest Company end of Dec-2026: NVIDIA 85.0% (oneDayPriceChange negative, oneWeekPriceChange positive — see 13-keys). | 🟢 |
| 6 | Shiller CAPE > 35 | 41.67 (multpl.com, 06-Oct read) - up from 41.38 on 02-Oct. | 🔴 FLAG |
| 7 | Buffett indicator > 150% | 244% of GDP as of 30-Jun-2026, 81.22% above the long-run trend line ('strongly overvalued'). | 🔴 FLAG |
Hyperscaler AI capex
| Company | Capex | Capex/Rev | YoY | Guidance |
|---|---|---|---|---|
| Microsoft | USD 175bn calendar-2026 guidance (from ~USD 190bn) - FX-driven revision, build unchanged | H2 step-up ~+25%/qtr vs Q2 USD 41bn | carried from the 05-Oct read (no refresh event) |
NVIDIA tell: NVDA closed 05-Oct at USD 238.9 (+2.12%), ~18.84% above its 200-DMA - the price tell stays UNFIRED; the AI-deflation evidence in this window is labour-market (Oracle/BMW), not price.
Cross-asset divergence signals
| Signal | Observation | Danger? | Notes |
|---|---|---|---|
| AI capex vs AI hiring | Capex guidance is intact while AI-attributed job cuts keep printing (Oracle 21,000, BMW management -20%). | MEDIUM | cost-side deflation shows up in employment before it shows up in hyperscaler capex. |
AI narrative health check
| Dimension | Status | Evidence |
|---|---|---|
| AI-internals | intact | NVDA above both DMAs; Polymarket dominance 85%; no capex cut. |
| AI-labour | deteriorating | Oracle 21,000; BMW ~20% of management; Indian IT commentary. |
Michael Burry / Cassandra signal: CRITICAL — carried: the 30-day lookback from Burry's Substack (Cassandra Unchained) was not re-crawled this run; the last read (05-Oct) was CRITICAL.
The classic flags remain 3 (ELEVATED): Shiller CAPE 41.67 (up from 41.38), Buffett 244% of GDP, margin debt +37.2% y/y — no new classic flag and none cleared. The new evidence is labour-side, not price-side: Oracle's 21,000-role cut with AI named as the driver and BMW's ~20% management cut keep the 'AI deflates employment first' thread alive. Credit spreads (HY 310bps / IG 85bps) and the VIX term structure (contango) still refuse to confirm any bubble-adjacent stress.
Narrative: The story has not shifted at the index level — AI internals stay intact (NVDA above both DMAs, no hyperscaler capex cut, NVIDIA dominance priced high) — but the employment undercurrent hardened again this week. That is the slow-burn divergence to track: capex intact while AI-attributed cuts print.
13. Domestic Mutual Fund Flows — DII Liquidity Backdrop DATA MONTH: 2026-08 ♻️ as of 2026-10-05
| Category | Net Flow (₹ Cr) | MoM |
|---|---|---|
| Equity (open-ended schemes) | ₹29,329 | 18.75 |
| Debt (open-ended schemes) | ₹-8,127 | -104.33 |
| Hybrid (open-ended schemes) | ₹10,045 | -12.58 |
| Index Funds (total) | ₹787 | -48.75 |
| ETFs (total) | ₹10,161 | — |
| Solution Oriented Schemes | ₹335 | — |
| Life Cycle Funds | ₹8 | — |
| Close-ended Schemes | ₹-1,112 | -60.6 |
| Interval Schemes | ₹-0 | — |
| Industry Grand Total (net inflow) | ₹41,354 | -82.47 |
| Small Cap Fund | ₹7,973 | 2.65 |
| Mid Cap Fund | ₹6,989 | 12.87 |
| Flexi Cap Fund | ₹5,059 | 7.44 |
| Large & Mid Cap Fund | ₹3,873 | 13.06 |
| Multi Cap Fund | ₹3,733 | 15.66 |
| Thematic Fund | ₹1,766 | — |
| Contra Fund | ₹1,328 | — |
| Focused Fund | ₹995 | 54.9 |
| Value Fund | ₹24 | — |
| Sectoral Fund | ₹-53 | — |
| Dividend Yield Fund | ₹-134 | 21.04 |
| Large Cap Fund | ₹-1,147 | — |
| ELSS | ₹-1,078 | -12.43 |
| Liquid Fund | ₹19,934 | -83.26 |
| Overnight Fund | ₹-30,654 | -175.85 |
| Money Market Fund | ₹11,735 | -44.59 |
| Ultra Short Term Fund | ₹4,257 | -47.05 |
| Floating Interest Rates Fund | ₹182 | 145.99 |
| Credit Risk Fund | ₹-23 | -115.97 |
| Banking & PSU Debt Fund | ₹-1,288 | -184.64 |
| Gilt Fund | ₹-1,824 | -786.37 |
| Corporate Bond Fund | ₹-3,190 | -306.55 |
| Arbitrage Fund | ₹3,789 | -41.73 |
| Multi Asset Allocation Fund | ₹3,671 | -2.2 |
| Balanced Hybrid Fund | ₹1,836 | — |
| Aggressive Hybrid Fund | ₹1,323 | — |
| Balanced Advantage Fund / Dynamic Asset Allocation | ₹-228 | 9.65 |
| Equity Savings Fund | ₹-246 | 48.44 |
| Conservative Hybrid Fund | ₹-99 | -347.15 |
| Equity ETFs | ₹7,237 | — |
| Gold ETFs | ₹2,597 | 66.59 |
| Silver ETFs | ₹1,271 | — |
| Debt ETFs | ₹-945 | — |
| Index Funds - Equity | ₹2,393 | — |
| Index Funds - Debt | ₹-1,610 | — |
| Fund of Funds investing overseas | ₹-72 | 20.13 |
| SIF (Specialised Investment Funds) | ₹7,699 | — |
SIP inflows: ₹32,297 Cr · ♻️ as of 2026-10-05
Trend: Reused 05-Oct collection (August 2026 AMFI vintage, the latest published): equity-category inflows stayed positive with a healthy MoM step-up and SIP contributions steady at a significant monthly run-rate — no fresh vintage exists since the last run, so this is carried, not stale news.
FII/DII absorption: The domestic bid (SIPs + category inflows) remains the structural counterweight to FII cash selling; nothing in today's tape changes the August picture.
NIFTY impact: DII absorption is what lets the index hold rebounds like Monday's; keep watching it as the FII overhang persists.
14. MCX Crude Oil Options — India-Denominated Crude Signal nearest expiry 2026-10-15
| Metric | Value |
|---|---|
| MCX Crudeoil futures | 8684 |
| ATM strike | — · IV — |
| Highest Call OI (crude resistance) | 9,000 |
| Highest Put OI (crude support) | 8,500 |
| PCR | 0.8453 |
| Max pain | — |
OI buildup: MCX CRUDEOIL is at 8,684/bbl (-232, -2.60% on the session); the page's OI summary flags heavier call OI at 9,000 (immediate resistance) and put support at 8,500, with an expected range of roughly 8,096–9,272 into the 15-Oct contract.
IV read: No reliable IV print was parsed this run (the per-strike grid could not be scraped), so the IV leg is marked unavailable rather than estimated.
Cross-checks: The domestic -2.60% move lines up with Brent ~$100.5 (-1.7%) and WTI ~$89.4 (-1.8%) overnight; a falling crude complex is a modest tailwind for India's macro inputs even though the level stays high.
NIFTY impact: Crude easing takes some pressure off the import bill and inflation expectations ahead of tomorrow's RBI decision — a supporting input for the range-bound call, not a directional one.
15. 🏛️ Policy Watch — Government & Regulatory Changes by Sector 🟢 no material change
No material change — a quiet policy day.
✅ No new policy notifications in the last 72h across the watched sources.
Carried from earlier runs — still pending
| Policy / notification | Sector | Status | Age | Severity | Issuer |
|---|---|---|---|---|---|
| SEBI pre-open market session (9:00-9:15) revised — Gold and Silver ETFs admitted to the pre-open session, phase timings and ETF base prices/price bands reworked | Financial Services | ⚡ In force | 39d old | 🟡 MED | SEBI |
| Corporate Laws (Amendment) Bill, 2026 pending before Parliament | Financial Services | 📝 Proposed | 26d old | 🟢 LOW | Corporate Affairs (MCA) |
| Taxation and Other Laws (Amendment) Bill, 2026 passed by Parliament | All sectors | ⚡ In force | 22d old | 🟡 MED | Finance |
| CBIC revises central excise duties on exported petroleum via Notifications 49, 50, 51/2026-Central Excise — export petrol special additional duty cut to Rs 0.50/litre, HSD to Rs 20/litre, ATF to Rs 15/litre, road cess on exported HSD to nil | Oil & Gas | ⚡ In force | 21d old | 🟡 MED | Finance (CBIC) |
| Anti-dumping duty on calcined gypsum powder from Iran, Oman, Saudi Arabia and UAE extended to 16 March 2027 | Cement | ⚡ In force | 21d old | 🟢 LOW | Finance (CBIC) |
| DGFT Notification 36/2026-27 exempts export consignments up to Rs 3 lakh FOB from RCMC / Certificate of Registration, effective immediately | Exports | ⚡ In force | 21d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Trade Notice 27/2026-27 proposes comprehensive Non-Preferential Rules of Origin for imports and exports; comments open 15 days | Exports | 📝 Proposed | 21d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Trade Notice 28/2026-27 cuts Pre-Shipment Inspection Certificate issuance to a two-day window from inspection | Exports | ⚡ In force | 21d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT extends deadline to surrender unutilised raw sugar TRQ allocation (10 lakh tonnes) to 30 September 2026 | Sugar | ⚡ In force | 21d old | 🟢 LOW | Commerce & Industry (DGFT) |
| SEBI consultation paper on BCP and disaster recovery for market infrastructure institutions — shorter non-working-day DR drills, tighter primary-data-centre norms | Financial Services | 📝 Proposed | 21d old | 🟢 LOW | SEBI |
| CBIC Notification 75/2026-Customs (N.T.) revises tariff values for palm oils, gold, silver, brass scrap and areca nuts effective 16 Sep 2026 | Metals | ⚡ In force | 20d old | 🟢 LOW | Finance (CBIC) |
| SEBI extends the Samuhik Prativedan Manch common reporting platform to clearing members who are also stock brokers — 14 compliance reports from 30 Sep 2026, phase 2 on 31 Dec 2026 | Financial Services | ⚡ In force | 19d old | 🟢 LOW | SEBI |
| Draft National Electricity Policy 2026 sent to Cabinet — annual tariff resets, discom financial turnaround, end to discom monopolies, renewable integration and storage | Power | 📝 Proposed | 18d old | 🟡 MED | Power & Energy |
| US presidential proclamation of 18-Sep-2026 extends the USD 100,000 payment requirement for certain new H-1B petitions to 21-Sep-2027 (India-born professionals were 71% of approved H-1B beneficiaries); court challenges continue | IT | ⚡ In force | 18d old | 🟡 MED | United States (Presidential Proclamation) |
| SEBI 215th Board approves new Portfolio Managers Regulations 2026 (replaces 2020 regime; PRIM + Independent Fund Manager) | Financial Services | 📌 Notified | 12d old | 🟡 MED | SEBI |
| SEBI 215th Board approves Settlement Regulations 2026 — formula-based settlement amount, pre-SCN settlement notice, fast-track under Rs 10 lakh | Financial Services | 📌 Notified | 12d old | 🟡 MED | SEBI |
| SEBI permits FPIs to trade non-agricultural index and non-cash-settled commodity derivatives, with mandatory exit before tender period (T-3) | Financial Services | 📌 Notified | 12d old | 🟡 MED | SEBI |
| SEBI enables Depository Receipts on REIT/InvIT units, initially via the IFSC, to attract foreign capital | Realty | 📌 Notified | 12d old | 🟢 LOW | SEBI |
| SEBI raises Vault Manager minimum net worth from Rs 50 crore to Rs 75 crore and widens scope beyond Electronic Gold Receipts | Financial Services | 📌 Notified | 12d old | 🟢 LOW | SEBI |
| DGFT Notification 41/2026-27 continues the RoDTEP scheme to 31-December-2026 for DTA units, Advance Authorisation holders, SEZ units and EOUs; Appendix 4R/4RE rates and value caps as applicable on 30-Sep-2026 continue unchanged | Exports | ⚡ In force | 6d old | 🟡 MED | Commerce & Industry (DGFT) |
| CBIC Notifications 52 & 53/2026-Central Excise cut the special additional excise duty on exported diesel from Rs 20 to Rs 16/litre and set ATF at Rs 10.50/litre and petrol at Rs 0.50/litre with effect from 1 October 2026 (domestic fuel duties unchanged) | Oil & Gas | ⚡ In force | 6d old | 🟡 MED | Finance (CBIC) |
| CBIC Notification 80/2026-Customs (N.T.) dated 30-Sep-2026 substitutes Tables 1-3 of Notification 36/2001-Customs (N.T.) from 1 October 2026: crude palm oil USD 1,229/MT, RBD palm oil 1,240, palmolein 1,248-1,251, crude soya bean oil 1,280, brass scrap 8,149/MT; gold USD 1,339 per 10 g and silver USD 1,965/kg; areca nuts unchanged at USD 11,574/MT | Metals | ⚡ In force | 6d old | 🟢 LOW | Finance (CBIC) |
| DGFT Notifications 39 & 40/2026-27 extend the Minimum Import Price condition on specified Chapter 29 chemical products (USD 111/kg CIF) and on Sulfadiazine API (Rs 1,774/kg CIF) to 30-November-2026 | Pharma | ⚡ In force | 6d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Notification 38/2026-27 extends the Minimum Import Price of Rs 67,220 per metric tonne (CIF) on specified Virgin Multi-layer Paper Board (ITC-HS 48059100, 48059200, 48059300, 48109200, 48109900) to 31-March-2027 | Paper & Packaging | ⚡ In force | 6d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Notification 37/2026-27 extends Component II timelines of the Resilience & Logistics Intervention for Export Facilitation (RELIEF) under the Export Promotion Mission to 31-March-2027, citing the continuing West Asia crisis | Exports | ⚡ In force | 6d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Trade Notice 29/2026-27 dated 1-Oct-2026 reconstitutes the Sub-Committee on Trade Finance under the Niryat Protsahan sub-scheme (MSME, DFS, DGFT, CGTMSE, EXIM Bank, NCGTC; invitees ECGC, IBA, IFSCA, factoring NBFCs) | Exports | ⚡ In force | 5d old | 🟢 LOW | Commerce & Industry (DGFT) |
| SEBI circular dated 1-Oct-2026 requires stock brokers to display investor awareness message(s) on their trading apps and websites under Project Jagrook | Financial Services | ⚡ In force | 5d old | 🟢 LOW | SEBI |
| RBI Master Direction on Note Sorting Machines dated 2-Oct-2026 (RBI/DCM/2026-27/473; DCM(NPD) No.S2154/18.00.014/2026-27): authentication and fitness-sorting standards consolidated, BIS-certified NSMs mandatory for future procurement, discontinued models phased out by 30-Jun-2027, quarterly calibration and testing; withdraws the 2009/2010/2022/2024/2025 circulars | Financial Services | ⚡ In force | 4d old | 🟢 LOW | Reserve Bank of India |
| President of India hosts President of the Swiss Confederation | Diplomacy | 📌 Notified | 1d old | 🟢 LOW | Rashtrapati Bhavan / MEA |
| CAQM deploys flying squads to curb paddy stubble burning | Environment / Agri | 📌 Notified | 1d old | 🟢 LOW | Environment (CAQM) |
| India and Japan launch Operational Manual for the Joint Crediting Mechanism | Climate / Energy | 📌 Notified | 1d old | 🟢 LOW | Environment / MEA |
| RBI to conduct Overnight VRRR auction under LAF on 06-Oct-2026 | Banks / Rates | ⚡ In force | 1d old | 🟢 LOW | RBI |
| Auction of Government of India Dated Securities | Rates / Fiscal | 📌 Notified | 1d old | 🟢 LOW | RBI |
| Directions under s.35A BR Act against six co-operative banks | Banks | 📌 Notified | 1d old | 🟢 LOW | RBI |
| RBI Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 in force from 1-Oct-2026: single export+import framework, mandatory Export Declaration Form for service/software exports within 30 days of month-end, realisation period 15 months (18 months for INR-invoiced/settled), declaration-based EDPMS/IDPMS closure up to Rs 10 lakh, wider set-off and third-party settlement, merchanting-trade rules, mandatory AD-bank SOPs, and advance/irrevocable-LC only for future exports where proceeds are unrealised beyond one year | Financial Services | ⚡ In force | — | 🟡 MED | Reserve Bank of India |
Net sector read
| Sector | Items | Net direction |
|---|---|---|
| Banks / Rates | 2 | 🔀 Mixed |
| Environment / Agri | 2 | 🔀 Mixed |
| Diplomacy / Climate | 1 | 🔀 Mixed |
| Fiscal | 1 | 🔀 Mixed |
Sector read: The time-boxed PIB + RBI + PRS sweep found only routine items: RBI's overnight VRRR liquidity operations and a dated-securities auction announcement, s.35A directions against six co-operative banks, and routine government releases (CAQM stubble-burning squads, an India-Japan climate-crediting manual, ceremonial items). Nothing is market-moving at index level; the sector reads are all neutral.
Watch next: The live policy clock is tomorrow's RBI decision — Polymarket prices a 25bp hike at 75% (~12% tail for 50bp) with the announcement due Wed 07-Oct. The policy watchlist carries 35 items after this run's six routine additions (all announced 05-Oct, all LOW); none has a HIGH severity today.
Cross-check: No HIGH-severity policy item to reconcile against Monday's pullers/draggers or the GIFT gap; the banks' sector read (neutral) matches the tape's own split — ICICI lifting the index while HDFC Bank dragged.
Sources checked: PIB (English, all-India RSS) ✅ · RBI press releases (RSS) ✅ · PRS billtrack ✅ · SEBI / CBDT / GST Council / DGFT / eGazette ⚠️
16. Layoffs & Job-Market Stress — The SIP-Retreat Early Warning JOB DATA AS OF 2026-08 (PLFS Monthly Bulletin Aug-2026) / 2025-07 (EPFO provisional, released 23-Sep-2025) - carried, see failures
Material layoff announcements, last 7 days (≥500 heads or ≥5% of workforce).
| Company | Headcount | % of workforce | Announced | Severity | Source |
|---|---|---|---|---|---|
| Nike | — | — | 2026-10-02 | MEDIUM | Reuters / OregonLive / Business Today (02-Oct-2026): new restructuring, further job cuts from 2027, targets USD 2.5bn savings; stock at a 13-year low. |
| Disney | — | — | 2026-10-03 | MEDIUM | Times of India / Times Now / Business Recorder (02-04 Oct 2026): fresh round of layoffs across marketing, Pixar, ABC News and ESPN; TV-business restructuring. |
| Oracle | 21,000 | 13.0% | 2026-06-23 | HIGH | Oracle annual report via Goodreturns (re-surfaced 02-Oct-2026): 141,000 FTEs vs ~162,000 a year earlier; AI reshaping roles; Indian employees in focus. |
| BMW | — | 20.0% | 2026-10-02 | MEDIUM | The Times of India (02-Oct-2026): management/leadership cuts (~20% across divisions) as AI takes over functions. |
| Comcast / NBCUniversal | — | — | 2026-10-02 | LOW | Times Now (02-Oct-2026): streaming jobs cut ahead of the spin-off. |
| Foghorn Therapeutics | — | 40.0% | 2026-10-02 | LOW | BioSpace layoff tracker (02-Oct-2026): 40% of workforce. |
| Job-market indicator | Value | Change |
|---|---|---|
| EPFO net payroll additions (monthly) | 21.04 L | +5.5% YoY |
| EPFO subscribers (monthly) | 9.79 L | — |
| PLFS unemployment rate | 5.00% | 2026-08 (PLFS Monthly Bulletin Aug-2026) / 2025-07 (EPFO provisional, released 23-Sep-2025) - carried, see failures |
Layoff events: The fresh 7-day window is led by Nike's further restructuring (cuts from 2027) and Disney's second round across marketing/Pixar/ABC/ESPN, with Oracle's 21,000-role cut (India centres named) re-surfacing and BMW's ~20% management cut citing AI outright. None of the events is India-headcount-specific; the Indian-IT layoff commentary continues without a new number.
Job market: The domestic job proxy is unchanged (PLFS Aug-2026 at 5.0%; EPFO block carried — the EPFO/PLFS pages were not re-read in this time-boxed run). No fresh deterioration signal, but no improvement either.
SIP channel (the one that matters): The SIP machine (August vintage, carried) is still the household cushion against job-market jitters — no visible stress in that channel today.
NIFTY impact: Stress level MEDIUM: heavy global events, unchanged domestic data. Not yet the pairing with FII selling that would mark a crash precondition (that needs job stress at ELEVATED/HIGH), but it is the slow variable to keep auditing.
🎯 Final Assessment — Today's Directional Bias
Overall Sentiment: ⚪ NEUTRAL-RANGEBOUND
Confidence Level: MEDIUM
| Level | Value |
|---|---|
| Expected spot range (day) | 22,450 – 22,750 |
| Support zone | 22,450 – 22,525 |
| Resistance zone | 22,650 – 22,800 |
🟢 Bullish (30%)
- Trigger: The GIFT gap holds and Nifty closes above the 22,600 pivot (200-WMA zone) with expiry short-covering into the 22,800 call tower
- Target 1: 22,700 · Target 2: 22,800
- Invalidation: below 22,500
🔴 Bearish (30%)
- Trigger: Rejection at 22,650-22,700 and a loss of 22,500 as FII cash supply persists; put-heavy positioning unwinds into the close
- Target 1: 22,400 · Target 2: 22,300
- Invalidation: above 22,650
⚪ Range-bound (40%)
- Trigger: —
- Range: 22,480–22,650
- Character: Expiry-day pin toward max pain 22,550: put writers defending 22,500 while the call towers at 22,800/23,000 cap the upside — the highest-probability path given the straddle width.
Key Factors Driving Today's View
- GIFT Nifty holds a +103-point gap-up to 22,659 ahead of the open — a modest gap-up with global risk-on behind it, but off a pre-market state read rather than a live tape.
- It is weekly expiry day: max pain 22,550 sits essentially at spot, and net put OI (+511.3 lakh) dwarfs call additions (+113.5) — pin dynamics and the 22,500 put wall are the day's gravitational centre.
- The wall structure is symmetric and tight: calls at 23,000 (146.6 lakh) / 22,800 (143.8) against puts at 21,500, 22,000 and 22,500 — with the Sensibull cohort's own short-CE wall at 22,900 and short-PE at 22,500 confirming the box.
- Monday's rebound was narrow and heavyweight-led: official A/D 0.88 with 5- and 20-session nets at -4,777 and -9,396 — participation is not confirming the bounce.
- Futures positioning shows covering, not fresh longs: front-month NIFTY OI fell 0.73% on a +0.40% price move, and BANKNIFTY front-month OI fell 1.94%.
- Global risk-on (Nasdaq record close, Asia firm, NVDA +2.1%) arrives with an Indian-IT divergence — Infosys and Wipro ADRs fell hard against that tape.
- FIIs remain net sellers of Indian cash (₹4,699 cr on 05-Oct) while DIIs absorb (₹5,182 cr); USD/INR ~96.3 and DXY 102.16 keep the structural overhang intact.
- Crude eases (~$100.5 Brent, -1.7%; MCX -2.60%) — a modest macro relief, but the level stays high and Polymarket keeps a 28% chance of WTI touching $100 in October.
- Classic bubble flags unchanged at 3 (ELEVATED: CAPE 41.67, Buffett 244%, margin debt +37.2% y/y) while credit and the VIX term structure stay calm — valuation risk, not stress risk, today.
⚠️ Risk Warnings
- Expiry-day liquidity and pinning: max pain 22,550 and heavy put writing can hold the index in a narrow band, but the same positioning makes late-day breaks sharper than the open suggests.
- FII cash supply persistence: another net-sell session would keep every rally capped and pressure the rupee.
- IT divergence: Indian IT ADRs fell while the Nasdaq made a record close — if the ADR weakness carries into the cash market it offsets the global bid (IT is a heavy NIFTY weight).
- Event risk ahead: the RBI's rate decision tomorrow (a 25bp hike is 75% priced) and the FOMC minutes Wednesday night; the ForexFactory feed does not carry the RBI event, so it is sourced from Polymarket and carried context.
- The 1.62% single-session gold spike is the macro stress tell to watch — sustained gold strength alongside equities historically flags a divergence.
- Data gaps disclosed in the footer: cluster 12 (Nifty Buddy) not collected; 18 reused from 05-Oct; MCX option ladder unparsed; FINRA margin-debt carried; PR Sundar's video is the 01-Oct report (no 06-Oct pre-market upload existed at run time).