Nifty Chronicles
NIFTY 50 Pre-Market Analysis — Thursday, 8 October 2026
Weekly expiry Tue, 13 Oct · Monthly expiry Tue, 27 Oct · Post-RBI-hike consolidations: the MPC hiked 25bp to 5.50% on 07-Oct (first hike in over three years) and Nifty fell 0.76% to 22,603.05; GIFT Nifty's live pre-open tape is soft (22,556, -47.05 vs the close, a rejected early pop), the fresh 13-Oct weekly chain is one-sided call-written (PCR 0.7124, max pain 22,650), and TCS Q2 results land after market hours. · Published ~08:25 IST, before the 09:15 open. Informational & educational only — no trade recommendations (SEBI-compliant).
1. Global Cues Snapshot
GIFT NIFTY — full OHLC (quote saved 06:33 IST live (Session I), 0 min before render)
| Metric | Value | Metric | Value |
|---|---|---|---|
| LTP | 22,556.00 | Change | -2.00 (−0.01%) |
| Open | 22,579.50 | Day High | 22,579.50 |
| Day Low | 22,549.50 | Prev Close | 22,558.00 |
| Implied gap vs NIFTY 22,603.05 | -47.1 pts | vs own prev close | -2.0 pts |
Cross-check source: 22,557.00 — agrees
Gap read: GIFT's live Session I tape is soft-borderline gap-down: 22,556.0 (-2.0 vs its own new prev close, -47.05 vs NIFTY's 22,603.05 close) after opening at the day's high 22,579.5 and sliding to 22,549.5 - a rejected early pop. The move is convergent with the overnight tape (US red, Asia mostly red) rather than an India-specific divergence, and niftytrader's futures-basis widget reads 'Gap-Down Expected'. The divergence to keep in view is that GIFT's own change is only -0.01% while the cross-session gap is -47 pts, i.e. a soft open, not a panic one.
| Market / Asset | Level | Change | Session OHLC |
|---|---|---|---|
| S&P 500 | 7,801.77 | −0.22% | O 7,792.98 · H 7,807.02 · L 7,763.34 |
| Dow Jones | 51,179.87 | −0.66% | O 51,406.44 · H 51,406.44 · L 50,917.42 |
| Nasdaq Composite | 27,538.69 | −0.22% | O 27,430.54 · H 27,547.20 · L 27,341.31 |
| CBOE VIX | 15.08 | +0.47% | O 15.21 · H 16.01 · L 14.97 |
| FTSE 100 | 10,458.50 | −0.79% | O 10,542.18 · H 10,542.18 · L 10,445.42 |
| DAX | 25,104.36 | −1.35% | O 25,280.67 · H 25,347.09 · L 25,038.51 |
| CAC 40 | 7,769.21 | −1.22% | — |
| Euro Stoxx 50 | 6,180.29 | −1.47% | — |
| Nikkei 225 | 69,410.01 | −0.89% | O 69,840.64 · H 69,918.20 · L 69,387.55 |
| Hang Seng | 24,130.50 | −0.62% | O 24,172.29 · H 24,266.92 · L 24,071.41 |
| Shanghai Composite | 3,842.20 | +0.31% | O 3,839.25 · H 3,851.22 · L 3,833.09 |
| KOSPI | 6,780.46 | −0.34% | O 6,808.68 · H 6,810.83 · L 6,750.58 |
| Taiwan TAIEX | 49,806.37 | −0.03% | O 49,857.32 · H 49,966.89 · L 49,567.52 |
| ASX 200 | 8,699.60 | −0.32% | O 8,727.70 · H 8,727.70 · L 8,677.60 |
| Straits Times | 5,608.44 | −1.63% | O 5,670.60 · H 5,679.15 · L 5,603.70 |
| NIFTY 50 | 22,603.05 | −0.76% | O 22,690.45 · H 22,717.65 · L 22,546.30 |
| Sensex | 72,638.70 | −0.59% | O 72,965.38 · H 73,018.82 · L 72,468.72 |
| USD/INR | 96.66 | −0.10% | — |
| Dollar Index (DXY) | 102.24 | −0.00% | — |
| Brent crude | 101.22 | +1.02% | — |
| WTI crude | 89.08 | +0.91% | — |
| Gold (USD) | 4,132.50 | −0.20% | — |
| Infosys (ADR) | 10.55 | 0.00% | — |
| HDFC Bank (ADR) | 22.14 | −1.25% | — |
| ICICI Bank (ADR) | 27.86 | −0.57% | — |
| Wipro (ADR) | 1.67 | −0.59% | — |
| India VIX | 13.93 | — | prior session close |
Global read: Overnight was a broad risk-off tape, not a mild one: Wall Street faded from records (Dow opened at its high and closed -0.66%, S&P 500 -0.22%, Nasdaq -0.22%) as the 30-year Treasury yield hit a 2002 high and the US 10Y closed 5.277%, Europe sold off hard (DAX -1.35%, Euro Stoxx 50 -1.47%) and Asia is red again this morning (Nikkei -0.89%, KOSPI -0.34%, ASX -0.32%). Brent is back above the $100 headwind level pre-market (101.22, +1.02%), DXY holds at 102.24 and gold is soft (4,132.5); India's ADRs split with global banks down (HDFC Bank -1.25%, ICICI -0.57%) and IT/Wipro lower. The net for the open is gap-down pressure rather than support, with the rupee the only mild positive (96.658, marginally stronger).
2. Critical Macro Indicators
| Indicator | Value | Change | Status |
|---|---|---|---|
| Brent / WTI | $101.22 / $89.08 | +1.02% / +0.91% | — |
| USD/INR · DXY | 96.66 · 102.24 | −0.10% · −0.00% | — |
| India VIX | 13.93 | — | — |
| Gold (₹/10g) | ₹1,49,169 | +2.05% / 10d | — |
| Yield curve 10Y–2Y | 0.51 pp (51 bps) | 2026-10-07 | 🟢 positive |
| Yield curve 10Y–3M | 1.06 pp (106 bps) | 2026-10-07 | 🟢 positive |
| NY Fed recession prob. | 13.88% | 12-mo ahead Aug 2027; data through Aug 2026; updated 06-Sep-2026 | 🟢 low |
| Sahm Rule | 0 | 2026-09-01 | 🟢 no trigger |
| HY / IG credit spreads | 303 / 83 bps | 2026-10-06 | 🟢 normal |
| VIX term structure | VIX9D 11.78 < VIX 15.08 < VIX3M 17.72 | — | 🟡 contango |
| Shiller CAPE / Buffett | 41.8 / 244% | 2026-10-07 | 🔴 bubble territory |
| TED spread | discontinued by FRED (last obs 2022-01-21) — retained as a framework footnote only | ||
Crude: Brent is back above $100 ($101.22, +1.02%) and WTI $89.08 (+0.91%) after Wednesday's settle just under $100, with the overnight Middle East re-escalation (another US carrier deployment, Houthi tanker attacks, a US Gulf storm) as the driver. The level, not the daily direction, is the import-bill problem for India, and it arrives alongside a hawkish RBI that hiked for inflation - a two-sided pressure on rate-sensitives and the rupee.
Currency: USD/INR is 96.658, marginally stronger (-0.11%) versus Wednesday's 96.76 settlement, but the level is a five-month low and the rupee crossed 97 intraday during the RBI session - the currency has ignored the hike. DXY is flat at 102.241 after Wednesday's +0.40% climb. The rupee remains the pressure valve for the FII cash exit: no fresh shock this morning, no relief either.
Gold: COMEX gold settled -1.11% Wednesday at $4,140.70 and is -0.20% more at $4,132.50, with silver -1.43% then -0.50% to $59.99 - the hedge bid cooled with the tape rather than spiking on the risk-off. In rupee terms gold is effectively flat after a two-session round-trip (Rs 1,49,169/10g, -766 on the day). No safe-haven surge is being priced.
Yield curve: The US curve stays un-inverted and slowly steepening - 10Y-2Y +51 bps and 10Y-3M +106 bps (both 07-Oct) - with the recession block quiet (NY Fed 13.88%, Sahm 0.00). The long end is the story: the 30-year hit a 2002 high and the 10Y closed 5.277%, a valuation headwind for long-duration equities. India's 10Y G-Sec is 7.23% (+2 bps), below its own flag threshold.
Credit: Credit remains calm-to-tight: HY OAS 303 bps and IG OAS 83 bps (06-Oct), both well inside stress lines, and the US VIX term structure sits in clean contango (spot 15.08 < 3M 17.72, 9D 11.78). No credit-based warning today - the established 2026 mechanism to watch is the AI build-out's debt layer, not a credit accident.
3. Economic Events — Today & This Week
Today (2026-10-08 — IST)
| Time (IST) | Event | Ccy | Impact | Forecast vs prev |
|---|---|---|---|---|
| 00:30 | Consumer Credit m/m | USD | Low | F: 14.5B · P: 18.1B |
| 04:31 | RICS House Price Balance | GBP | Low | F: -30% · P: -28% |
| 05:20 | Current Account | JPY | Low | F: 2.14T · P: 2.52T |
| 05:30 | MI Inflation Expectations | AUD | Low | F: · P: 4.9% |
| 09:05 | 30-y Bond Auction | JPY | Low | F: · P: 4.08|3.8 |
| 10:30 | Economy Watchers Sentiment | JPY | Low | F: 46.7 · P: 46.4 |
| 11:30 | German Trade Balance | EUR | Low | F: 19.0B · P: 21.3B |
| 13:35 | Gov Board Member Martin Speaks | CHF | Low | F: · P: |
| 14:00 | BOE Credit Conditions Survey | GBP | Low | F: · P: |
| 14:00 | FOMC Member Waller Speaks | USD | Medium | F: · P: |
| 14:30 | MPC Member Pill Speaks | GBP | Low | F: · P: |
| 14:45 | MPC Member Greene Speaks | GBP | Low | F: · P: |
| 14:45 | Eurogroup Meetings | EUR | Low | F: · P: |
| 17:00 | ECB Monetary Policy Meeting Accounts | EUR | Low | F: · P: |
| 17:45 | BOE Gov Bailey Speaks | GBP | High | F: · P: |
| 18:00 | Unemployment Claims | USD | Medium | F: 200K · P: 197K |
| 18:30 | MPC Member Lombardelli Speaks | GBP | Low | F: · P: |
| 19:30 | Final Wholesale Inventories m/m | USD | Low | F: 0.7% · P: 0.7% |
| 20:00 | Natural Gas Storage | USD | Low | F: 79B · P: 64B |
| 22:31 | 30-y Bond Auction | USD | Low | F: · P: 5.31|2.6 |
| 23:10 | FOMC Member Musalem Speaks | USD | Low | F: · P: |
Rest of the week (high/medium impact)
| Date | Time (IST) | Event | Ccy | Impact |
|---|---|---|---|---|
| 2026-10-09 | 07:00 | CPI y/y (SEP) | CNY | Medium |
| 2026-10-09 | 07:00 | CPI m/m (SEP) | CNY | Low |
| 2026-10-09 | 05:00 | Household Spending y/y | JPY | Low |
| 2026-10-09 | 11:30 | Prelim Machine Tool Orders y/y | JPY | Low |
| 2026-10-09 | 12:30 | SECO Consumer Climate | CHF | Low |
| 2026-10-09 | 13:30 | Italian Industrial Production m/m | EUR | Low |
| 2026-10-09 | 14:45 | ECOFIN Meetings | EUR | Low |
| 2026-10-09 | 18:00 | Employment Change | CAD | High |
| 2026-10-09 | 18:00 | Unemployment Rate | CAD | High |
| 2026-10-09 | 08:30 | Trade Balance (AUG) | CNY | Medium |
| 2026-10-09 | 08:30 | Exports y/y (AUG) | CNY | Medium |
| 2026-10-09 | 08:30 | Imports y/y (AUG) | CNY | Medium |
| 2026-10-09 | 19:30 | Prelim UoM Consumer Sentiment | USD | Medium |
| 2026-10-09 | 19:30 | Prelim UoM Inflation Expectations | USD | Medium |
| 2026-10-09 | RBI FX Reserves (week ended 02-Oct) | INR | Low | |
| 2026-10-10 | 01:30 | FOMC Member Collins Speaks | USD | Low |
Events read: India's own event risk has passed (RBI hiked 25bp to 5.50% on 07-Oct), leaving a thin global slate: FOMC's Waller at 14:00 IST, ECB meeting accounts at 17:00, BOE Governor Bailey at 17:45 (the day's only High-impact print), US jobless claims at 18:00 and a US 30-year auction at 22:31 IST. The domestic catalyst is corporate: TCS Q2 results after market hours. No INR data point is scheduled.
4. F&O Positioning — What Smart Money Is Doing
Index futures
| Index | LTP | Chg% | OI | OI Chg% | OI Chg | Signal |
|---|---|---|---|---|---|---|
| NIFTY | 22,632.90 | −0.71% | 1,90,23,355 | +1.80% | 3,36,440 | Short buildup |
| NIFTY | 22,737.50 | −0.67% | 23,75,425 | +1.42% | 33,150 | Short buildup |
| NIFTY | 22,876.20 | −0.64% | 2,82,100 | +5.26% | 14,105 | Short buildup |
| BANKNIFTY | 55,249.60 | +0.00% | 23,88,810 | +4.44% | 1,01,610 | Long buildup |
| BANKNIFTY | 55,551.20 | +0.03% | 1,66,710 | +3.48% | 5,610 | Long buildup |
| BANKNIFTY | 55,858.20 | +0.03% | 29,490 | +58.55% | 10,890 | Long buildup |
| FINNIFTY | 24,985.60 | −0.04% | 24,660 | −7.64% | -2,040 | Long unwinding |
| FINNIFTY | 24,880.30 | 0.00% | 240 | 0.00% | 0 | Flat |
| FINNIFTY | 25,015.00 | 0.00% | 0 | — | 0 | Flat |
| MIDCPNIFTY | 13,760.60 | −0.69% | 19,88,040 | +0.34% | 6,720 | Short buildup |
| MIDCPNIFTY | 13,809.75 | −0.71% | 83,640 | +3.57% | 2,880 | Short buildup |
| MIDCPNIFTY | 13,831.00 | −0.94% | 1,680 | +40.00% | 480 | Short buildup |
| NIFTYNXT50 | 69,627.60 | −0.90% | 16,625 | +0.15% | 25 | Short buildup |
| NIFTYNXT50 | 69,706.40 | −0.92% | 500 | +66.67% | 200 | Short buildup |
| NIFTYNXT50 | 70,493.00 | 0.00% | 25 | 0.00% | 0 | Flat |
Futures confirm the bearish turn: NIFTY's 27-Oct contract fell 0.71% to 22,632.9 with OI up 336,440 (+1.8%) - a short build-up - while BANKNIFTY's 27-Oct contract was flat (+0.004%) with OI up 101,610 (+4.44%), the one long build on the board. Front-month NIFTY premium to spot has compressed to about 30 points, and the far months (Nov/Dec) also built shorts, so the positioning is one-directional: supply, not accumulation.
Option Chain Key Levels — nearest expiry 2026-10-13
| Type | Strike | OI (Lakh) | Significance |
|---|---|---|---|
| 🔴 Strong Resistance | 23,000 | 96.3 | Highest Call OI |
| 🔴 Strong Resistance | 22,800 | 94.6 | |
| 🔴 Strong Resistance | 22,700 | 86.1 | |
| 🟢 Strong Support | 21,500 | 71.1 | Highest Put OI |
| 🟢 Strong Support | 22,000 | 71.0 | |
| 🟢 Strong Support | 22,600 | 62.5 |
PCR: 0.7124 · Max pain: 22650 · India VIX: 13.93 · ATM straddle: 22,445.05–22,724.30 (₹279.25 width)
OI change: The fresh 13-Oct weekly chain is one-sided call-side: net call OI built +591.2 lakh against net put +210.6 lakh, PCR slid to 0.7124 (the bearish edge of the neutral band) and there was not a single call-OI reduction anywhere in the chain. The resistance stack thickened exactly overhead - 22,800 (94.6 lakh, the largest call add at +53.1) and 23,000 (96.3 lakh, the top call wall) just above the max-pain magnet at 22,650 - while puts were unwound precisely at 22,700-22,800 where calls were written. Support is a two-step structure: the ATM battle wall at 22,600 (highest combined OI, 129.4 lakh) and the deeper anchors at 22,000/21,500 (71.0/71.1 lakh).
Sensibull Verified Cohort (#VerifiedBySensibull)
| Index | Signal | Bias % (bull-side) | Cohort PCR | CE-short wall | PE-short wall |
|---|---|---|---|---|---|
| NIFTY | NEUTRAL | 55.5 | 0.61 | 23200 (33800 lots) | 22500 (16965 lots) |
| BANKNIFTY | NEUTRAL | 63.3 | 1.04 | 54400 (600.0 lots) | 54400 (1050.0 lots) |
| SENSEX | NEUTRAL | 46.2 | 1 | 73100 (7000.0 lots) | 71800 (7000.0 lots) |
| FINNIFTY | — | — | |||
| MIDCPNIFTY | — | — |
4B. India VIX — IV Rank & IV Percentile
| Metric | Value |
|---|---|
| India VIX (latest close) | 13.93 |
| 252-session high / low | 27.89 / 9.15 |
| IV Rank (0–100) | 25.5 — Low |
| IV Percentile | 67.5% |
Trailing 252 sessions (2025-09-22 → 2026-10-07) of India VIX EOD closes. IV Rank = (VIX − session low) / (session high − low) × 100; IV Percentile = share of those sessions that closed below the current VIX. Derived deterministically by scripts/vix-iv-rank.mjs; window high/low include the day's own close.
India VIX closed 13.93, up 2.35% on a -0.76% cash session - vol is being bid as the index tests the top of its OI range. Against the trailing 252-session window, IV Rank is 25.51 (Low) yet IV Percentile is 67.46: the two diverge because one outsized earlier spike anchors the top of the window, so near-term vol is priced cheap versus the year's extremes but mid versus the typical session. The market is pricing little tail fear even as the tape deteriorates - descriptive only.
5. Yesterday's NIFTY Movers
| Top 5 Pullers | Points | Top 5 Draggers | Points |
|---|---|---|---|
| ICICI Bank | +23.06 | HDFC Bank | -29.19 |
| Bharti Airtel | +15.95 | Larsen and Toubro | -17.53 |
| Kotak Mahindra Bank | +13.07 | Infosys | -16.88 |
| Coal India | +1.49 | Titan Company | -15.63 |
| Max Healthcare Institute | +0.89 | Reliance Industries | -15.07 |
Net contribution (top movers): -179.40 pts
Wednesday's -179.4-point net contribution was narrow and negative: only 8 of 50 names positive against 41 negative (positive sum +55.46 vs draggers -234.86). ICICI Bank (+23.06), Bharti Airtel (+15.95) and Kotak Mahindra Bank (+13.07) carried the pullers, while HDFC Bank (-29.19), L&T (-17.53), Infosys (-16.88), Titan (-15.63) and Reliance (-15.07) did the damage. The banks split exactly as PR Sundar described - HDFC Bank the sole drag while ICICI/Kotak/PSU banks held.
6. Technical Levels for Today
| Level | Price |
|---|---|
| R3 | 22,869.70 |
| R2 | 22,793.70 |
| R1 | 22,698.40 |
| Pivot | 22,622.30 |
| S1 | 22,527.00 |
| S2 | 22,451.00 |
| S3 | 22,355.70 |
Moving averages
| MA | Level | Spot vs MA |
|---|---|---|
| 5 DMA | 22,595.46 | +0.03% above |
| 10 DMA | 22,812.41 | −0.92% below |
| 20 DMA | 23,088.16 | −2.10% below |
| 50 DMA | 23,796.14 | −5.01% below |
Nifty closed 22,603.05 (-0.76%) after touching a low of 22,546.30, and sits above the 5-DMA (22,595.46) but 2.1% below the 20-DMA (23,088.16) and far under the 50-DMA (23,796.14): the short end is flat, the trend still down. Classic pivots for today: PP 22,622.3, R1 22,698.4, R2 22,793.7, R3 22,869.7; S1 22,527.0, S2 22,451.0, S3 22,355.7 - with the PP sitting almost exactly on the 22,650 max-pain magnet and the 22,600 combined-OI battle wall just below.
6B. Market Breadth — How Many Stocks Actually Moved
| Metric | Value |
|---|---|
| Advancers | 1516 |
| Decliners | 2077 |
| Net (A − D) | -561 |
| A/D ratio 0.73 | 41.03% advancing · 3,695 traded |
| Net over last 5 sessions | -1546 |
| Net over last 20 sessions | -8415 |
NSE top movers — 2026-10-07
| Top gainers | LTP | Chg% | Top losers | LTP | Chg% |
|---|---|---|---|---|---|
| INDIAGLYCO | 382.70 | +19.99% | LEXUS | 9.48 | −12.30% |
| ACEVECTOR | 31.11 | +19.98% | SUPREMEINF | 54.67 | −10.96% |
| VALUE360 | 73.85 | +19.98% | AVROIND | 6.13 | −10.51% |
| MYMUDRA | 99.20 | +19.95% | |||
| MONEYVIEW | 60.46 | +19.72% | |||
| HTEL | 87.94 | +19.14% |
Filtered to liquid NSE equity names (volume ≥ 1,00,000); 6 illiquid or non-equity entries were excluded from the raw all-securities list.
Official exchange breadth for 07-Oct is weak: 1,516 advancers vs 2,077 decliners, A/D 0.73 and only 41.03% of 3,695 traded names up on the -0.76% close - a narrow, heavyweight-pressured tape, not broad participation. The multi-session nets remain deeply negative (-1,546 over 5 sessions, -8,415 over 20 through 07-Oct), so the prior session's +1,207 bounce was not followed through. Tuesday's relief advance was a two-day event, not a breadth turn.
NSE MCP get_market_breadth (2026-10-07) — Exchange data via NSE MCP (mcp.nseindia.in) — informational use only, not endorsed by NSEIL.
7. Key News Headlines — NIFTY, US & India
🇺🇸 US / Global
- Wall Street ends lower, off record highs, as Treasury yields climb — Reuters 🔴 US risk-off overnight - records lost with the long end at a 2002 high; a soft GIFT open is the base case.
- 30-Year Treasury Yield Hits 2002 High; S&P 500, Nasdaq Fall From All-Time Highs on inflation worry — TradingView / NDTV Profit 🔴 The long end is the driver - inflation worry plus oil above $100 is a valuation headwind for India's IT and consumer names.
- Asian Stocks Drop as Oil Stokes Inflation Worries (China reopens after holiday) — Bloomberg / investingLive 🔴 Asia opens lower into India's session and Chinese markets return from Golden Week, adding a reopen-flow variable.
- Oil Climbs as U.S. Sends Another Aircraft Carrier to Middle East; Brent stays ~$100 on Hormuz and tanker risk — WSJ / Gulf News 🔴 Crude geopolitics re-escalated overnight - a direct negative for the import bill and the rupee.
🇮🇳 India
- RBI hiked repo rate 25 bps to 5.50% - first hike in nearly four years; GDP forecast raised to 7.1%, hawkish stance — Moneycontrol / ET 🔴 The hike landed and Nifty still fell 0.76%; direction now shifts to the stance and to rate-sensitive sectors.
- FIIs net sell Rs 6,121 crore, DIIs net buy Rs 4,597 crore on Oct 7 — Moneycontrol 🔴 FII selling widened vs Oct 6's Rs 2,961 cr while DII absorption shrank to 75.1% of it - flows remain the drag under every bounce.
- Rupee ends at 5-month low of 96.78 despite RBI rate hike (crossed 97/$ intraday) — New Indian Express / Moneycontrol 🔴 The currency ignored the hike - a weak rupee keeps FII-outflow and imported-inflation logic alive.
- Nifty takes support at 22,600 despite a hawkish RBI; analysts map a 22,500-22,800 range — Moneycontrol / CNBC TV18 ⚪ Sell-side consensus is a 22,500-22,800 box with 22,600 the defended support - the range edges frame the session.
NIFTY-specific
- Nifty Outlook for October 8: RBI rate hike, hawkish stance put focus on 22,500-22,800 range — CNBC TV18 ⚪ Sell-side levels cluster in a 300-point box with 22,600 the support the desk defends.
- Technical View: Nifty likely to consolidate below 22,800; 55,200 crucial for further upside in Bank Nifty — Moneycontrol ⚪ 22,800 caps the upside and Bank Nifty's 55,200 is the parallel gate - both are the OI walls in cluster 06.
- TCS Q2 results today: weak quarter expected, margins steady, Porsche-led deal pipeline, dividend decision — CNBC TV18 / Moneycontrol / Upstox ⚪ Earnings season's first heavyweight print lands after market hours - IT will trade the guidance more than the number.
17. Market Charts — @Barchart & @Patterns0001 (X)
Latest chart image posts from the tracked X accounts, captured verbatim. Third-party content, reproduced for information only — all rights remain with the original posters. Not investment advice; no trade setups reproduced.
@Barchart
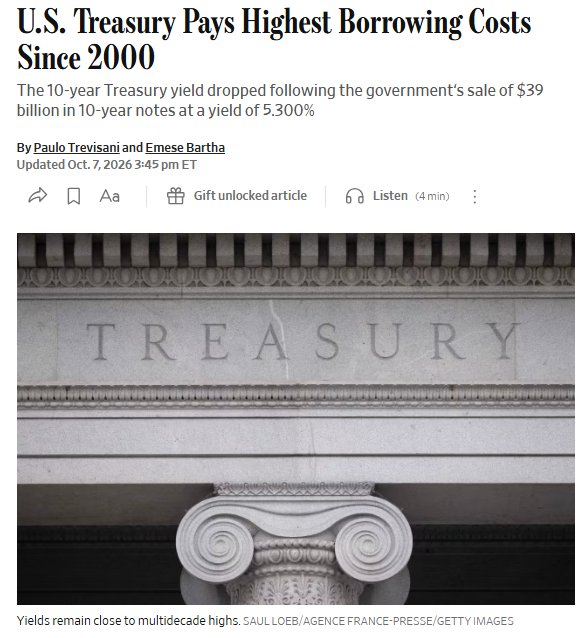
U.S. Treasury just auctioned 10-Year Treasuries at a yield of 5.3%, the highest level this century 🚨 🚨 https://t.co/nduSFGNJ6I — View on X ↗
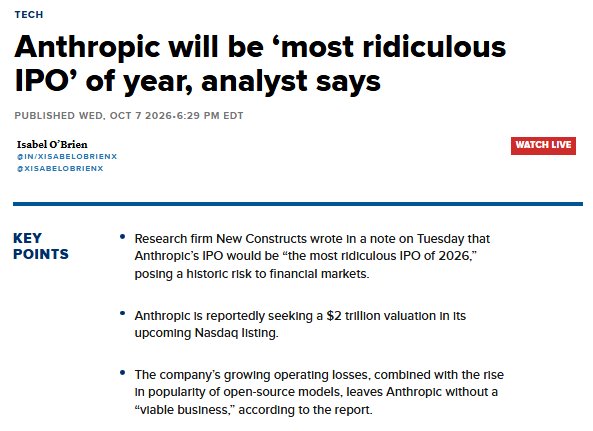
Anthropic's IPO poses a historic risk to financial markets, and should only be valued at $150 Billion, warns Research firm New Constructs 🚨 🚨 https://t.co/hfwvqRdU3w — View on X ↗
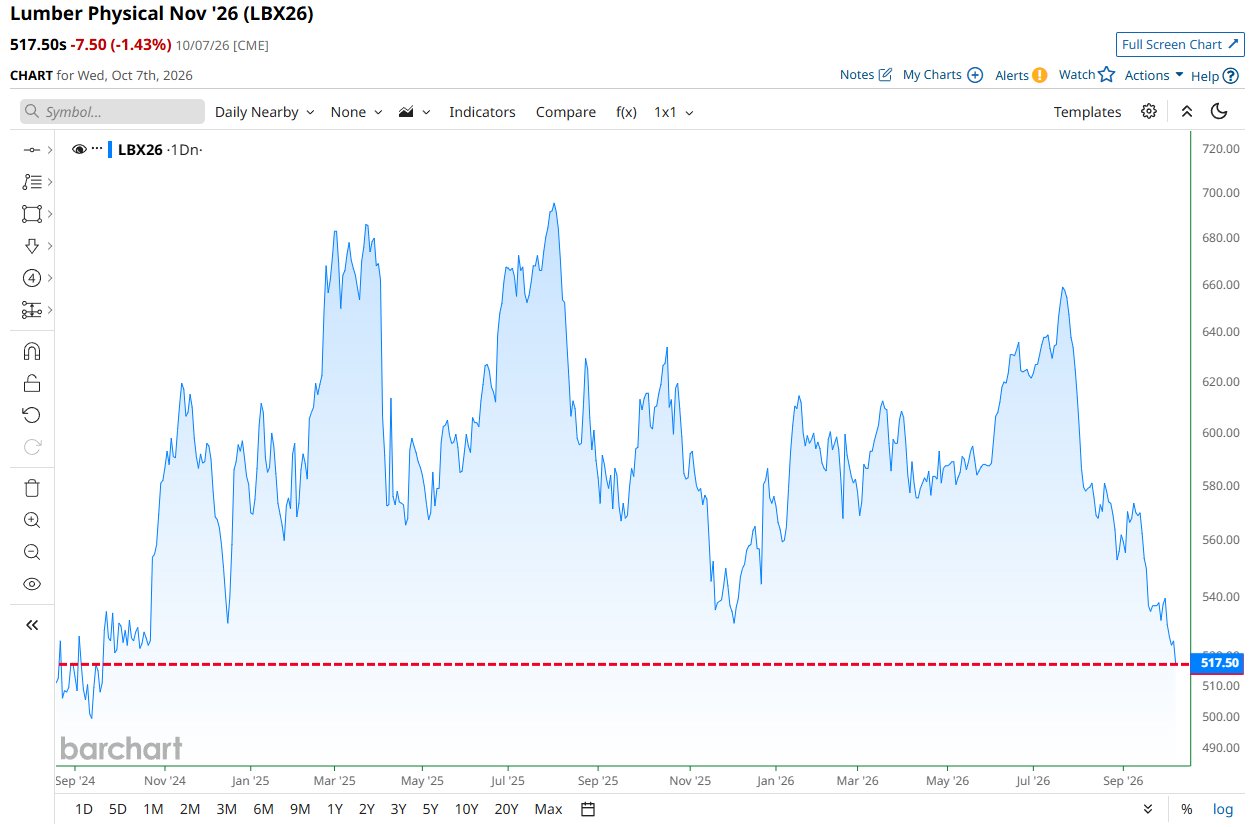
BREAKING 🚨: Lumber Lumber falls to lowest price in more than 2 years 📉 📉 https://t.co/IH3HJpDX5t — View on X ↗
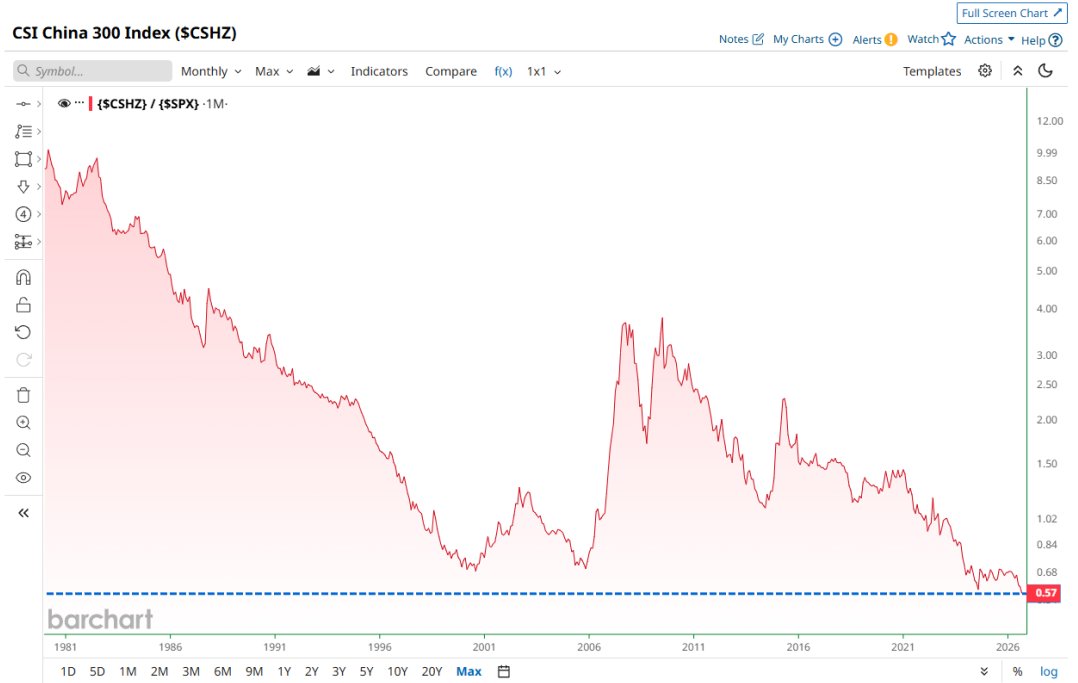
BREAKING 🚨: China Chinese Stocks are now underperforming the S&P 500 by the largest margin in history 📉 📉 https://t.co/Iz03HyjdPG — View on X ↗
@Patterns0001
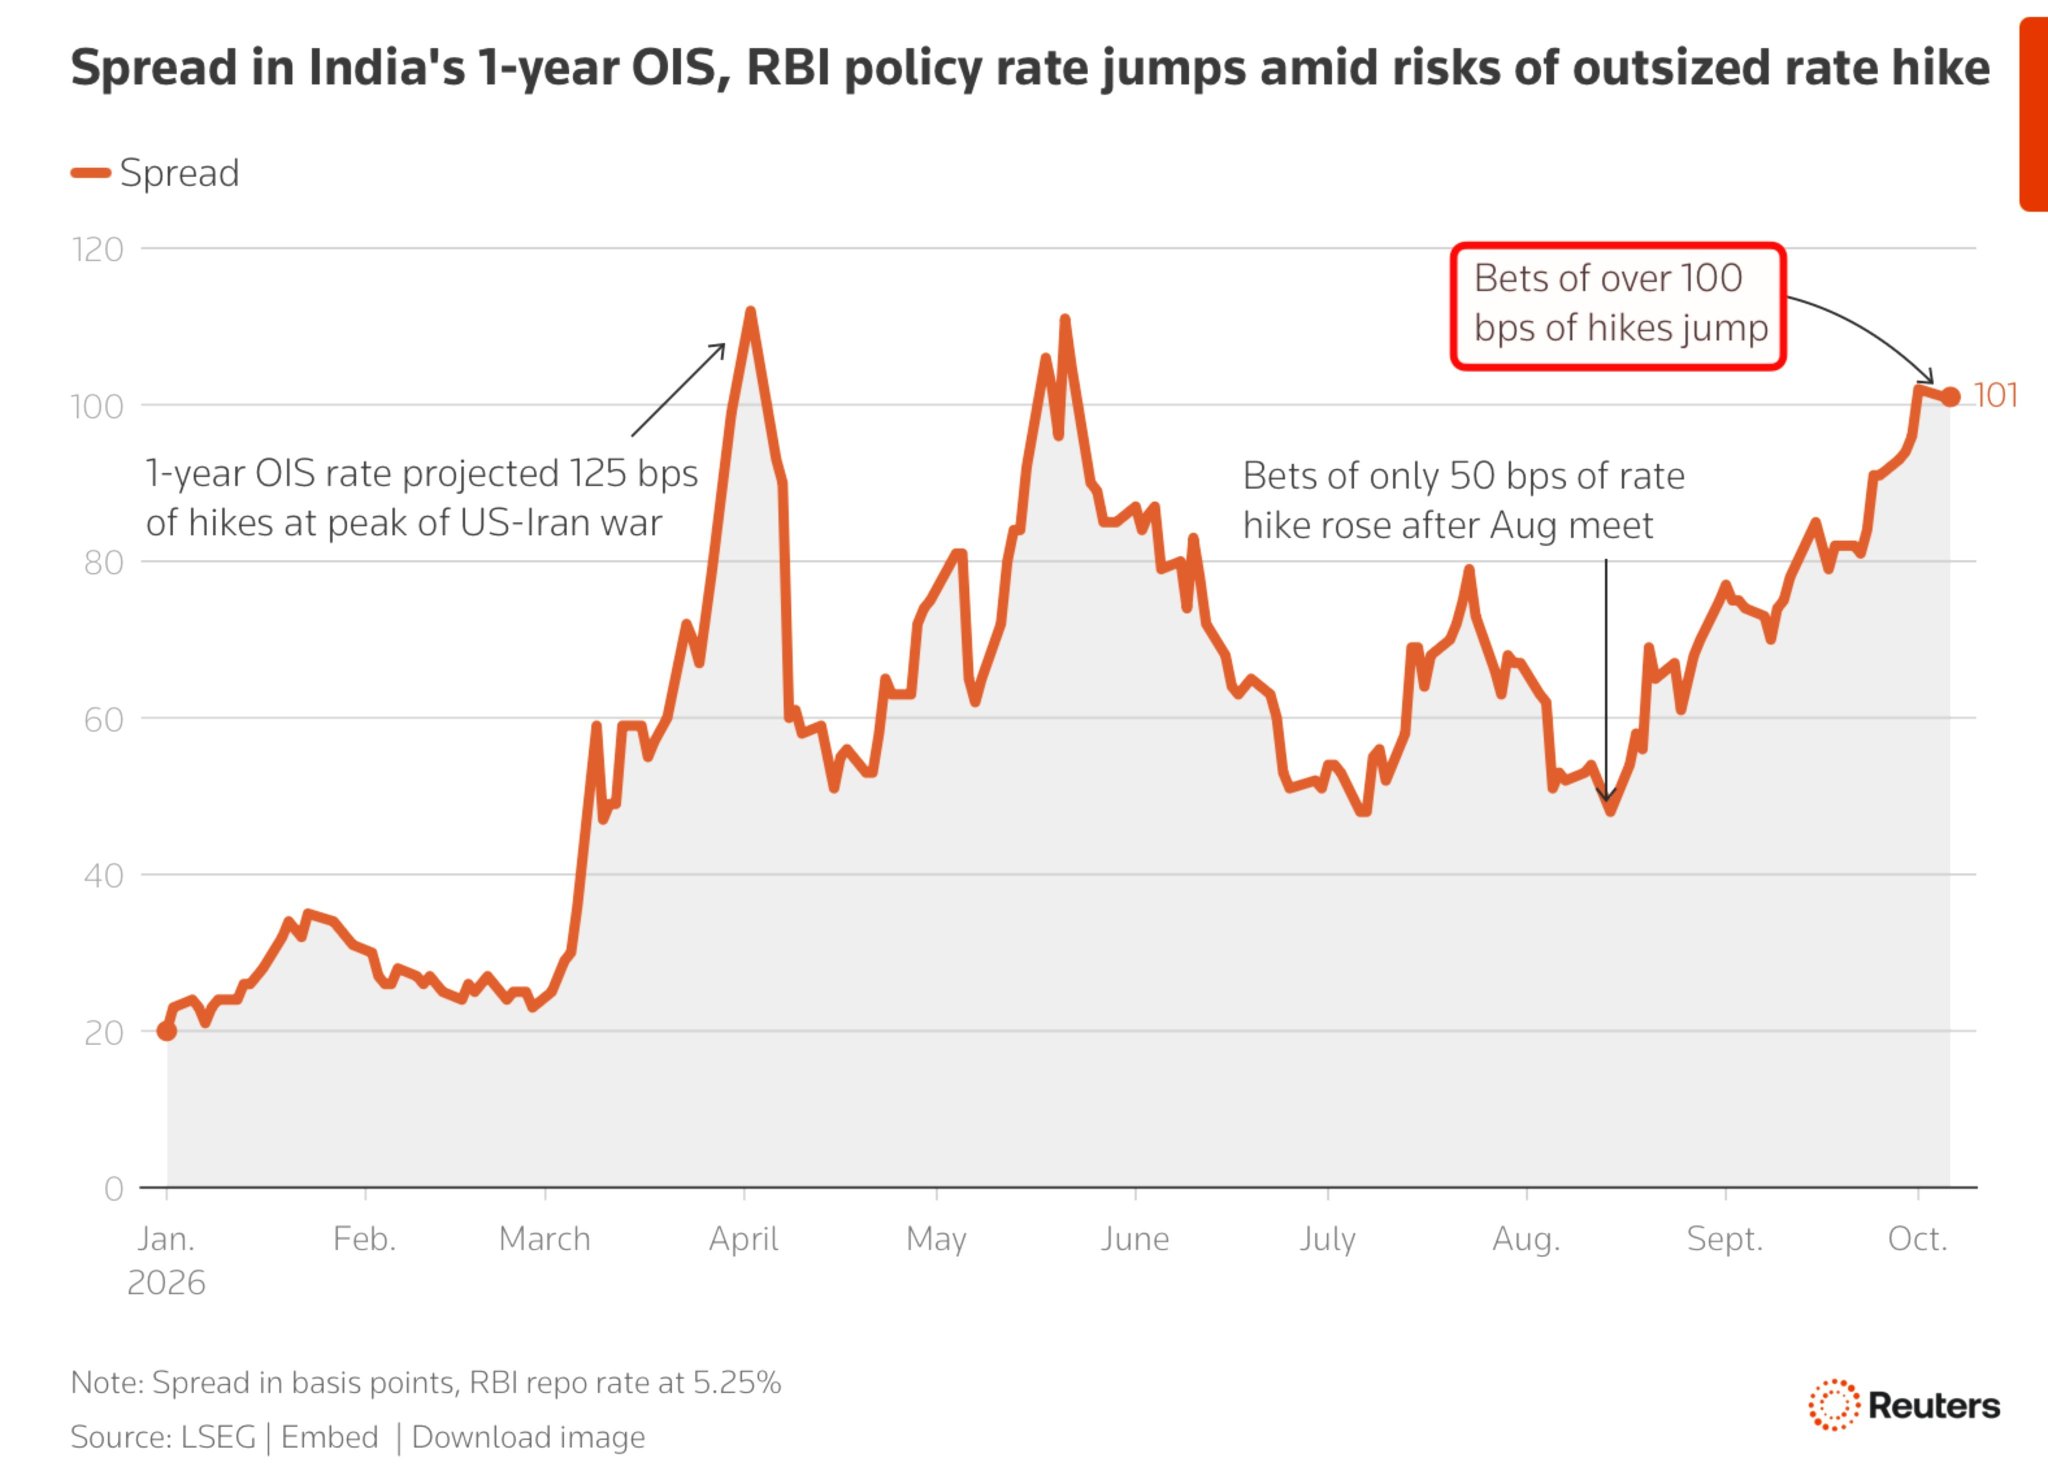
MARKET IS PREPARING FOR BIGGER RATE HIKE: Markets are now pricing in 101 bps (1.01%) of RBI rate hikes over the next Year As, INDIA'S 1-Year OIS spread hits 101 bps — The Highest in more than 4 months https://t.co/RzOwfvNjn5 — View on X ↗
8. PR SUNDAR'S VIEW
| Item | View |
|---|---|
| Bias | Clearly bearish and worsening: he says the two-to-three-day 'smart recovery' has completely vanished and now expects Nifty to break 22,500 again (GIFT down another ~100 pts after the US close). He now sees the 22,200 double-bottom support possibly breaking, in October rather than waiting for December; the only swing factor he leaves open is the corporate-results season. |
| Key levels | 22,500-23,000 = his current box; a break of 22,500 opens the next box 22,000-22,500, which he calls 'very very bad'; 22,200 = the double-bottom support now seen as likely to break; 23,000 = the level he hopes the year can still close near. He notes the Nifty futures premium collapsed from ~100 pts to ~15 pts, which is why call options are 'falling like anything'. |
| Rationale | Reads the RBI 25bp hike as priced only by the banks - PSU Bank index +1%, ICICI/Axis/Kotak higher, Kotak at a swing high - with HDFC Bank the sole drag on Bank Nifty. IT is the disaster: Infosys broke below 1,000 and the IT index is 'doing very very badly', with none of the expected pre-TCS short-covering. FIIs doubled their selling and are net sellers for nine consecutive sessions totalling ~Rs 55,000 cr, with the US 10Y at a 24-year high, crude higher and US futures lower driving GIFT down ~100 pts. |
| Cross-check with data | His box floor (22,500) and premium-collapse read align with the 06 keys: PCR 0.71, heavy fresh call writing at 22,600 (+47.2 lakh) and 22,700-22,800, max pain 22,650. He is the most bearish of the three expert reads, and his 22,500 line sits just below today's S1 22,527 and the straddle's lower breakeven 22,445. |
8B. Be Sensibull Analysis View
| Item | View |
|---|---|
| Bias | Two-sided and explicitly conditional with a bearish tilt: nothing is settled until 22,600 decides it. Holding the 22,600 (200-WMA/trendline) zone keeps a relief 'pump' alive toward 23,000 then 23,500-24,000, while a break of 22,400 opens 'scary targets' - at least 20,000 and potentially 17,000. He warns the risk-reward of being long is asymmetrically poor and cautions against bottom-fishing. |
| Key levels | 22,600 = the 200-week MA / trendline support that must hold for any relief rally; 22,400 = the hard break level (opens 20,000, potentially 17,000); upside if 22,600 holds: 23,000, then 23,500, then 24,000. He notes a lot of option resistance sits above 22,600. Macro: USD/INR breakout (~97) is the dominant read; US/Asia bleeding; gold/silver down; US 10Y stabilising; oil falling but the INR move offsets it. |
| OI / PCR / IV commentary | PCR '0.7 around and 0.8 overall' - weak, 'no questions asked'. Participant futures: FII and pro net bearish, client bullish. FII flows: about Rs 6,600 cr sold in index futures and about Rs 6,000 cr sold in cash. No max-pain figure is quoted anywhere (left null in keys). |
| Cross-check with data | His 22,600 decider is the ATM battle wall and highest combined-OI strike (129.4 lakh) in cluster 06, and his 22,400 break level is close to S2 22,451 and the straddle's lower breakeven 22,445 - the two-sided box the option market itself is pricing. |
8C. Crowd Sentiment — 4chan & Reddit (US + India)
| Venue | Tone |
|---|---|
| 4chan /biz/ + /wsg/ | /biz/ is fully engaged (six /smg/ generals at 119-380 replies) but the edition titles flipped in one day: yesterday's 'ATH edition' now sits next to a 'sell for your lives edition' after Wall Street's drop, with 'the stakes are high' and 'Macron vs Micron' alongside. Jumpy and bear-flavored, not panicked. Contrarian: Not at an extreme - the 'sell for your lives' posture coexists with intact /GME//BBBYQ cult threads and ATH nostalgia, i.e. chronic /biz/ bearishness rather than capitulation or euphoria. Neutral input. |
| Reddit US (WSB · stocks · investing) | WSB is two-sided (earnings-day nerves on single names vs still-flaunted winners); r/stocks is macro-analytic (why is the sell-off so weak with the 10Y above 5.3% and crude above $100?); r/investing runs AI-skeptic reads including Goldman's 'S&P 500 has disconnected'. Anxious but hedged - no capitulation, no euphoria. Themes: yields >5.3% plus crude >$100 macro squeeze · AI capex/AGI skepticism (Meta/MSFT trimming Anthropic reliance) · memory-chip earnings boom (Samsung, MU) · SpaceX $40bn Nvidia-chip debt deal |
| Reddit India (r/IndianStockMarket · r/IndiaInvestments) | r/IndianStockMarket is weary-frustrated after the RBI hike - 'Market gave us hope for exactly 24 hours', 'Fii's with indian market', 'How long' drawdown fatigue, plus broker/portfolio housekeeping posts. Frustration is building but not capitulatory; r/IndiaInvestments is mostly stale. Themes: RBI-hike disappointment / 'hope for 24 hours' · FII-selling resentment · drawdown fatigue · Zerodha platform chatter |
Verdict: Retail sentiment is not at an extreme - Indian retail is tired, US retail two-sided and macro-anxious; no contrarian flag. — Indian retail fatigue aligns with the persistent FII outflows and five-month-low rupee - a grind, not a blowoff; US retail is hedged and macro-questioning rather than euphoric. There is no one-sided crowd to fade.
9. Nifty Buddy's View (X/Twitter)
| Item | View |
|---|---|
| Bias | Bearish-leaning within his standing 04-Oct week band 22,700-21,850: the 22,700 'one way upside' trigger round-tripped (satisfied at the 06-Oct close, failed back below at 22,603.05), his hawkish RBI read preceded the selloff and his freshest market post was 'Markets coming to it's senses now... Falling from the top' (07-Oct 13:08 IST). |
| Weekly/monthly levels | 22,700-21,850 = his expected range for the week (04-Oct); 22,700 = the upside trigger / 'moment of truth' (now resistance again); 21,850 = the older downside target, still never tested (07-Oct low 22,546.30); 23,300 = the level that would flip him bullish (28-Sep, unretracted); Bank Nifty 55,200 resistance, 51,500 target. No 13-Oct or 27-Oct expiry level set was ever published. |
| Commentary | Two-for-two on macro this week: the 25bp hike he called landed, and his hawkish interpretation preceded the fall. No fresh level since 04-Oct, no monthly map, crude still direction-only, and his 06-Oct FII 'short covering / put writing' remark is now stale - the 07-Oct bhavcopy shows a short build-up instead. |
| Cross-check with data | His 22,700 round-tripped trigger sits within 1.6 pts of today's R1 22,698.4 and is the 86.1-lakh call-OI strike in cluster 06 - a three-way resistance confluence at 22,700-22,800 with the pivot, call wall and his band top. His 21,850 floor is far below S1 22,527 and the chain's put walls. |
10. Polymarket Prediction Market Signals
| Event | Probabilities | Trend | Vol 24h | Ends |
|---|---|---|---|---|
| 🏆 Largest company / NVIDIA | ||||
| 🗳️ US politics | ||||
| 🛢️ Oil | ||||
| 🌍 Geopolitics | ||||
| 🟠 Recession | ||||
| 🔵 Fed policy | ||||
| Fed Decision in October? | No change: 83.5% · 25 bps increase: 15.5% · 25 bps decrease: 0.45% · 50+ bps increase: 0.35% | No change ↑, 25 bps increase ↓, 25 bps decrease ↓, 50+ bps increase ↓ | $12,07,147 | 2026-10-29 |
| Fed Decision in December? | 25 bps increase: 74.5% · No change: 23.5% · 50+ bps increase: 2.95% · 25 bps decrease: 1.05% · 50+ bps decrease: 0.35% | 25 bps increase ↑, No change ↑, 50+ bps increase ↑, 25 bps decrease ↑, 50+ bps decrease ↓ | $61,200 | 2026-12-10 |
| Fed Decision in January? | No change: 64.5% · 25 bps increase: 31.5% · 25 bps decrease: 1.5% · 50+ bps increase: 1.5% · 50+ bps decrease: 0.75% | No change ↑, 25 bps increase ↓, 25 bps decrease ↓, 50+ bps increase ↓, 50+ bps decrease ↓ | $27,604 | 2027-01-28 |
| Another Fed rate hike in 2026? | Another Fed rate hike in 2026?: 77.5% | Another Fed rate hike in 2026? ↑ | $9,447 | 2026-12-10 |
| US recession by end of 2026? | US recession by end of 2026?: 6.5% | US recession by end of 2026? ↓ | $6,151 | 2026-12-31 |
| US recession by end of 2027? | US recession by end of 2027?: 33.5% | US recession by end of 2027? ↓ | — | 2027-12-31 |
| How high will US unemployment go in 2026? | 5.0%: 5.45% · 5.5%: 2.35% · 7.0%: 1.7% · 10.0%: 1.7% · 6.0%: 0.55% | 5.0% ↓, 5.5% ↓, 7.0% ↑, 10.0% ↑ | $151 | 2027-04-01 |
| 2026 World GDP Growth | ≤2.9%: 33.5% · 3.1%: 25.85% · 3.0%: 22.1% · 3.2%: 10.15% · 3.6%: 3.05% · 3.4%: 2% · 3.3%: 1.35% · 3.5%: 0.7% · 3.7%+: 0.25% | ≤2.9% ↑, 3.1% ↑, 3.0% ↑, 3.2% ↑, 3.6% ↓, 3.4% ↓, 3.7%+ ↓ | $246 | 2027-05-01 |
| US announces end of Iranian blockade by...? | March 31: 72.5% · December 31: 49.8% · November 30: 36% · October 31: 20.5% · October 15: 10.5% | March 31 ↓, November 30 ↓, October 31 ↓, October 15 ↓ | $6,78,840 | 2027-01-01 |
| US-Iran ceasefire continues through...? | October 5: 99.95% · October 7: 99.65% · October 9: 96.75% · October 12: 93% · October 15: 90.5% · October 31: 71.5% · November 15: 56.5% · November 30: 40.5% · December 31: 33.5% | October 7 ↑, October 9 ↑, October 12 ↑, October 15 ↑, October 31 ↑, November 15 ↑, November 30 ↓, December 31 ↓ | $4,73,815 | 2026-10-31 |
| Will the U.S. invade Iran before 2027? | Will the U.S. invade Iran before 2027?: 15.5% | Will the U.S. invade Iran before 2027? ↑ | $2,75,730 | 2027-01-01 |
| US-Iran Final Nuclear Deal by…? | December 31: 13.5% · November 30: 8.5% · October 31: 2.65% | December 31 ↑, November 30 ↓, October 31 ↑ | $72,610 | 2027-01-01 |
| What will WTI Crude Oil (WTI) hit in October 2026? | ↑ $90: 90% · ↓ $85: 69.5% · ↑ $95: 53.5% · ↓ $80: 37.5% · ↑ $100: 28.5% · ↓ $75: 17% · ↑ $105: 13.5% · ↑ $110: 6.5% · ↓ $70: 6.5% · ↑ $115: 3.55% | ↑ $90 ↓, ↓ $85 ↑, ↑ $95 ↓, ↓ $80 ↑, ↑ $100 ↓, ↓ $75 ↓, ↑ $105 ↓, ↑ $110 ↓, ↓ $70 ↓, ↑ $115 ↓ | $1,13,905 | 2026-11-01 |
| What will WTI Crude Oil (WTI) hit Week of October 5 2026? | ↑ $90: 87% · ↓ $85: 16% · ↓ $80: 11% · ↑ $95: 9.5% · ↓ $75: 3.15% · ↑ $120: 0.8% · ↑ $125: 0.75% · ↑ $110: 0.7% · ↑ $105: 0.7% · ↑ $100: 0.6% | ↑ $90 ↓, ↓ $85 ↓, ↓ $80 ↑, ↑ $95 ↓, ↓ $75 ↓, ↑ $125 ↓, ↑ $100 ↓ | $2,935 | 2026-10-09 |
| WTI Crude Oil (WTI) closes above ___ on October 8? | $85: 96.5% · $86: 92% · $87: 86.5% · $88: 74.5% · $89: 58.5% · $90: 40.5% · $91: 24.5% · $92: 12% · $93: 5.1% · $94: 4.5% | $85 ↓, $86 ↓, $87 ↓, $88 ↓, $89 ↓, $90 ↓, $91 ↓, $92 ↓, $93 ↓, $94 ↓ | $426 | 2026-10-08 |
| WTI Crude Oil (WTI) Up or Down on October 8? | WTI Crude Oil (WTI) Up or Down on October 8?: 59.5% | WTI Crude Oil (WTI) Up or Down on October 8? ↓ | $401 | 2026-10-08 |
| Balance of Power: 2026 Midterms | Democrats Sweep: 63.5% · R Senate, D House: 27.5% · Republicans Sweep: 8.5% · D Senate, R House: 0.85% | Democrats Sweep ↓, R Senate, D House ↓, Republicans Sweep ↑ | $10,33,830 | 2026-11-04 |
| Which party will win the House in 2026? | Democratic Party: 91.5% · Republican Party: 8.5% | Democratic Party ↓, Republican Party ↓ | $5,09,839 | 2026-11-04 |
| Which party will win the Senate in 2026? | Democratic Party: 63.5% · Republican Party: 35.5% | Democratic Party ↓, Republican Party ↓ | $47,402 | 2026-11-04 |
| Texas Senate Election Winner | James Talarico (D): 66.5% · Ken Paxton (R): 33.5% | James Talarico (D) ↑, Ken Paxton (R) ↓ | $1,12,282 | 2026-11-04 |
| Largest Company end of December 2026? | NVIDIA: 87.5% · Apple: 8.55% · Alphabet: 2.65% · Microsoft: 0.6% · SpaceX: 0.25% | NVIDIA ↓, Apple ↑, Alphabet ↓, SpaceX ↓ | $34,006 | 2027-01-01 |
| Largest Company end of October 2026? | NVIDIA: 95.6% · Apple: 3.7% · Alphabet: 0.4% | NVIDIA ↓, Alphabet ↓ | $3,444 | 2026-11-01 |
| 2nd Largest Company end of December 2026? | Apple: 72% · Alphabet: 15% · NVIDIA: 11.5% · Microsoft: 4.3% · SpaceX: 0.2% | Apple ↑, Alphabet ↑, NVIDIA ↑, SpaceX ↓ | $88 | 2027-01-01 |
| 2nd Largest Company end of October 2026? | Apple: 92.5% · Alphabet: 4.1% · NVIDIA: 3.4% · Tesla: 1.95% · Microsoft: 0.8% · SpaceX: 0.3% | Apple ↓, Tesla ↑, Microsoft ↓, SpaceX ↓ | $242 | 2026-11-01 |
Fed: The hawkish-Fed channel is fully priced but unforgiving: the Oct 28-29 FOMC is a hold near-certainty (No change 83.5%, +18pp w/w), December prices a 25bp hike at 74.5%, 'another hike in 2026' 77.5% and 'zero Fed cuts in 2026' 95.55%, with first-cut pricing pushed to mid-2027. A strong-dollar/FII-outflow headwind, not a growth scare (recession 6.5%).
Geopolitics: De-escalation drifts on the week (US-Iran ceasefire through Oct 15 at 90.5%, end-of-blockade by Dec 31 49.8%) but the crude supply tail stays fat: military action against the Saudi East-West pipeline is 40% by Oct 31 / 52.5% by Nov 30, and Saudi strikes on Yemen sit at 71-91%. Taiwan quiet (invade 2.3%).
US politics: Midterms lean Democratic (D sweep 63.5%, House-D 91.5%, Senate-D 63.5%; divided government 27.5%) - gridlock-lean, mildly positive for EM policy volatility. No live tariff/H-1B/India market with volume.
Overall signal: NEUTRAL
Fed: October 83.5% hold, December 74.5% hike, 2026 zero-cuts 95.55% - a duration/EM headwind, not a growth scare (recession 6.5%).
India: the October RBI market resolved to a 25bp hike and December follow-up repriced to 66.5% (+25.5pp d1) - the RBI is now a hiking central bank.
NVIDIA dominance end-December 87.5% (+8.0pp w/w, -1.0pp d/d); Apple 8.55% - the AI-bubble deflation trigger is NOT fired.
Oil: WTI $100-in-October 28.5% (-10pp w/w) and $105 -9.5pp - a lower ceiling but the spike tail persists; today's close-above ladder puts spot in the high-$80s.
Bitcoin slid to the $82,000-84,000 band (61.5%, +45pp d1) - the one clear de-risking tick; SPX-hits-8000-by-Dec rebuilt to 63.5% (+24pp w/w).
11. Trump Posts & Comments — Real-Time Policy Signal 🟢 LOW
| Time (IST) | Platform | Topic | Content | Impact |
|---|---|---|---|---|
| 2026-10-07 ~08:00 | Truth Social | legal/politics | Link repost of a USA Journal report on Jack Smith surveillance of Trump staff - legal score-settling, no market content. | ⚪ |
| 2026-10-08 ~05:35 | proclamation | energy (ceremonial) | 'National Energy Dominance Month, 2026' - 'America's abundant energy resources are the backbone of our booming economy'. | ⚪ |
Tone: Domestically combative midterm-campaign mode (endorsements, media attacks, personnel/legal noise) but quiet on economics - zero tariff/Fed/China/dollar/oil/H-1B/India posts in the last 24h. · Theme: campaign politics plus personnel/legal noise; no fresh economic escalation - the standing overhangs are the weekend 150-300% tariff threat and the stalled India-US trade deal (talks at a 'plateau', deal 'not imminent'). · Alert: LOW
Quiet on the market-relevant axes for NIFTY. Cross-ref: Nothing overnight reprices India directly. The live India tail remains the stalled BTA; the market-adjacent activity was US-domestic energy politics and ceremonies.
12. 🤖 AI Bubble & Systemic Risk Dashboard
Composite: ELEVATED — 4/7 flags (classic: 3/11, AI: 1/11)
Classic bubble & recession indicators
| # | Indicator | Value | Flag |
|---|---|---|---|
| 1 | 10Y-2Y spread | 0.51 pp | 🟢 |
| 2 | 10Y-3M spread | 1.06 pp | 🟢 |
| 3 | NY Fed recession prob | 13.88% | 🟢 |
| 4 | Sahm Rule | 0.00 | 🟢 |
| 5 | HY OAS | 303 bps | 🟢 |
| 6 | IG OAS | 83 bps | 🟢 |
| 7 | VIX term structure | contango | 🟢 |
| 8 | Shiller CAPE | 41.80 | 🔴 FLAG |
| 9 | Buffett indicator | 244% | 🔴 FLAG |
| 10 | Margin debt YoY | +37.2% | 🔴 FLAG |
| 11 | TED spread | discontinued | 🟢 |
AI-specific indicators
| # | Indicator | Value | Flag |
|---|---|---|---|
| 1 | NVIDIA P/E >60 with decelerating growth | 30.01 TTM / 19.62 forward (S&P Global Market Intelligence via stockanalysis.com, 'Last updated: Oct 7, 2026'; $237.47 / EPS $7.91 TTM). PEG 0.39, PS 18.92, fwd PS 10.67, PB 25.03, market cap $5.73T. Revenue $302.97B TTM, net income $192.88B, GM 74.67%, profit margin 63.66%, ROE 117.21%. Consensus Strong Buy, 61 analysts, avg PT $328.72 (+38.43%); revenue growth forecast (3Y) 61.12%, EPS growth forecast (3Y) 64.78%. Short interest 1.22% of shares out; next earnings 18-Nov-2026. vs the 06-Oct read (30.21 TTM / 19.75 fwd): -0.20 TTM / -0.13 fwd. Trigger = P/E >60 with decelerating growth: 29.99 pts short of the line | 🟢 |
| 2 | NVDA below 50/200-DMA | $237.47 (07-Oct close, -0.74%, -$1.77 vs 239.24; after-hours $237.70 +0.10%): +8.05% above the 50-DMA $219.77 and +17.94% above the 200-DMA $201.36. Cross-checks data/collection/2026-10-08/03-keys.json nvda (price 237.47, dma50 219.77, dma200 201.36, below_200dma false) exactly; stockanalysis SMAs (220.58/201.68, +7.66%/+17.75%) agree in direction. RSI 64.31; +27.99% 52w; 20-day avg volume 108.4M. First down close after Tuesday's fresh 52-week record run; no >5% single-session move. Trigger = below 50/200-DMA or a >5% single-session drop: neither close | 🟢 |
| 3 | Mag-7 >35% of S&P 500 | 34.9% (historyofmarket.com /api/mag7/concentration.json, live, latest.date 2026-10-07; SPY-holdings sum; also listed as the series peak). +0.2pp d/d vs 34.7% (2026-10-06). Top-10 share of the S&P 500 = 40.41%, top-3 = 20.52%, top-1 = 8.12% (same vendor, topShares.asOf 2026-10-07; names NVDA AAPL GOOGL MSFT AMZN META AVGO TSLA MU BRK.B). Press counterpoint datapoint: NVDA+AAPL+MSFT >21% of the S&P (Creative Planning via Benzinga/Yahoo 07-Oct). CLOSEST METRIC TO ITS LINE: 0.1pp below the 35% 'extreme concentration' trigger (0.3pp yesterday); the top-10 metric already exceeds the spec's 40% 'unprecedented' line | 🟢 |
| 4 | Hyperscaler capex cuts | NONE. REUSE per spec (no earnings/guidance event; tracker stamped 'Updated 06 Oct 2026'; guidance from the July 22-30 Q2 reports). Big-4 2026 capex guidance $720B-$745B, midpoint ~$732.5B (YieldTheory): MSFT ~$175B (H1 $72.9B), GOOGL $195-205B (H1 $80.6B), AMZN ~$220B (H1 $98.4B), META $130-145B (H1 $50.92B). 7 raises / 0 cuts; all four must spend ~12%-51% more per quarter in H2 than Q2. New debt-layer context (Benzinga 07-Oct): Dimon estimates hyperscaler spend ~$700B this year rising to ~$1T next year; Goldman sees top-5 hyperscalers issuing ~$250B bonds in 2026 and ~$400B in 2027; AMZN/MSFT/GOOGL/META/ORCL issued ~$200B IG debt in H1-2026, ~2x all of 2025 (iShares). capex/rev% not disclosed -> null. Next refresh after Q3 reports late Oct 2026 | 🟢 |
| 5 | GPU cloud rental >20% decline in 3 months | GPU Economy Cloud GPU Price Index (CC BY 4.0): H100 SXM $3.49/GPU-hr, week of Oct 5-11 2026 (provisional; read 2026-10-08 00:41 UTC; median of 31 quotes / 29 providers). Weekly series W37 $3.92 -> W38 $3.90 -> W39 $3.70 -> W40 $3.49 (final) -> W41 $3.49: w/w flat ($3.49 -> $3.49), -11.0% over the 4 published weeks (series starts 2026-09-07), but the vendor's like-for-like base-100 index ROSE 76.4 (end-Aug) -> 78.4 (W40) = +2.6% - the $-median drop is partly panel change, not rate-card cuts. Listed H100 rates sit 22% below Jan-2025 like-for-like (a gradual 20-month slide, not a 3-month collapse). Spot median -50% vs on-demand; hyperscaler median $9.90 vs specialist $3.20 (+209%). Silicon Data transacted index ~$2.53/GPU-hr mid-2026 (coloprice; from ~$8 in 2024). GPUniq /statistics page removed (homepage cards verbatim: H200 $2.19/h, RTX PRO 6000 $0.97/h, RTX 5090 $0.34/h, 7-day average). Trigger = sustained >20% decline over 3 months: NOT met | 🟢 |
| 6 | SOX below 200-DMA / underperforming S&P 4W >5% | CLEARED: SOX 13,066.15 (07-Oct, -1.15% d/d - 2.7x the S&P's loss; 5 sessions 12,628.62 -> +3.46%), +8.91% above its 50-DMA 11,997.25 and +25.30% above its 200-DMA 10,428.20 (computed in-page over 1y daily). SPX 7,801.77 (-0.22%; +1.96% 5 sessions). 4-week (vs 08-Sep): SOX +9.91% vs SPX +1.67% = +8.24pp relative (from +9.29pp). Semis still lead on both counts, but SOX led the downside on the day. Trigger = SOX below 200-DMA AND underperforming S&P >5% over 4 weeks: neither | 🟢 |
| 7 | AI VC funding down >40% QoQ | no contraction signal. REUSE: September 2026 $97.9B across 825 AI rounds (agenccy.ai tracker); largest ByteDance $29.6B debt, SoftBank $11.1B, Zhipu $5B. Context: Anthropic's $65B Series H at a $965B post-money valuation (May-2026) tops OpenAI's $852B - the valuation Burry's 06-Oct note calls out. Nowhere near the -40% QoQ trigger | 🟢 |
| 8 | AI ETF outflows >$500M/wk x4 | ARKK only: -$876.9M weekly outflow (week to 02-Oct-2026; shares 105.7M -> 95.8M, -9.4%; ETF Channel, 02-Oct) - carried unchanged, no fresher weekly print exists yet. BOTZ and AIQ weekly flows NOT obtainable -> null for those funds. One ARKK week only and no usable BOTZ/AIQ series, so the >$500M/wk x4 trigger can be neither fired nor counted (partial data) | 🟢 |
| 9 | 'AI' earnings-call mentions declining 2+ quarters | UNCHANGED / REUSE. Q2 2026 = 331 of 493 S&P 500 calls mentioned AI = 67% (FactSet; window 15-Jun to 14-Sep). No Q3-2026 print yet (season starts mid-Oct). First decline after three quarters of expansion (Q1 337 -> Q2 331); 5-yr avg 178. Threshold is 2+ consecutive quarters, so one quarter is not a flag | 🟢 |
| 10 | AI-deflation narrative mainstream | BEARISH narrative vs a just-slightly-down tape; FIRING and escalated this window. FRESH: (a) Burry's new essay posted 08-Oct 00:05 UTC (05:35 IST, ~2h before collection) - 'Short Thoughts: The AI Cloud Oligopoly, Stages of Grief & a Flashing Bear Market Indicator': 'the tech giants, but for Apple, are spending as if their lives depended on it when their lives clearly do not'; 'the expectation the government will tolerate their oligopoly on AI'; 'all this spending does not have a defined goal or economic end-point'; 'Data Center Financing at Risk... creaks and groans - and some loud snapping and crackling... valuation marks in the private equity and private credit arenas'; 'long-term rates are rising before the timelines have a chance to play out at all'. (b) Burry press-quoted (Benzinga 07-Oct): market 'quite obviously in its first stage of grief, denial'...'per 2000 and 2008, this stage lasts 6-9 months'. (c) Dalio 07-Oct (Forbes Global CEO Conference, Singapore, via Bloomberg/Benzinga): AI a 'classic bubble', 'We're in the part of the cycle that is before that but approaching that... I think we're close to that' - debt + rising rates the pop point. (d) Semafor 07-Oct: investors (Dalio, Temasek CIO) warn of AI bubble at record highs. Counter: istheaibubbleover.com tracker (updated 07-Oct) counts 0/4 signals hit; S&P/Nasdaq only -0.2% on the day | 🔴 FLAG |
| 11 | NVDA dominance falling >10%/wk or Apple #1 (Polymarket) | Dec-2026 market: NVIDIA 87.5%, Apple 8.55% (data/collection/2026-10-08/13-keys.json nvidia_dominance; trend 'down' on the 1-day basis: -1.0pp d/d, but +8.0pp on the week - trend_basis 1-day price change). vs the 07-Oct collection (88.5%): -1.0pp d/d; vs 06-Oct (85.0%): +2.5pp; vs 05-Oct (84.5%): +3.0pp. NO TRIGGER: the weekly change is POSITIVE (+8.0pp); a >10pp weekly fall or an Apple flip is far away | 🟢 |
Hyperscaler AI capex
| Company | Capex | Capex/Rev | YoY | Guidance |
|---|---|---|---|---|
| Microsoft | ~$175B 2026 guidance (calendar year); H1 spend $72.9B (Q1 $31.9B + Q2 $41.0B); needs ~$51B/qtr in H2 | H2 step-up ~+24.5% per quarter vs Q2 $41.0B | UNCHANGED build; calendar-2026 reads ~$175B (from ~$190B) on a finance->operating-lease reclass, not less building. Guidance as of the July 22-30 Q2 report; tracker updated 06-Oct-2026 | |
| Google/Alphabet | $195B-$205B 2026 guidance (mid $200B); H1 spend $80.6B (Q1 $35.7B + Q2 $44.9B); needs $57.2B-$62.2B/qtr in H2 | H2 step-up ~+27.4% to +38.5% per quarter vs Q2 $44.9B | UNCHANGED this run - guidance from the July Q2 report; raised twice during 2026 | |
| Amazon | ~$220B 2026 guidance (companywide: AI, AWS, chips, robotics, fulfillment, satellites); H1 spend $98.4B (Q1 $44.2B + Q2 $54.2B); needs ~$60.8B/qtr in H2 | H2 step-up ~+12.2% per quarter vs Q2 $54.2B | UNCHANGED this run - guidance from the July Q2 report | |
| Meta | $130B-$145B 2026 guidance (mid $137.5B); H1 spend $50.92B (Q1 $19.84B + Q2 $31.08B); needs $39.5B-$47.0B/qtr in H2 | H2 step-up ~+27.2% to +51.3% per quarter vs Q2 $31.08B | UNCHANGED this run - guidance from the July Q2 report; floor previously raised from $125B to $130B | |
| Big-4 combined (MSFT+GOOGL+AMZN+META) | $720B-$745B 2026 guidance, midpoint ~$732.5B | no cuts; all four must spend ~12%-51% more per quarter in H2 than in Q2 | 7 raises / 0 cuts. No hyperscaler cut or changed guidance in this window. Guidance as of the July 22-30 Q2 reports; next refresh after Q3 reports late Oct 2026. Debt layer (Benzinga 07-Oct): Dimon sees hyperscaler spend ~$700B -> ~$1T next year; Goldman: ~$250B top-5 hyperscaler bonds 2026, ~$400B 2027; ~$200B IG debt issued H1-2026 (~2x all of 2025, iShares). Adding Oracle's FY27 guidance (~$90B-$95B) lifts the tracked total to ~$835B (TMT Finance analysis). ROI caveat: none of the four reports an audited AI-capex line, so the 'spend without revenue proof' risk is unresolved |
NVIDIA tell: UNFIRED, but the tape blinked for the first time in a week. NVDA closed 07-Oct at $237.47 (-0.74%, -$1.77 vs 239.24) - its first down close after Tuesday's fresh 52-week record - and held after-hours at $237.70 (+0.10%). It remains +8.05% above its 50-DMA $219.77 and +17.94% above its 200-DMA $201.36 on a 30.01 TTM / 19.62 forward P/E (03-keys cross-checked exactly; stockanalysis/S&P Global SMAs 220.58/201.68 agree in direction). No price trigger is close: no >5% single-session drop, no DMA breach. The crowd agrees - Polymarket prices NVIDIA 87.5% for end-Dec-2026 dominance (Apple 8.55%): -1.0pp on the day but +8.0pp on the week, the opposite of the >10pp weekly collapse that would fire the deflation trigger. What did move is the AI-complex periphery on the same session: META -2.38%, SOX -1.15% (vs SPX -0.22%), BTC -2.62%. The live NVIDIA-relevant stress remains positioning/narrative: Burry's 28-Sep NVIDIA-short roll into Sep-2027 puts, his 01-Oct GPU-depreciation critique, the 06-Oct 'bubble private company valuation' note, and the 08-Oct oligopoly essay naming hyperscaler debt-financing risk.
Cross-asset divergence signals
| Signal | Observation | Danger? | Notes |
|---|---|---|---|
| NASDAQ vs Dow | Nasdaq 27,538.69 (-0.22% d/d; +4.23% over 4 weeks from 26,421.41 on 08-Sep; +4.06% above its 50-DMA 26,463.09) vs Dow 51,179.87 (-0.66% d/d; -3.04% over 4 weeks from 52,786.07; -2.80% below its 50-DMA 52,651.85). 4-week tech-over-value spread +7.27pp (widened from +6.86pp). | watch | the 'tech at highs / Dow falling' divergence is now 4+ weeks old in direction, though yesterday's joint down day partially masks the dot-com signature; spread still widening. |
| S&P 500 vs equal-weight (SPY vs RSP) | SPY 777.22 (-0.24% d/d; +1.47% 4w; +1.66% above 50-DMA 765.95) vs RSP 210.60 (-0.82% d/d - triple the index's loss; -2.83% 4w; -2.69% below 50-DMA 216.42). 4-week cap-weight premium +4.30pp (from +3.74pp). | watch | narrow leadership: the average stock is falling faster than the index; still far short of the spec's >10%/6-month trigger. |
| US Dollar vs EM | DXY 102.241 (08-Oct live; 03-keys), USD/INR 96.658 (08-Oct live). FIIs have now sold Indian cash for 9 straight sessions with index-futures net-short (L/S 0.10). | no | DXY below the spec's >105 line; the flow pattern (FII selling into a firm-ish dollar, absorbed by DIIs) remains the standing EM/India headwind - captured as YES under FII/DII. |
| Bitcoin vs NVIDIA | BTC $83,316.34 (08-Oct live; -2.62% vs the last valid daily close 85,557.56 (06-Oct; the 07-Oct bar close is null on Yahoo); -1.4% over 5 sessions) vs NVDA -0.74% d/d. | no | no joint >5% week yet - but both fell on the same final session with BTC at ~3.5x NVDA's magnitude; speculative froth cracking at the edges. |
| Gold vs equities ratio | Gold $4,132.50 (07-Oct settlement, -0.20%; 03-keys) while the S&P slipped only -0.22%. | no | the hedge bid cooled along with the tape; no sustained safe-haven divergence (>2 weeks with equities flat). |
| Bonds vs equities (credit) | HY OAS 303 bps (obs 2026-10-06, fresh 01-keys), IG OAS 83 bps; VIX 15.08 (07-Oct, +0.47%), term structure contango (vix3m 17.72, vix9d 11.78). | no | credit tight and equities only just off records = 'everything rally' froth signature, NOT the both-falling liquidity-crisis regime; but rising long rates (Dalio, Burry both flag it) is the named 2026 transmission mechanism. |
| FII vs DII flows (India) | 07-Oct: FII net -Rs 6,121.37 cr (buy Rs 12,578 cr / sell Rs 18,699 cr); DII net +Rs 4,596.57 cr (buy Rs 18,707 cr / sell Rs 14,110 cr); FIIs net sellers 9 sessions straight; last five sessions sum -Rs 33,413 cr (computed: -6,121.37, -2,961, -4,699, -9,484, -10,148); FII index-futures long-short 0.10 (net short); Nifty -0.76% - flow and price ALIGNED (both down) after two diverged sessions. (fnoscan.com, NSE+BSE provisional, as of 7 Oct.) | YES | the spec's external-stress pattern persists at scale: FIIs selling at >Rs 33,000 cr per 5 sessions absorbed by DIIs; watch for DII capitulation as the real-crash tell. |
AI narrative health check
| Dimension | Status | Evidence |
|---|---|---|
| AI-internals / price | GREEN intact, first crack | NVDA $237.47 (-0.74%, first down close after Tuesday's fresh 52-week record), still above both DMAs (+8.05% / +17.94%); after-hours +0.10%; RSI 64.31; Polymarket dominance 87.5% (-1.0pp d/d, +8.0pp w/w). Periphery cracked harder: META -2.38%, SOX -1.15%, BTC -2.62%. |
| Magnificent-7 concentration | AMBER 0.1pp from the trigger | 34.9% of the S&P 500 (2026-10-07 live reading, +0.2pp d/d, series peak); only 0.1pp below the spec's 35% 'extreme' line (0.3pp yesterday); top-10 share 40.41% already above the 40% 'unprecedented' line; top-10 names NVDA AAPL GOOGL MSFT AMZN META AVGO TSLA MU BRK.B. |
| fundamentals at the frontier | GREEN accelerating | NVDA revenue $302.97B TTM, net income $192.88B, EPS $7.91, GM 74.67%, ROE 117.21%; 52w price +27.99%; market cap $5.73T; next earnings 18-Nov-2026. |
| analyst consensus | GREEN bullish, no downgrades | Strong Buy (61 analysts), avg PT $328.72 (+38.43%); revenue growth forecast (3Y) 61.12%, EPS (3Y) 64.78%. |
| hyperscaler capex / ROI + funding | AMBER accelerating, ROI unproven, debt layer explicit | Big-4 2026 guidance $720B-$745B, 0 cuts, 7 raises (REUSE); Dimon: ~$700B -> ~$1T next year; Goldman: ~$250B hyperscaler bonds 2026, ~$400B 2027; ~$200B IG debt issued H1-2026 (~2x all of 2025, iShares); Burry 08-Oct: PE/private-credit marks 'creaking' as the transmission channel; capex_rev_pct null. |
| GPU rental market | GREEN like-for-like; $-median drifting down | GPU Economy H100 SXM $3.49/hr (W41 provisional): w/w flat; like-for-like base-100 index +2.6% (76.4 end-Aug -> 78.4 W40); $-median -11.0% over 4 published weeks partly on panel change; 22% below Jan-2025 like-for-like (gradual 20-month slide); spot median -50% vs on-demand; GPUniq statistics page discontinued. |
| semis vs market | GREEN leading, led the downside | SOX 13,066.15: +25.30% above its 200-DMA; +8.24pp over the S&P on 4 weeks; but -1.15% on 07-Oct vs SPX -0.22% - semis took the most heat on the risk-off day. |
| AI VC funding / IPO window | GREEN open | Sept AI funding $97.9B across 825 rounds (REUSE); Anthropic's $965B private valuation tops OpenAI's $852B; no AI IPO cancellation/delay in this window. |
| AI-labour | AMBER deteriorating structurally | FRESH: HubSpot ~660 cuts (~7% of workforce) in an AI-driven 'customer outcomes' restructuring - board authorized 01-Oct, announced 06-Oct, charges $65-75M, complete by Q1-2027 (Quartz via Yahoo; CEO denies AI-efficiency driver per Boston Globe). Carried: Challenger September - tech cuts 10,799 (+77% m/m), AI the YTD #1 reason (120,136, ~21%); Oracle 21,000 (~13%); Microsoft ~500; Disney ~300. |
| media / narrative | RED deflation frame now carries a marquee manager | Burry 08-Oct oligopoly essay (dedicated, hours before collection) + 'stage of grief, denial... lasts 6-9 months' press quote; Dalio 07-Oct 'classic bubble... I think we're close to that'; Semafor 07-Oct investor warnings at record highs. Counter: istheaibubbleover tracker 0/4; indices -0.2% on the day; analyst PTs unchanged. |
| regulatory | NEUTRAL no event found | No fresh material AI regulatory/antitrust headline in this collection window (Burry's 'government will tolerate their oligopoly' line is commentary, not an event). |
| Burry / Cassandra signal | RED CRITICAL | New dedicated essay 08-Oct 00:05 UTC (05:35 IST) - 'Short Thoughts: The AI Cloud Oligopoly, Stages of Grief & a Flashing Bear Market Indicator' - with extensive free-portion quotes naming oligopoly-rent expectations, unknowable endpoints, sunk cost, and PE/private-credit financing risk; plus press-carried 'stage of grief' quote. Caveats: Scion deregistered (no refreshable 13F); typically 6-18 months early. |
Michael Burry / Cassandra signal: CRITICAL — NEW POST this window: 'Short Thoughts: The AI Cloud Oligopoly, Stages of Grief & a Flashing Bear Market Indicator' posted 2026-10-08T00:05:38Z (05:35 IST, ~2h before this collection; his 00:07 UTC note links it: 'New expansive Short Thoughts post! Enjoy!'). Subtitle: 'Other Peoples' Money, Market Breadth & Market Structure, The Difference This Time'. Free-portion verbatim: 'I have recently considered that the tech giants, but for Apple, are spending as if their lives depended on it when their lives clearly do not.' ... 'Monopolies almost by definition need not spend wildly as if their lives depended on it.' ... 'they collectively have the expectation the government will tolerate their oligopoly on AI. Nay, will tolerate and fear it.' ... 'Why are OpenAI and Anthropic and Oracle also spending so much? Surely they are not monopolies?!? No, but they intend to be part of the oligopoly.' ... 'even Larry Ellison was seduced to bet his company on it' ... 'other than the grab for market power, all this spending does not have a defined goal or economic end-point. As such, the consequences are likely unknowable to all.' ... 'Ultimately, compression will do its deed, and much of what is being spent will be just so much sunk cost.' ... 'Data Center Financing at Risk - Meanwhile, I am hearing of creaks and groans - and some loud snapping and crackling. I speak of valuation marks in the private equity and private credit arenas. We've moved shadow banking offshore and reinvented the role of insurance companies. These noises are so loud that I can hear them way out here.' ... 'growing leverage in the buildout of AI data centers, which fundamentally conflicts with financing timelines' ... 'People say this time is different. This is how it is different. Not a good thing. Not to mention, long-term rates are rising before the timelines have a chance to play out at all.' ... 'why is the bull run to new highs so well-affirmed, well-accepted, and well-projected?' (teases a Part VI slide; remainder paid). PRESS-CARRIED QUOTE (Benzinga 07-Oct): the market is 'quite obviously in its first stage of grief, denial', and 'per 2000 and 2008, this stage lasts 6-9 months.' CARRIED: 06-Oct note (Anthropic's $965B buys 78 profitable S&P 500 companies - 'the bubble private company valuation'); 05-Oct Trading Post (tax-loss season; LULU->DECK wash-sale proxy swap per press); 01-Oct GPU-depreciation critique; 28-Sep NVIDIA short rolled into Sep-2027 puts (plus MU/NBIS/PLTR/SOXX/NDX/ORCL/CAT put rolls, CoreWeave covered). Posted about AI/bubbles in the last 30 days: YES - three essays + notes in 10 days, the latest hours before this collection. Scion 13F: not refreshable (deregistered Nov-2025; last verified 13F = quarter ended 2025-09-30). Caveat: typically 6-18 months early - a bubble-risk input to the composite, NOT a NIFTY directional/timing call.
Composite 4/7 flags, ELEVATED: three classic valuation/leverage flags (CAPE 41.80, Buffett 244%, margin debt +37.2% y/y) plus the AI-deflation narrative. No AI-internal price flag fired: P/E 30.01 (not >60), NVDA above both DMAs, zero hyperscaler capex cuts, GPU like-for-like rental index rising, SOX +8.24pp over the S&P on 4 weeks, VC funding open. Mag-7 concentration hit 34.9% of the S&P (07-Oct, +0.2pp d/d) - now just 0.1pp below the 35% 'extreme concentration' line, with top-10 at 40.41% already past 40%. The deflation narrative escalated materially: Burry posted a new essay ~2h before collection ('The AI Cloud Oligopoly, Stages of Grief & a Flashing Bear Market Indicator') and Dalio called AI a 'classic bubble' near its popping point.
Narrative: The story has not shifted at the index level - AI internals stay intact and the crowd pushed NVIDIA dominance UP 8pp on the week - but the bubble conversation hardened from 'Burry re-engaged' to 'Burry dedicated essay plus a sitting mega-manager (Dalio) plus a press chorus', while concentration closes in on its extreme line from below. The next real test is the late-October Q3 capex reports; nothing today is a trigger.
13. Domestic Mutual Fund Flows — DII Liquidity Backdrop DATA MONTH: 2026-08
| Category | Net Flow (₹ Cr) | MoM |
|---|---|---|
| Equity (open-ended schemes) | ₹29,329 | 18.75 |
| Debt (open-ended schemes) | ₹-8,127 | -104.33 |
| Hybrid (open-ended schemes) | ₹10,045 | -12.58 |
| Index Funds (total) | ₹787 | -48.75 |
| ETFs (total) | ₹10,161 | — |
| Solution Oriented Schemes | ₹335 | — |
| Life Cycle Funds | ₹8 | — |
| Close-ended Schemes | ₹-1,112 | -60.6 |
| Interval Schemes | ₹-0 | — |
| Industry Grand Total (net inflow) | ₹41,354 | -82.47 |
| Small Cap Fund | ₹7,973 | 2.65 |
| Mid Cap Fund | ₹6,989 | 12.87 |
| Flexi Cap Fund | ₹5,059 | 7.44 |
| Large & Mid Cap Fund | ₹3,873 | 13.06 |
| Multi Cap Fund | ₹3,733 | 15.66 |
| Thematic Fund | ₹1,766 | — |
| Contra Fund | ₹1,328 | — |
| Focused Fund | ₹995 | 54.9 |
| Value Fund | ₹24 | — |
| Sectoral Fund | ₹-53 | — |
| Dividend Yield Fund | ₹-134 | 21.04 |
| Large Cap Fund | ₹-1,147 | — |
| ELSS | ₹-1,078 | -12.43 |
| Liquid Fund | ₹19,934 | -83.26 |
| Overnight Fund | ₹-30,654 | -175.85 |
| Money Market Fund | ₹11,735 | -44.59 |
| Ultra Short Term Fund | ₹4,257 | -47.05 |
| Floating Interest Rates Fund | ₹182 | 145.99 |
| Credit Risk Fund | ₹-23 | -115.97 |
| Banking & PSU Debt Fund | ₹-1,288 | -184.64 |
| Gilt Fund | ₹-1,824 | -786.37 |
| Corporate Bond Fund | ₹-3,190 | -306.55 |
| Arbitrage Fund | ₹3,789 | -41.73 |
| Multi Asset Allocation Fund | ₹3,671 | -2.2 |
| Balanced Hybrid Fund | ₹1,836 | — |
| Aggressive Hybrid Fund | ₹1,323 | — |
| Balanced Advantage Fund / Dynamic Asset Allocation | ₹-228 | 9.65 |
| Equity Savings Fund | ₹-246 | 48.44 |
| Conservative Hybrid Fund | ₹-99 | -347.15 |
| Equity ETFs | ₹7,237 | — |
| Gold ETFs | ₹2,597 | 66.59 |
| Silver ETFs | ₹1,271 | — |
| Debt ETFs | ₹-945 | — |
| Index Funds - Equity | ₹2,393 | — |
| Index Funds - Debt | ₹-1,610 | — |
| Fund of Funds investing overseas | ₹-72 | 20.13 |
| SIF (Specialised Investment Funds) | ₹7,699 | — |
SIP inflows: ₹32,297 Cr
Trend: August-2026 vintage (the freshest AMFI print; September is due ~10-Oct, unchanged from yesterday's read): equity inflows +Rs 29,328.62 cr (+18.75% MoM) into a falling market and a record SIP book of Rs 32,297 cr, but the composition stays defensive - small cap +7,973 cr and mid cap +6,989 cr lead, while large-cap (-1,147 cr) and ELSS (-1,078 cr) bleed and the debt book flipped to a -8,127 cr outflow. Money is buying risk selectively, not underwriting the large-cap complex.
FII/DII absorption: The domestic bid is real but fading at the margin: DIIs covered 75.1% of Wednesday's FII selling (Rs 4,597 cr vs Rs 6,121 cr), down from the prior session's more-than-full offset, while the record SIP line alone exceeds the month's net equity inflow. With large-cap and ELSS outflows, domestics are not the marginal buyer of index heavyweights - the mechanism by which DIIs can absorb everything and the Nifty still struggle.
NIFTY impact: The absorption thesis holds arithmetically while weakening at the margin; the September AMFI print (~10-Oct) is the next checkpoint - a second consecutive deceleration alongside the FII selling streak would break the cushion narrative.
14. MCX Crude Oil Options — India-Denominated Crude Signal nearest expiry 2026-10-15
| Metric | Value | |||
|---|---|---|---|---|
| MCX Crudeoil futures | 8562 | |||
| ATM strike | 8550 · IV — | |||
| Highest Call OI (crude resistance) |
| |||
| Highest Put OI (crude support) |
| |||
| PCR | 0.6179 | |||
| Max pain | 8650 |
OI buildup: MCX CRUDEOIL's nearest contract (15-Oct) closed soft at Rs 8,562 (-66, -0.76%) and the option book flipped decisively call-heavy: PCR collapsed to 0.6179 from ~1.05, with call writing at 8,700 (+4,468 lots, +97.9%) and the 9,000 wall at 14,439 lots (+5,600), while put positions were covered at 8,500 (-3,568, -26.1%, 'Put Long Covering') and 8,000 (-1,236). Max pain recomputed at 8,650 (source published none), against walls at 9,000 resistance / 8,500 support.
IV read: ATM (8,550) call Rs 265 / put Rs 250 (straddle Rs 515); ATM IV is null - the niftytrader per-strike IV fields read 0 and the live IV endpoint requires an API key. The expected-range widget prints Rs 8,148.71-8,975.29.
Cross-checks: The rupee-crude book sits ~5% below the 9,000 call wall in a flat max-pain zone around 8,650, while USD crude (WTI $89, Brent $101) is the driver; Polymarket's WTI ladder cut its $100 leg 10pp on the week. The put-covering-plus-call-writing combination says Indian traders see crude capped, not spiking.
NIFTY impact: For NIFTY's import bill this reads as neutral-to-mildly-supportive rather than a repositioned base case: the market's rupee-crude expectation is a capped-to-lower book even as Brent holds above $100, so the crude channel is a persistent level headwind rather than a fresh shock.
15. 🏛️ Policy Watch — Government & Regulatory Changes by Sector 🟢 LOW
A quiet policy day: RBI's SA-CCR and CVA capital-framework directions (both effective 01-Apr-2027) and three 07-Oct SEBI debt-market circulars lead, with the proposed US H-1B Visa Fraud Crackdown Act the one IT-relevant item - no HIGH-severity change and no fresh tariff/duty move.
New in the last 72h — 8 items
Carried from earlier runs — still pending
| Policy / notification | Sector | Status | Age | Severity | Issuer |
|---|---|---|---|---|---|
| Corporate Laws (Amendment) Bill, 2026 pending before Parliament | Financial Services | 📝 Proposed | 28d old | 🟢 LOW | Corporate Affairs (MCA) |
| Taxation and Other Laws (Amendment) Bill, 2026 passed by Parliament | All sectors | ⚡ In force | 24d old | 🟡 MED | Finance |
| CBIC revises central excise duties on exported petroleum via Notifications 49, 50, 51/2026-Central Excise — export petrol special additional duty cut to Rs 0.50/litre, HSD to Rs 20/litre, ATF to Rs 15/litre, road cess on exported HSD to nil | Oil & Gas | ⚡ In force | 23d old | 🟡 MED | Finance (CBIC) |
| Anti-dumping duty on calcined gypsum powder from Iran, Oman, Saudi Arabia and UAE extended to 16 March 2027 | Cement | ⚡ In force | 23d old | 🟢 LOW | Finance (CBIC) |
| DGFT Notification 36/2026-27 exempts export consignments up to Rs 3 lakh FOB from RCMC / Certificate of Registration, effective immediately | Exports | ⚡ In force | 23d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Trade Notice 27/2026-27 proposes comprehensive Non-Preferential Rules of Origin for imports and exports; comments open 15 days | Exports | 📝 Proposed | 23d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Trade Notice 28/2026-27 cuts Pre-Shipment Inspection Certificate issuance to a two-day window from inspection | Exports | ⚡ In force | 23d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT extends deadline to surrender unutilised raw sugar TRQ allocation (10 lakh tonnes) to 30 September 2026 | Sugar | ⚡ In force | 23d old | 🟢 LOW | Commerce & Industry (DGFT) |
| SEBI consultation paper on BCP and disaster recovery for market infrastructure institutions — shorter non-working-day DR drills, tighter primary-data-centre norms | Financial Services | 📝 Proposed | 23d old | 🟢 LOW | SEBI |
| CBIC Notification 75/2026-Customs (N.T.) revises tariff values for palm oils, gold, silver, brass scrap and areca nuts effective 16 Sep 2026 | Metals | ⚡ In force | 22d old | 🟢 LOW | Finance (CBIC) |
| SEBI extends the Samuhik Prativedan Manch common reporting platform to clearing members who are also stock brokers — 14 compliance reports from 30 Sep 2026, phase 2 on 31 Dec 2026 | Financial Services | ⚡ In force | 21d old | 🟢 LOW | SEBI |
| Draft National Electricity Policy 2026 sent to Cabinet — annual tariff resets, discom financial turnaround, end to discom monopolies, renewable integration and storage | Power | 📝 Proposed | 20d old | 🟡 MED | Power & Energy |
| US presidential proclamation of 18-Sep-2026 extends the USD 100,000 payment requirement for certain new H-1B petitions to 21-Sep-2027 (India-born professionals were 71% of approved H-1B beneficiaries); court challenges continue | IT | ⚡ In force | 20d old | 🟡 MED | United States (Presidential Proclamation) |
| SEBI 215th Board approves new Portfolio Managers Regulations 2026 (replaces 2020 regime; PRIM + Independent Fund Manager) | Financial Services | 📌 Notified | 14d old | 🟡 MED | SEBI |
| SEBI 215th Board approves Settlement Regulations 2026 — formula-based settlement amount, pre-SCN settlement notice, fast-track under Rs 10 lakh | Financial Services | 📌 Notified | 14d old | 🟡 MED | SEBI |
| SEBI permits FPIs to trade non-agricultural index and non-cash-settled commodity derivatives, with mandatory exit before tender period (T-3) | Financial Services | 📌 Notified | 14d old | 🟡 MED | SEBI |
| SEBI enables Depository Receipts on REIT/InvIT units, initially via the IFSC, to attract foreign capital | Realty | 📌 Notified | 14d old | 🟢 LOW | SEBI |
| SEBI raises Vault Manager minimum net worth from Rs 50 crore to Rs 75 crore and widens scope beyond Electronic Gold Receipts | Financial Services | 📌 Notified | 14d old | 🟢 LOW | SEBI |
| DGTR initiates an anti-dumping investigation into imports of Penicillin G and its salts from China (initiation of 28-Sep-2026; gazette CG-DL-E-06102026-276860 published 06-Oct-2026) | Pharma | 📝 Proposed | 10d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGTR initiates an anti-dumping investigation into imports of Isopropyl Alcohol (IPA) from the European Union, South Korea, Taiwan and the USA (initiation of 29-Sep-2026; gazette CG-DL-E-06102026-276878 published 06-Oct-2026) | Chemicals | 📝 Proposed | 9d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGFT Notification 41/2026-27 continues the RoDTEP scheme to 31-December-2026 for DTA units, Advance Authorisation holders, SEZ units and EOUs; Appendix 4R/4RE rates and value caps as applicable on 30-Sep-2026 continue unchanged | Exports | ⚡ In force | 8d old | 🟡 MED | Commerce & Industry (DGFT) |
| CBIC Notifications 52 & 53/2026-Central Excise cut the special additional excise duty on exported diesel from Rs 20 to Rs 16/litre and set ATF at Rs 10.50/litre and petrol at Rs 0.50/litre with effect from 1 October 2026 (domestic fuel duties unchanged) | Oil & Gas | ⚡ In force | 8d old | 🟡 MED | Finance (CBIC) |
| CBIC Notification 80/2026-Customs (N.T.) dated 30-Sep-2026 substitutes Tables 1-3 of Notification 36/2001-Customs (N.T.) from 1 October 2026: crude palm oil USD 1,229/MT, RBD palm oil 1,240, palmolein 1,248-1,251, crude soya bean oil 1,280, brass scrap 8,149/MT; gold USD 1,339 per 10 g and silver USD 1,965/kg; areca nuts unchanged at USD 11,574/MT | Metals | ⚡ In force | 8d old | 🟢 LOW | Finance (CBIC) |
| DGFT Notifications 39 & 40/2026-27 extend the Minimum Import Price condition on specified Chapter 29 chemical products (USD 111/kg CIF) and on Sulfadiazine API (Rs 1,774/kg CIF) to 30-November-2026 | Pharma | ⚡ In force | 8d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Notification 38/2026-27 extends the Minimum Import Price of Rs 67,220 per metric tonne (CIF) on specified Virgin Multi-layer Paper Board (ITC-HS 48059100, 48059200, 48059300, 48109200, 48109900) to 31-March-2027 | Paper & Packaging | ⚡ In force | 8d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGFT Notification 37/2026-27 extends Component II timelines of the Resilience & Logistics Intervention for Export Facilitation (RELIEF) under the Export Promotion Mission to 31-March-2027, citing the continuing West Asia crisis | Exports | ⚡ In force | 8d old | 🟢 LOW | Commerce & Industry (DGFT) |
| DGTR initiates the second sunset-review anti-dumping investigation into imports of Toluene DiIsocyanate (TDI) from China PR, Japan and Korea RP (initiation notification dated 30-Sep-2026) | Chemicals | 📝 Proposed | 8d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGTR initiates an anti-dumping investigation into imports of Sodium Cyanide (NaCN) from China PR, the European Union, Japan and Korea RP (initiation notification dated 30-Sep-2026) | Chemicals | 📝 Proposed | 8d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGTR initiates a countervailing duty (anti-subsidy) investigation into imports of Insoluble Sulphur from China PR (initiation notification dated 30-Sep-2026) | Chemicals | 📝 Proposed | 8d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGTR initiates an anti-dumping investigation into imports of Persulphates from China (initiation notification dated 30-Sep-2026) | Chemicals | 📝 Proposed | 8d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGTR initiates an anti-subsidy / countervailing duty investigation into imports of Uncoated Writing and Printing Paper from Indonesia (initiation notification dated 30-Sep-2026) | Paper & Packaging | 📝 Proposed | 8d old | 🟢 LOW | Commerce & Industry (DGTR) |
| DGFT Trade Notice 29/2026-27 dated 1-Oct-2026 reconstitutes the Sub-Committee on Trade Finance under the Niryat Protsahan sub-scheme (MSME, DFS, DGFT, CGTMSE, EXIM Bank, NCGTC; invitees ECGC, IBA, IFSCA, factoring NBFCs) | Exports | ⚡ In force | 7d old | 🟢 LOW | Commerce & Industry (DGFT) |
| SEBI circular dated 1-Oct-2026 requires stock brokers to display investor awareness message(s) on their trading apps and websites under Project Jagrook | Financial Services | ⚡ In force | 7d old | 🟢 LOW | SEBI |
| RBI issues final Amendment Directions to the Acquisition and Holding of Shares or Voting Rights Directions for Commercial Banks, Small Finance Banks, Payments Banks and Local Area Banks — simplifying the approval process for subsequent acquisitions of major shareholding in a banking company by mutual funds, insurance companies and pension funds; immediate effect (Press Release 2026-2027/1233, dated 01-Oct-2026) | Banks | ⚡ In force | 7d old | 🟢 LOW | Reserve Bank of India |
| RBI Master Direction on Note Sorting Machines dated 2-Oct-2026 (RBI/DCM/2026-27/473; DCM(NPD) No.S2154/18.00.014/2026-27): authentication and fitness-sorting standards consolidated, BIS-certified NSMs mandatory for future procurement, discontinued models phased out by 30-Jun-2027, quarterly calibration and testing; withdraws the 2009/2010/2022/2024/2025 circulars | Financial Services | ⚡ In force | 6d old | 🟢 LOW | Reserve Bank of India |
| President of India hosts President of the Swiss Confederation | Diplomacy | 📌 Notified | 3d old | 🟢 LOW | Rashtrapati Bhavan / MEA |
| CAQM deploys flying squads to curb paddy stubble burning | Environment / Agri | 📌 Notified | 3d old | 🟢 LOW | Environment (CAQM) |
| India and Japan launch Operational Manual for the Joint Crediting Mechanism | Climate / Energy | 📌 Notified | 3d old | 🟢 LOW | Environment / MEA |
| RBI to conduct Overnight VRRR auction under LAF on 06-Oct-2026 | Banks / Rates | ⚡ In force | 3d old | 🟢 LOW | RBI |
| Auction of Government of India Dated Securities | Rates / Fiscal | 📌 Notified | 3d old | 🟢 LOW | RBI |
| Directions under s.35A BR Act against six co-operative banks | Banks | 📌 Notified | 3d old | 🟢 LOW | RBI |
| Union Cabinet approves setting up of the Integrated Transport & Logistics Authority (ITLA) as a Special Purpose Vehicle — apex transport & logistics planning body: National Transport Master Plan (10-year+ horizon), technical appraisal and monitoring of GoI transport projects above Rs 500 crore, a National Transport Data Repository (GSTN e-way bill, FASTag, Vahan), and review of the National Logistics Policy 2022 | Infrastructure | 📌 Notified | 2d old | 🟡 MED | Cabinet (PIB Delhi) |
| Union Cabinet approves a Rs 10,000 crore Government of India commitment to the SME Growth Fund — a direct-equity Alternative Investment Fund for small and medium enterprises, majority allocation to small/medium manufacturing enterprises and Tier-II/III industrial clusters | Financial Services | 📌 Notified | 2d old | 🟢 LOW | Ministry of Micro, Small & Medium Enterprises (PIB Delhi) |
| Quality Control Orders notified for three types of woven sacks (Department of Chemicals & Petrochemicals; gazette CG-DL-E-06102026-276879, published 06-Oct-2026) | Paper & Packaging | 📌 Notified | 2d old | 🟢 LOW | Chemicals & Fertilizers (Dept of Chemicals & Petrochemicals) |
| RBI to conduct Overnight Variable Rate Reverse Repo (VRRR) auction under LAF on October 07, 2026 | Banks / Rates | ⚡ In force | 2d old | 🟢 LOW | Reserve Bank of India |
| RBI extends the Section 35A Banking Regulation Act, 1949 directions on Samarth Urban Co-operative Bank Ltd., Osmanabad (Maharashtra) | Banks | 📌 Notified | 2d old | 🟢 LOW | Reserve Bank of India |
| RBI Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 in force from 1-Oct-2026: single export+import framework, mandatory Export Declaration Form for service/software exports within 30 days of month-end, realisation period 15 months (18 months for INR-invoiced/settled), declaration-based EDPMS/IDPMS closure up to Rs 10 lakh, wider set-off and third-party settlement, merchanting-trade rules, mandatory AD-bank SOPs, and advance/irrevocable-LC only for future exports where proceeds are unrealised beyond one year | Financial Services | ⚡ In force | — | 🟡 MED | Reserve Bank of India |
Net sector read
| Sector | Items | Net direction |
|---|---|---|
| Banks | 3 | 🔀 Mixed |
| Banks / Rates | 1 | 🔀 Mixed |
| Financial Services | 3 | 🔀 Mixed |
| IT | 1 | 📉 Bearish |
🧭 Likely-affected NIFTY names by sector
| Sector | Policies this run | Representative NIFTY names (by index weight) |
|---|---|---|
| Financial Services | sebi-credit-risk-o-meter-debt-2026, sebi-merchant-banker-private-placement-exemption-2026, sebi-isin-private-placement-debt-review-2026, corporate-laws-amendment-bill-2026 +9 more | HDFCBANK 9.85% · ICICIBANK 9.45% · SBIN 3.98% · AXISBANK 3.39% · KOTAKBANK 2.80% · BAJAJFINSV ≈ · PFC F&O · RECLTD F&O · CHOLAFIN F&O · MUTHOOTFIN F&O · LICHSGFIN F&O |
| Chemicals | dgtr-adi-ipa-2026, dgtr-adi-tdi-2026, dgtr-adi-nacn-2026, dgtr-cvd-insoluble-sulphur-2026 +1 more | PIDILITIND F&O · SRF F&O · DEEPAKNTR F&O · AARTIIND F&O · NAVINFLUOR F&O · ATUL F&O |
| Exports | dgft-rcmc-exemption-3lakh, dgft-non-preferential-rules-of-origin-draft, dgft-psic-two-day-timeline, dgft-rodtep-extension-dec2026 +1 more | INFY 3.61% · CIPLA ≈ · DRREDDY ≈ · HCLTECH ≈ · SUNPHARMA ≈ · TCS ≈ · DEEPAKNTR F&O · SRF F&O · NAVINFLUOR F&O · KPRMILL F&O · TRIDENT F&O |
| Banks | rbi-sa-ccr-amendment-directions-2026, rbi-cva-framework-directions-2026, rbi-acquisition-directions-2026 | HDFCBANK 9.85% · ICICIBANK 9.45% · SBIN 3.98% · AXISBANK 3.39% · KOTAKBANK 2.80% · BAJAJFINSV ≈ · BANKBARODA F&O · PNB F&O · CANBK F&O · UNIONBANK F&O · IDFCFIRSTB F&O |
| IT | us-h1b-fraud-crackdown-act-2026, h1b-100k-fee-extension-2027 | INFY 3.61% · HCLTECH ≈ · TCS ≈ · TECHM ≈ · WIPRO ≈ · LTIM F&O · PERSISTENT F&O · COFORGE F&O · MPHASIS F&O · OFSS F&O |
| Metals | cbec-customs-tariff-value-75-2026, cbec-customs-tariff-value-80-2026 | ADANIENT ≈ · HINDALCO ≈ · JSWSTEEL ≈ · TATASTEEL ≈ · VEDL F&O · SAIL F&O · NMDC F&O · NATIONALUM F&O · HINDZINC F&O |
| Oil & Gas | cbec-petroleum-export-duty-sep2026, cbec-diesel-atf-export-saed-oct2026 | RELIANCE 7.83% · COALINDIA ≈ · ONGC ≈ · OIL F&O · PETRONET F&O · IGL F&O · MGL F&O · GUJGASLTD F&O |
| Pharma | dgtr-adi-penicillin-g-2026, dgft-mip-ch29-api-extension-nov2026 | CIPLA ≈ · DRREDDY ≈ · SUNPHARMA ≈ · DIVISLAB F&O · LUPIN F&O · AUROPHARMA F&O · TORNTPHARM F&O · ZYDUSLIFE F&O · ALKEM F&O |
| Infrastructure | cabinet-itla-2026 | LT 4.30% · IRB F&O · NBCC F&O · RVNL F&O · IRCON F&O |
| Power | nep-2026-draft-cabinet | NTPC ≈ · POWERGRID ≈ · TATAPOWER F&O · ADANIPOWER F&O · JSWENERGY F&O · NHPC F&O · SJVN F&O |
| Realty | sebi-reit-invit-depository-receipts | DLF F&O · GODREJPROP F&O · OBEROIRLTY F&O · PRESTIGE F&O · PHOENIXLTD F&O |
Index-wide (taxation-other-laws-amendment-bill-2026) — affects all NIFTY 50 sectors.
Representative NIFTY 50 constituents in each affected sector, index weights as of 2026-09-27 (≈ = weight estimated, not published per-name), plus large F&O names outside the index. Sector membership is factual; informational only — not a recommendation or a trade signal.
Sector read: The Banks heavyweights (36.5% of NIFTY) get two MEDIUM capital-framework directions - SA-CCR scope/netting clarity and a CVA framework with sector/credit-sensitive supervisory risk weights - both effective only from April 2027, i.e. a slow-burn compliance repricing rather than an earnings event. Financial Services gets three low-severity SEBI debt-market disclosures (Credit Risk-o-Meter, merchant-banker private-placement exemption, ISIN review). IT carries a proposed (not notified) US H-1B fraud-crackdown bill with sharply higher fines and bans - directionally bearish for the sector, but far from in force.
Watch next: The dated repricing clocks are distant: SA-CCR and CVA land 01-Apr-2027, and the H-1B bill remains proposed. The watchlist now carries 47 items with no effective date today; the RBI's Rs 2,00,000 cr 29-day VRRR auction today is a liquidity operation, not a policy change.
Cross-check: No pre-open policy headline exists to attribute the GIFT softness to - the tape's drivers are global yields, crude and the RBI-hike aftermath (04/05/06), not the sectors named by today's items. The H-1B proposal lands on IT, which was already Wednesday's weakest sector (Infosys -16.88 pts, IT index down) and reports TCS after the close - policy and price are aligned in direction, not yet in magnitude.
Sources checked: RBI press releases (rss + PR pages) ✅ · SEBI circulars listing (browser/curl) ✅ · PIB English all-India RSS (RssMain.aspx ModId=6) ✅ · PRS billtrack ✅ · GST Council (press-release / meetings / home) ✅ · DGFT notifications listing (browser) ✅ · DGTR What's New (curl) ✅ · Global overlay (news search: tariffs-on-India / H-1B / CBAM / steel quotas / sanctions) ✅
16. Layoffs & Job-Market Stress — The SIP-Retreat Early Warning JOB DATA AS OF 2026-08 (PLFS Monthly Bulletin Aug-2026, released 15-Sep-2026) / 2025-07 (EPFO provisional payroll data for Jul-2025, released 23-Sep-2025) - carried, not re-read (PIB/EPFO unreachable today)
Job-market stress: LOW — The 7-day window (02-Oct -> 08-Oct) carries eight rows. The largest fresh announcement is Royal Mail 2,500 (~2% of workforce, voluntary redundancies in head-office/support roles, no frontline delivery cuts) - a >=2,000-head single event, the only one this week; HubSpot 660 / ~7% (AI-driven, 06-Oct) and airBaltic 500-700 (~17-23% of a ~3,000-employee carrier in Chapter 11) remain in the window; India adds the Amazon Stores cut (fewer than 1,000, US/India/UK, announced 07-Oct), HSBC's UK wealth management cuts (about half of management/specialist roles, ~70% of financial advisers, absolute headcount undisclosed), the BusinessLine India-GCC pressure piece (Cambium ~200 closure, >400 GCCs under stress), Disney's 300 (third round this year), and IBAI's projection that IRDAI reforms put '10 lakh' insurance-distribution jobs at risk. The composite gate is nonetheless NOT met - the job-market data does not corroborate a turn: PLFS unemployment is stable at 5.0% (Aug-2026), the last readable EPFO print is still positive (+5.55% YoY, 21.04 lakh net members, 9.79 lakh new subscribers, Jul-2025, no 2026 release exists), and the AMFI SIP book sits at a record Rs 32,297 Cr (Aug-2026), so the household-income/SIP channel is not firing and headlines alone do not score ELEVATED. Adjacent AI-in-banking signals not given rows (below materiality): DNB ~400 Technology & Services roles, costs booked Q2-2027. What would flip it: the AMFI September-2026 SIP print due ~10-Oct-2026 (a first MoM decline alongside the FII selling streak) and the PLFS September-2026 bulletin ~mid-Oct (urban UR 6.8% is the tell). No real-time Indian SIP-cancellation series is published, so no cancellation rate is measured or implied. · SIP book reference ₹32,297 Cr
Material layoff announcements, last 7 days (≥500 heads or ≥5% of workforce).
| Company | Headcount | % of workforce | Announced | Severity | Source |
|---|---|---|---|---|---|
| Royal Mail (UK postal operator, EP Group / Daniel Kretinsky) | 2,500 | 2.0% | 2026-10-07 | ELEVATED | AFP via The Economic Times (07-Oct-2026, 21:08 IST) 'Royal Mail announces up to 2,500 job cuts': up to 2,500 positions 'representing about two percent of its workforce', planned as voluntary redundancies and non-replacement of leavers, head-office and support-function roles, to be completed by end-2027; 'no reductions in operational frontline roles in delivery and processing'; letter volumes down more than 70% from peak |
| HubSpot | 660 | 7.0% | 2026-10-06 | ELEVATED | CBS Boston / The Boston Globe / Quartz / The Business Journals / Fast Company (06-Oct-2026) and the 01-Oct-2026 SEC filing: restructuring eliminating ~7% of the workforce, nearly 660 roles, positioned around 'AI-driven outcomes'; $65-75M in charges, mostly Q4-2026 |
| airBaltic | 700 | — | 2026-10-05 | ELEVATED | Reuters (05-Oct-2026) / AviTrader (06-Oct-2026): between 500 and 700 positions across the Riga, Vilnius and Tallinn bases, roughly 17-23% of the airline's ~3,000 employees (headcount is the upper bound); collective-redundancy notice to Latvia's State Employment Agency; follows the Sept-2026 Chapter 11 filing |
| Amazon (Stores / retail unit) | — | — | 2026-10-07 | WATCH | Reuters via The Hindu BusinessLine (08-Oct-2026) 'Amazon cuts jobs in Stores unit as latest layoffs affect US, India and UK' and Business Insider (07-Oct-2026): Amazon cut 'fewer than 1,000' white-collar roles, primarily in the Stores e-commerce unit, with employees in the US, India and the UK affected; a spokesperson confirmed 'a small number' of roles; follows the ~30,000-job round that began last year and ran into January 2026; exact headcount not disclosed so none is asserted |
| HSBC (UK wealth management business) | — | — | 2026-10-07 | WATCH | Financial Times via Reuters / ETHRWorld (07-Oct-2026) 'HSBC plans job cuts across UK wealth business in AI push': about half of management and specialist roles in the business to be cut, reductions among financial advisers could reach ~70%; HSBC does not disclose the number of UK wealth staff (thought to be 'hundreds' of relationship managers), so no absolute headcount is asserted - positioned as an AI-integration push |
| Walt Disney | 300 | — | 2026-10-03 | WATCH | Los Angeles Times (02-Oct-2026) 'Disney cuts 300 workers, offers executives early retirement' / Yahoo Finance (03-Oct-2026) / Times of India (04-Oct-2026): third round this year (corporate HR/IT, then marketing/Pixar/ABC News/ESPN), 300 roles cut with a further TV reorganisation prepared; below the 500-head floor, carried as the ongoing media-sector cluster |
| India GCC sector (global capability centres; ~2,100+ centres) | — | — | 2026-10-07 | WATCH | The Hindu BusinessLine (07-Oct-2026) 'GCCs under pressure: Why some India centers are cutting jobs or closing': Cambium Networks shut its Bengaluru GCC in October (~200 employees) and Hy-Vee closed its India engineering centre in June (~150); Inductus Group estimates parent-company restructuring/global cost-cutting at 50-60% of India-GCC layoffs, AI-led productivity 15-20%, portfolio weakness 10-15%, closures/parent exits 5-10%; UnearthInsight says more than 400 GCCs could remain under stress over the next few years; no single-sector headcount published, so none is asserted |
| IRDAI distribution reforms (IBAI job-loss warning; India insurance distribution chain) | — | — | 2026-10-06 | WATCH | PTI via Rediff / Business Standard / The Tribune (06-Oct-2026): IBAI (800+ broker members) says IRDAI's consultation paper on commission caps and expense-of-management could cut intermediary revenue 60-70% and put '10 lakh' insurance-distribution jobs at risk over five years; an industry-body projection, not announced company cuts, so no headcount is asserted |
| Job-market indicator | Value | Change |
|---|---|---|
| EPFO net payroll additions (monthly) | 21.04 L | +5.5% YoY |
| EPFO subscribers (monthly) | 9.79 L | — |
| PLFS unemployment rate | 5.00% | 2026-08 (PLFS Monthly Bulletin Aug-2026, released 15-Sep-2026) / 2025-07 (EPFO provisional payroll data for Jul-2025, released 23-Sep-2025) - carried, not re-read (PIB/EPFO unreachable today) |
Layoff events: The 7-day window carries eight rows: Royal Mail's up-to-2,500 voluntary cuts (~2% of workforce, head-office/support, no frontline delivery cuts - the week's only >=2,000-head event), HubSpot 660 (~7%, AI-restructuring), airBaltic 500-700 (~17-23% of a carrier in Chapter 11), Amazon Stores fewer than 1,000 (US/India/UK), HSBC's UK wealth cuts (~half of management/specialist roles), Disney's 300 and an India-GCC pressure piece (Cambium ~200 closure).
Job market: The domestic proxy has not turned: PLFS unemployment is stable at 5.0% (Aug-2026), and the last readable EPFO print remains positive (Jul-2025, 21.04 lakh net members, +5.55% y/y, 9.79 lakh subscribers; no 2026 monthly release exists and the subscriber MoM change is not published). PIB/EPFO were unreachable today, so the block is carried with its as-of date.
SIP channel (the one that matters): The AMFI SIP book at a record Rs 32,297 cr (Aug-2026) says the household-income channel is not firing - the cushion against job jitters is intact. No real-time Indian SIP-cancellation series is published, so no cancellation rate is measured or implied.
NIFTY impact: Stress level LOW: headlines cluster but the job data does not corroborate a turn, so the crash precondition (layoffs clustering WHILE FIIs sell) is not active - the pairing to keep auditing, with the September AMFI print (~10-Oct) and the PLFS September bulletin (~mid-Oct) as the next tests.
🎯 Final Assessment — Today's Directional Bias
Overall Sentiment: 🔴 BEARISH
Confidence Level: MEDIUM
| Level | Value |
|---|---|
| Expected spot range (day) | 22,420 – 22,698 |
| Support zone | 22,451 – 22,527 |
| Resistance zone | 22,650 – 22,700 |
🔴 Bearish (45%)
- Trigger: The soft GIFT open holds below the 22,622 PP and the 22,600 combined-OI battle wall; FII supply continues and put writers defending 22,500 step aside as the global risk-off tape and the 30Y-at-2002-highs yield backdrop bite
- Target 1: 22,451 · Target 2: 22,356
- Invalidation: above 22700
⚪ Range-bound (35%)
- Trigger: —
- Range: 22,527–22,700
- Character: Compression pinned to the 22,650 max-pain / 22,622 PP confluence just under spot, with one-sided call writing above and the two-step put structure (22,600 then 22,000/21,500) below; TCS results after the close keep the session from committing.
🟢 Bullish (20%)
- Trigger: The 22,600 put wall is defended, the hawkish-RBI trade is deemed spent after one session, and a reclaim of the PP opens a short-covering squeeze into the 22,700-22,800 call cluster
- Target 1: 22,698 · Target 2: 22,794
- Invalidation: below 22500
Key Factors Driving Today's View
- The RBI's first hike in over three years (25bp to 5.50% on 07-Oct) landed hawkish and Nifty still fell 0.76% to 22,603.05; Polymarket now prices a December follow-up hike at 66.5% (+25.5pp d1), keeping pressure on banks and rate-sensitives (36.5% of NIFTY).
- FIIs are net sellers for nine consecutive sessions (Rs 6,121 cr on 07-Oct; ~Rs 33,413 cr over the last five; index-futures L/S 0.10 net short) while DII absorption shrank to 75.1% - the supply under every bounce is intact.
- GIFT Nifty's live tape is soft (22,556, -47.05 vs the close, -0.01% vs its own prev) after rejecting its early high, directionally consistent with the global risk-off and niftytrader's 'Gap-Down Expected'.
- The fresh 13-Oct chain is one-sided call-side: PCR 0.7124, net call OI +591.2 lakh vs put +210.6 lakh, zero call-OI reductions anywhere, call walls at 22,700/22,800/23,000 and max pain at 22,650, with the ATM straddle pricing 22,445-22,724 (279 pts).
- The global tape is genuinely hostile: the 30-year Treasury at a 2002 high (US 10Y 5.277%), Europe down 1.2-1.5%, Asia red, Brent back above $100 ($101.22) and DXY 102.24 - with the rupee a five-month low at 96.66 (97 crossed intraday Wednesday).
- Vol is mid-range, not fearful: India VIX 13.93 (+2.35%) with IV Rank 25.51 (Low) but IV Percentile 67.46 - cheap versus the year's extremes, mid versus the typical session, so the market is pricing little tail risk into a deteriorating tape.
- Technically spot sits above the flat 5-DMA (22,595) but 2.1% below the 20-DMA and far under the 50-DMA, with today's pivots PP 22,622 / S1 22,527 / R1 22,698 and the PP almost exactly on the 22,650 max-pain magnet.
- Breadth is weak and narrow: official A/D 0.73 with only 41.03% advancing, 8 positive vs 41 negative contributors (net -179.4 pts), and 5-/20-session nets at -1,546/-8,415 - the two-day relief advance did not turn breadth.
- The expert layer is aligned and conditional: PR Sundar expects a break of 22,500 (box 22,500-23,000, next box 'very very bad'), Sensibull makes 22,600 the decider (22,400 breaks open 20,000) and NiftyBuddy's 22,700-21,850 bear band has its top sitting on today's R1 and call wall.
- AI-bubble composite holds at 4/7 ELEVATED with Mag-7 concentration 34.9% just 0.1pp from the 35% line and the narrative hardened (Burry's fresh oligopoly essay, Dalio's 'classic bubble'), while TCS Q2 lands after the close into the weakest sector.
⚠️ Risk Warnings
- Corporate-results gap risk: TCS Q2 reports after market hours today and IT is the weakest large sector (Infosys broke below 1,000, IT index down Wednesday) - tomorrow's open carries the sector's reaction, not today's.
- The hawkish double: a first RBI hike in over three years into a Fed path pricing zero 2026 cuts at 95.55% is a structural EM-duration and strong-dollar headwind that caps relief rallies.
- Crude supply tail: Brent back above $100 with Polymarket still pricing 40% for military action against the Saudi East-West pipeline by Oct 31 - an import-bill and inflation risk sitting under the RBI's hawkish turn.
- FII supply plus a five-month-low rupee (96.66; 97 crossed intraday) is a self-reinforcing risk-off pairing - a further currency break would pressure flows and inflation expectations together.
- One-sided positioning cuts both ways: zero call-OI reductions means a reclaim of 22,700-22,800 can force a fast short-covering squeeze, so the bearish read has a defined two-sided edge at the 22,700 R1/call wall.
- Data disclosures in the footer: MCX ladder from niftytrader's server snapshot (MCX blocked, ATM IV null); AMFI flows are the August vintage (September due ~10-Oct); EPFO job data is Jul-2025 vintage; PR Sundar's video is the 07-Oct post-market report (no 08-Oct pre-market existed at run time); policy eGazette/income-tax/PIB-browser tiers unreachable.